
Does Renters Insurance Cover Storage Units?
Usually — renters insurance follows belongings into storage, but an off-premises cap of 10% of your property limit bounds the payout; scheduling bypasses the cap.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Usually — renters insurance extends to belongings in storage units, but most policies cap off-premises property at 10% of the personal-property limit. On a $30,000 policy, that is $3,000 inside the unit; everything above the cap is self-funded.
How off-premises coverage attaches to a unit
Property in a storage unit is property away from your residence, and that is where the cap lives. Most renters forms extend coverage to belongings wherever they are located — the coverage territory clause — but commonly limit away-from-home property to 10% of the personal-property limit. The math: a $20,000 contents policy caps at $2,000 inside the storage unit; a $30,000 policy caps at $3,000.
Everything above the cap is self-funded, which is why the unit's inventory — not the unit's rent — decides whether the coverage is adequate. Two checks before leasing: read the away-from-home wording on your form (some carriers cap higher or not at all), and total the replacement value of what is going in. If the total exceeds the cap, the three paths in the last section apply.
The facility's liability versus yours
Storage leases say plainly what the facility will not do: pay for theft, water, or fire damage to your unit absent proven negligence. That disclaimer shifts the risk to your policy, which is why every carrier's storage answer starts with your own coverage rather than the facility's.
The facility's insurance — often sold as a monthly add-on — covers the building and sometimes the unit's contents, but its terms vary and it typically excludes high-value categories. Climate control is a preservation decision, not an insurance transfer: it reduces the humidity and heat damage the facility disclaims, but no policy covers gradual deterioration. The unit decision that actually moves risk is security quality — cameras, gated access, unit alarms — because it changes the theft odds your coverage exists for.
The remote-property inventory
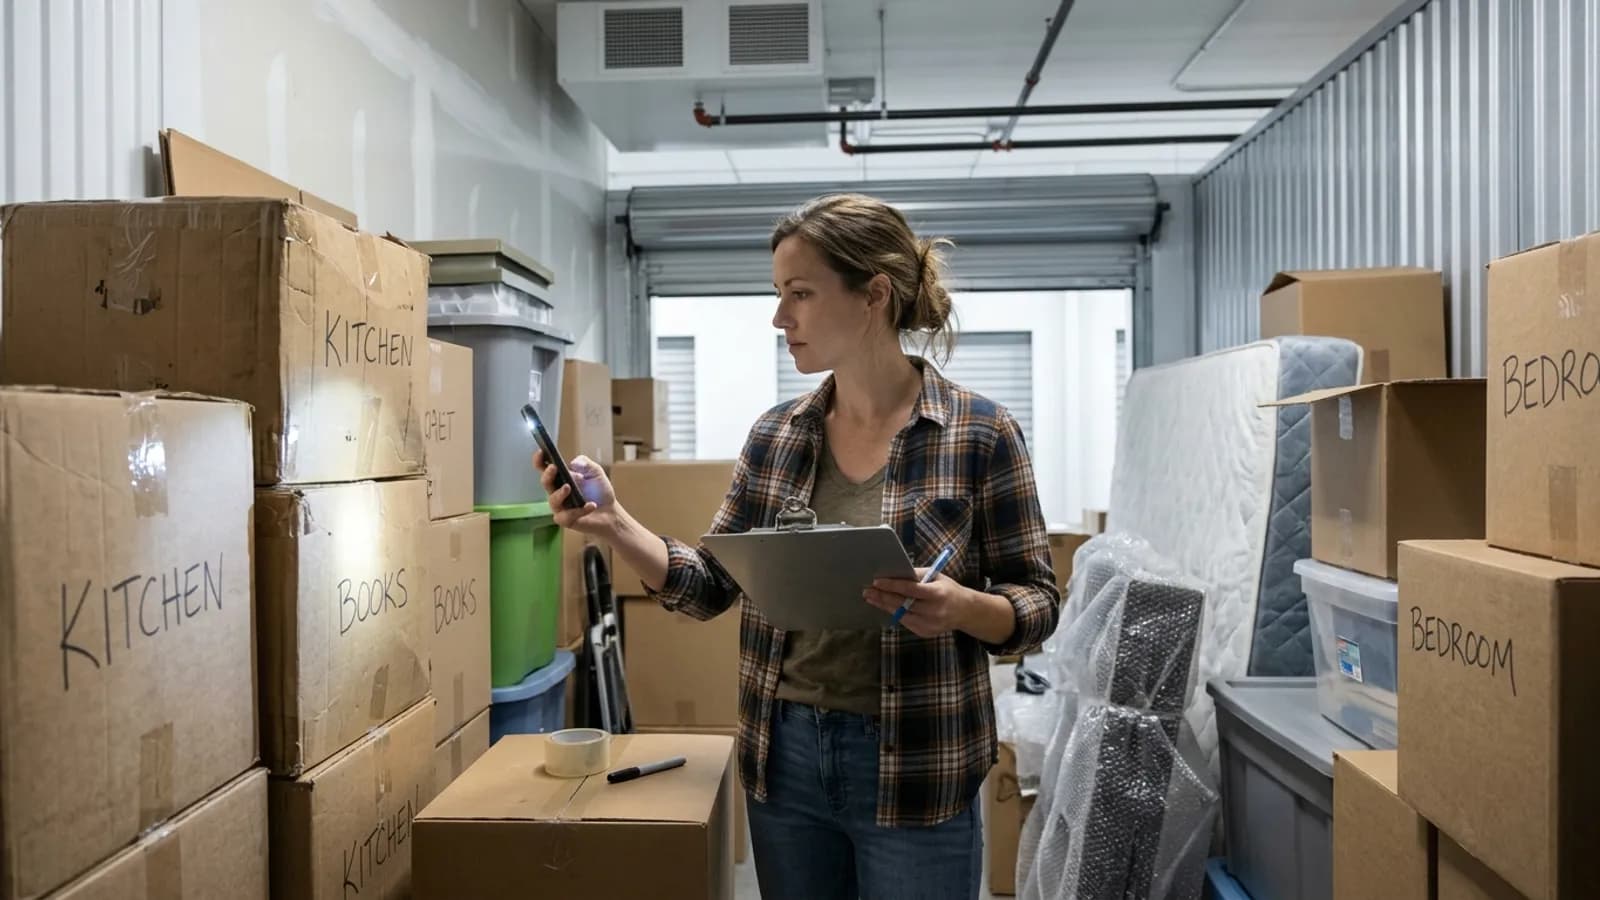
Property you cannot see still needs documentation, and the storage version of the inventory runs at pack-in time.
- Photograph each box's contents as it is sealed — the photos prove what was in the unit.
- Label boxes to match the photos — the numbering makes the claim list verifiable.
- Keep the list and receipts in cloud storage — adjusters price documented losses, not remembered ones.
- Flag anything valuable for scheduling — instruments, heirlooms, and cameras escape the cap under itemized coverage.
The list serves the claim twice: it proves what was in the unit, and it proves the value that justifies raising the cap. Scheduling runs through scheduled personal property or a standalone personal-property floater, both of which carry their own full limit away from home. If a theft does happen, the claim process page covers the filing sequence.
Storage for students and between-leases movers
Summer storage is the classic cap encounter: students parking a dorm room's contents for three months discover the 10% cap mid-lease. The student insurance page covers the between-semesters gap, and the same math applies to anyone between apartments — the cap follows the person, not the lease calendar.
The between-lease timeline
The cap decision has a calendar. A one-month gap between apartments with $5,000 of belongings in a unit fits comfortably under the 10% cap of a $30,000 policy — no action needed beyond the inventory photos. A six-month deployment, a year abroad, or a household in storage that totals $10,000–$15,000 needs action: raise the contents limit (which raises the 10% ceiling with it at most carriers), add a storage endorsement where offered, or schedule the irreplaceable pieces. The action belongs at pack-in, when the inventory is fresh and the receipts exist — not at the theft, when the claim meets a cap nobody re-read.
Related guides
Storage-unit coverage borrows from the away-from-home and documentation questions:
- What Is Renters Insurance and How Much Does It Cost? — the policy the off-premises cap sits inside, at $15–$30 per month.
- Does Renters Insurance Cover Theft From My Car? — the other away-from-home theft claim, split across two policies.
- The 8 Renters Insurance Mistakes That Cost Tenants Money — the documentation habit the unit claim depends on.
- First Apartment Insurance Checklist — the pack-in inventory standard, applied room by room.
Sources
Frequently asked questions
Does renters insurance cover theft from a storage unit?
Yes, under off-premises coverage — usually capped at 10% of your personal-property limit. The facility's insurance does not cover your boxes, which is why the cap is the number to verify before filling the unit. A police report and an itemized inventory drive the claim.
Is water damage from a leaking storage roof covered?
If your form covers water damage to off-premises property, yes, subject to the cap. Sudden water events fare better than gradual seepage, which stays excluded. Document the leak and report it to the facility too — their negligence can make it a facility claim as well.
Is a flooded storage unit covered?
Surface-water flooding is excluded everywhere — a flood policy is the only fix. Water from a burst pipe inside the facility may be covered under your form's water wording, and the facility's liability may respond if their plumbing failed. The water's source decides, as always.
Can I raise my off-premises limit for storage?
Often. Some carriers sell higher off-premises limits or storage endorsements; others hold the 10% cap firm. Ask before leasing a large unit, and schedule irreplaceable items individually to bypass the cap entirely. Raising the contents limit raises the cap with it at most carriers.
How do I insure belongings worth more than the off-premises cap?
Three paths: raise the contents limit (raising the 10% cap with it at most carriers), buy a storage or higher off-premises endorsement where offered, or move genuinely valuable items — instruments, heirlooms — into scheduled coverage where they escape the cap.
How we researched this guide
Renters coverage is small and simple, but landlord requirements and state rules vary — so we verify both sides of the lease.
- What HO-4 policies cover (and the liability and loss-of-use mechanics) is verified against standard policy forms and DOI consumer guides.
- Landlord-side insurance requirements are framed against HUD tenant-rights resources, since required coverage limits appear in lease terms, not statutes.
- Cost figures are ranges by state and coverage limit, anchored to NAIC statistics.
- Disaster-aid expectations are set from FEMA guidance: federal assistance is not a replacement for coverage, and we explain exactly what it does pay.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HUD — tenant rights and responsibilities — state landlord-tenant rules that affect liability requirements.
- FEMA — renters and disaster assistance — what federal disaster aid does and does not cover for tenants.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Renters Insurance for Students: Dorms, Off-Campus, and the Fine Print
Dorm belongings ride on parents' homeowners policies at 10% of contents; off-campus apartments need the student's own policy at roughly $12–$18 per month.
Read guide
The Renters Insurance Claim Process: From Theft to Reimbursement
Renters claims are won by documentation — police report, photos before cleanup, itemized inventory — and most simple claims pay within one to two weeks.
Read guideWhat Is Scheduled Personal Property?
Scheduled personal property is items listed individually on a policy at appraised value — no deductible, broader perils, full-value payment at loss.
Read guideWhat Is a Personal Property Floater?
A floater is a scheduled personal property policy covering specific valuables — jewelry, cameras, bikes — at appraised value, no deductible, with broader perils.
Read guideWhat Is a Coverage Territory?
Coverage territory is the clause defining where a policy applies — US auto policies cover the US and Canada but exclude Mexico; property follows the location.
Read guide