
Travel Insurance: The Complete Guide
Travel insurance reimburses prepaid trip costs after covered cancellations and pays medical bills abroad — how policies work, what they cost, and when they pay.
53 in-depth guides
Why you can trust this guide
- Written by Amara Bennett, Former ACA enrollment counselor — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.

Adventure Sports Travel Insurance: Skiing, Diving, and Climbing Coverage
Standard travel policies exclude or cap adventure sports, and off-piste skiing, deep scuba, and climbing need riders or specialty coverage priced 10–40% higher.
Read guide
Cancel For Any Reason (CFAR) Coverage: How It Works and When It's Worth 50% More
Cancel For Any Reason (CFAR) coverage reimburses 50–75% of prepaid trip costs on a cancellation for any reason at all — for a 40–50% premium and four strict rules.
Read guide
Cruise Insurance: The Coverage Questions Land-Based Trips Never Ask
Cruise insurance covers what land policies never meet — missed ports, cabin confinement, shipboard medical, evacuation from foreign waters — at 5–10% of the fare.
Read guide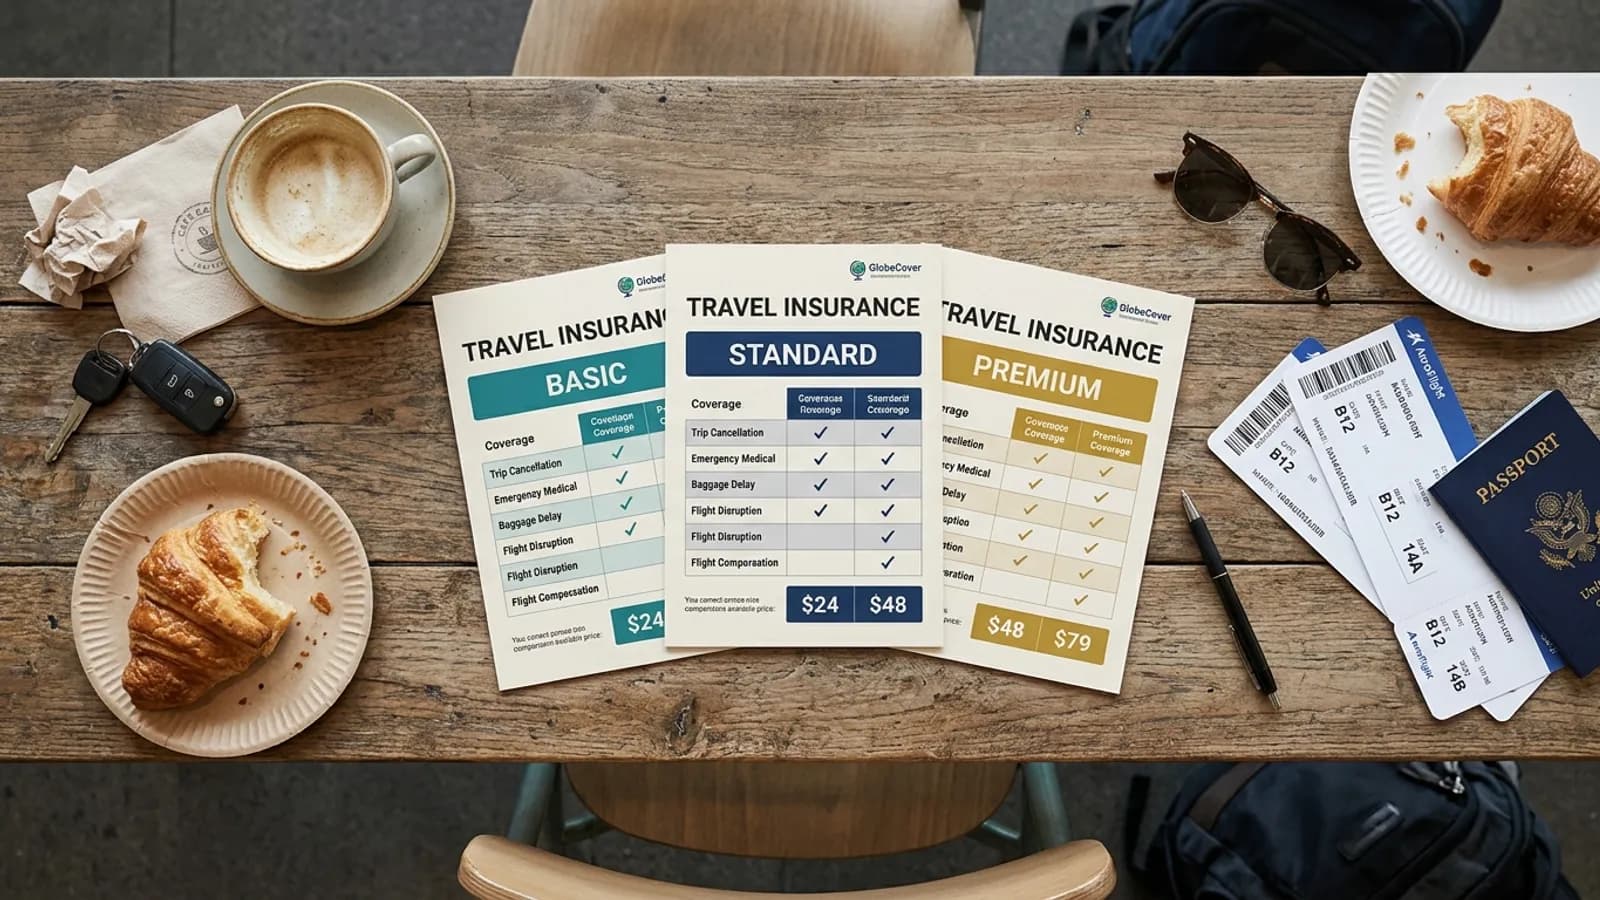
How to Choose the Best Travel Insurance Company (No Sponsored Rankings)
The best travel insurance company is the one whose underwriter, assistance line, and wording fit your trip type — five evaluation criteria, no sponsored rankings.
Read guide
Is Travel Insurance Worth It? A Decision Framework
Travel insurance is worth it when one bad outcome would hurt: expensive prepaid trips and international travel, where an evacuation can cost $50,000 or more.
Read guide
Travel Insurance Comparison: How to Compare Policies in 20 Minutes
Compare travel insurance by fixing coverage targets, then comparing five numbers: cancellation, medical, evacuation, exclusions, and price — the 20-minute method.
Read guide
Travel Insurance for Argentina: Do You Need It and What It Costs (2026)
Travel insurance for Argentina is worth it: Buenos Aires hospitals bill visitors and Patagonia evacuations run six figures. Budget 4–10% of trip cost for a policy.
Read guide
Travel Insurance for Aruba: Do You Need It and What It Costs (2026)
Travel insurance for Aruba is worth it: local care stabilizes, serious cases fly to Colombia or the US, and $500,000 evacuation coverage costs 4–10% of your trip.
Read guide
Travel Insurance for Australia: Do You Need It and What It Costs (2026)
Travel insurance for Australia is essential: US visitors get no Medicare access, outback evacuations run six figures, and a policy costs 4–10% of your trip.
Read guide
Travel Insurance for Bali, Indonesia: Do You Need It and What It Costs (2026)
Travel insurance for Bali is worth it: scooter accidents drive claims, serious cases evacuate to Singapore, and a $500,000 evacuation limit costs 4–10% of trip.
Read guide
Travel Insurance for Belize: Do You Need It and What It Costs (2026)
Travel insurance for Belize is worth it: the Blue Hole and remote cayes make $500,000 evacuation coverage the product, and a policy costs 4–10% of your trip.
Read guide
Travel Insurance for Brazil: Do You Need It and What It Costs (2026)
Travel insurance for Brazil is worth it: private hospitals treat visitors at international rates, dengue and traffic drive claims, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Canada: Do You Need It and What It Costs (2026)
Travel insurance for Canada is worth it: universal healthcare excludes visitors, non-resident hospital days bill privately, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Cancún and the Riviera Maya: Do You Need It and What It Costs (2026)
Travel insurance for Cancún and the Riviera Maya is worth it: hotel-zone clinics stabilize, serious cases fly to the US, and coverage costs 4–10% of trip cost.
Read guide
Travel Insurance for Colombia: Do You Need It and What It Costs (2026)
Travel insurance for Colombia is worth it: Medellín and Bogotá hospitals bill visitors, the nomad visa mandates coverage, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Costa Rica: Do You Need It and What It Costs (2026)
Travel insurance for Costa Rica is worth it: CIMA and Clinica Biblica bill visitors, zipline and whitewater claims need riders, and coverage costs 4–10% of trip.
Read guide
Travel Insurance for Cuba: Do You Need It and What It Costs (2026)
Travel insurance for Cuba is legally required: immigration enforces compliant medical coverage at entry, and a policy meeting the mandate costs 4–10% of trip cost.
Read guide
Travel Insurance for Dubai and the UAE: Do You Need It and What It Costs (2026)
Travel insurance for Dubai is worth it: residence visas mandate coverage, private hospitals bill at premium rates, and a $150,000-limit policy costs 4–10% of trip.
Read guide
Travel Insurance for Egypt: Do You Need It and What It Costs (2026)
Travel insurance for Egypt is worth it: Red Sea decompression and desert evacuations demand real coverage, and a $500,000-limit policy costs 4–10% of trip cost.
Read guide
Travel Insurance for Fiji: Do You Need It and What It Costs (2026)
Travel insurance for Fiji is essential: serious cases fly to Auckland or Brisbane at five-to-six-figure cost, and $500,000+ evacuation coverage runs 4–10% of trip.
Read guide
Travel Insurance for France: Do You Need It and What It Costs (2026)
Travel insurance for France is worth it: non-residents pay for care, Alpine ski injuries bill at private rates, and a policy costs 4–10% of your trip.
Read guide
Travel Insurance for Germany: Do You Need It and What It Costs (2026)
Travel insurance for Germany is worth it: statutory healthcare excludes tourists, hospitals bill visitors at premium rates, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Greece: Do You Need It and What It Costs (2026)
Travel insurance for Greece is worth it: island transfers run by helicopter and ferry, summer heat and mopeds drive claims, and coverage costs 4–10% of trip.
Read guide
Travel Insurance for Iceland: Do You Need It and What It Costs (2026)
Travel insurance for Iceland is worth it: visitors pay beyond emergencies, Laugavegur treks and gravel damage drive claims, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for India: Do You Need It and What It Costs (2026)
Travel insurance for India is worth it: Apollo and Fortis bill upfront, traffic and waterborne illness drive claims, and a policy costs 4–10% of your trip.
Read guide
Travel Insurance for Ireland: Do You Need It and What It Costs (2026)
Travel insurance for Ireland is worth it: visitors pay hospital charges, winter ferries and flights cancel routinely, and a policy costs 4–10% of trip cost.
Read guide
Travel Insurance for Italy: Do You Need It and What It Costs (2026)
Travel insurance for Italy is worth it: private care and repatriation bill visitors, Vespa injuries and heat drive claims, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Jamaica: Do You Need It and What It Costs (2026)
Travel insurance for Jamaica is worth it: public hospitals are strained, serious cases transfer to the US, and $500,000 evacuation coverage costs 4–10% of trip.
Read guide
Travel Insurance for Japan: Do You Need It and What It Costs (2026)
Travel insurance for Japan is worth it: superb hospitals bill tourists 100% upfront, earthquake and typhoon season add risks, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for Mexico: Do You Need It and What It Costs (2026)
Yes, travel insurance is worth buying for Mexico: US health plans often pay little there, serious cases fly to US hospitals, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Morocco: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Morocco: serious cases transfer to France, Marrakech moped and Atlas trekking claims are common, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for New Zealand: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for New Zealand: ACC pays accident care for visitors but bills illness in full, and premiums run 4–10% of the trip cost.
Read guide
Travel Insurance for Panama: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Panama: Panama City private hospitals are strong but regional care transfers out, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Peru: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Peru: Cusco altitude illness drives claims, Andes trekking needs evacuation coverage, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Portugal: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Portugal: emergencies are covered but D7 and nomad visas mandate private coverage, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Puerto Rico: Do You Need It and What It Costs (2026)
It depends for Puerto Rico: as a US territory your health plan may work there, so insure prepaid resorts and hurricane-season travel instead.
Read guide
Travel Insurance for Seniors: Coverage After 65 (and 75)
Senior travel insurance turns on the Medicare gap abroad, the pre-existing condition waiver, and higher medical limits — the coverage structure after 65 and 75.
Read guide
Travel Insurance for Singapore: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Singapore: private hospitals are world-class at US-level prices, and premiums run 4–10% of the trip's prepaid cost.
Read guide
Travel Insurance for South Africa: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for South Africa: private hospitals are world-class but safari regions are remote, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for South Korea: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for South Korea: hospitals bill visitors upfront and in full, and premiums run 4–10% of the trip's prepaid cost.
Read guide
Travel Insurance for Spain: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Spain: public emergencies are excellent but nomad visas mandate private coverage, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Switzerland: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Switzerland: ski injuries bill five figures quickly at Swiss prices, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Thailand: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Thailand: private hospitals bill foreigners premium rates, motorbike accidents drive claims, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for the Bahamas: Do You Need It and What It Costs (2026)
Travel insurance for the Bahamas is worth it: Nassau stabilizes but serious cases fly to Florida, and boating claims make $500,000 evacuation coverage essential.
Read guide
Travel Insurance for the Dominican Republic: Do You Need It and What It Costs (2026)
Travel insurance for the Dominican Republic is worth it: resort clinics stabilize, serious cases fly to Miami for $30,000–$60,000, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for the Maldives: Do You Need It and What It Costs (2026)
Travel insurance for the Maldives is essential: atoll transfers run by seaplane and boat, decompression claims need dive coverage, and a policy costs 4–10% of trip.
Read guide
Travel Insurance for the Netherlands: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for the Netherlands: hospitals bill visitors fully, bike accidents are the injury signature, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for the United Kingdom: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for the United Kingdom: NHS emergency care is free but repatriation and private care bill in full, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Turkey: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Turkey: private hospitals are strong for the price, Istanbul earthquake risk matters, and premiums run 4–10% of trip cost.
Read guide
Travel Insurance for Vietnam: Do You Need It and What It Costs (2026)
Yes, buy travel insurance for Vietnam: local care is limited outside Hanoi and Ho Chi Minh City, serious cases fly to Bangkok, and premiums run 4–10% of trip cost.
Read guide
Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements
Travel medical insurance pays for treatment and evacuation abroad — no trip-cancellation benefits — the product for long stays, nomads, and Schengen visa rules.
Read guide
What Is Travel Insurance? Types, Coverage, and How It Works
Travel insurance reimburses prepaid trip costs after a covered cancellation or interruption and pays emergency medical and evacuation abroad — the product, defined.
Read guide
When to Buy Travel Insurance: The 14–21 Day Window Explained
Buy travel insurance within 14–21 days of your first trip payment — the window that unlocks the pre-existing condition waiver and CFAR eligibility for the trip.
Read guideTravel insurance is a short-term policy tied to one trip — it reimburses prepaid, nonrefundable costs if a covered reason cancels or cuts the trip, and it pays emergency medical and evacuation bills abroad, where most U.S. health coverage stops — priced at roughly 4–8% of the trip's prepaid cost. The guides below split the two products people confuse, price the coverage, and map the destination rules.
What travel insurance covers (and what it never covers)
Trip protection and travel medical are two different products sold under one name. Trip protection insures the money spent: trip cancellation reimburses 100% of insured nonrefundable costs when a covered reason stops the trip before departure, and interruption pays the unused portion plus the fare home when a covered reason cuts it short. Travel medical insures the traveler: treatment, hospitalization, and evacuation where the home health plan does not reach.
The exclusion list decides everything. Exclusions remove changed plans, work conflicts, and fear of travel from cancellation coverage, remove pre-existing conditions unless the early-purchase waiver applies, and make any storm or event already named at purchase time a foreseeable loss. Read the covered-reason list before buying, because the list — not the brochure headline — is the contract.
What travel insurance costs
Travel premiums price as a share of the trip:
| Profile | Typical cost |
|---|---|
| Comprehensive policy | 4–8% of prepaid trip cost |
| Example: $6,000 trip | $240–$480 |
| Cancel For Any Reason upgrade | +40–50% on the premium |
| Quote under 3% of trip cost | Trimmed limits — verify before buying |
| Quote over 12% of trip cost | Older traveler plus CFAR — verify, do not panic |
Age moves the medical rate steeply after 60–70, trip length and destination move the rest, and insuring only part of the trip prorates the payout. The Cancel For Any Reason (CFAR) coverage guide prices the one upgrade that covers "we just don't want to go."
How to use this guide set
- Long trips, visas, or living abroad → Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements covers the standalone medical product and the Schengen-style requirements.
- Cruising → Cruise Insurance: The Coverage Questions Land-Based Trips Never Ask handles shipboard medical, missed ports, and evacuation at sea.
- Skiing, diving, or climbing → Adventure Sports Travel Insurance: Skiing, Diving, and Climbing Coverage maps the activity exclusions and the riders that fix them.
The travel insurance cluster, mapped
The destination guides answer the two questions each country raises before the policy is priced: whether entry rules require coverage, and what treatment actually costs there. Some destinations make insurance de facto mandatory — visa-linked medical requirements and entry rules — while others leave the decision to the exposure, such as countries where serious cases are flown back to U.S. hospitals at evacuation prices. The per-destination cost share, the entry fine print, and the local medical reality are what the 42 destination pages carry; the guides below anchor the rest of the cluster.
Start here
- What Is Travel Insurance? Types, Coverage, and How It Works — the product, defined with real benefit limits.
- Is Travel Insurance Worth It? A Decision Framework — the exposure test that settles the question.
- Travel Insurance Comparison: How to Compare Policies in 20 Minutes — the five numbers that separate real coverage from trimmed quotes.
- When to Buy Travel Insurance: The 14–21 Day Window Explained — the deadline that unlocks the waiver and CFAR.
- Travel Insurance for Seniors: Coverage After 65 (and 75) — age bands, medical underwriting, and the worth-it math.
- How to Choose the Best Travel Insurance Company (No Sponsored Rankings) — claims paying, assistance networks, and underwriters.
Destination guides
Destination guides carry entry requirements, local medical realities, and the per-trip cost share:
- Travel Insurance for Mexico: Do You Need It and What It Costs (2026)
- Travel Insurance for Cancún and the Riviera Maya: Do You Need It and What It Costs (2026)
- Travel Insurance for the Bahamas: Do You Need It and What It Costs (2026)
- Travel Insurance for the Dominican Republic: Do You Need It and What It Costs (2026)
- Travel Insurance for Costa Rica: Do You Need It and What It Costs (2026)
- Travel Insurance for Italy: Do You Need It and What It Costs (2026)
- Travel Insurance for France: Do You Need It and What It Costs (2026)
- Travel Insurance for Japan: Do You Need It and What It Costs (2026)
- Travel Insurance for Canada: Do You Need It and What It Costs (2026)
- Travel Insurance for Dubai and the UAE: Do You Need It and What It Costs (2026)
- Travel Insurance for India: Do You Need It and What It Costs (2026)
- Travel Insurance for the Maldives: Do You Need It and What It Costs (2026)
- Travel Insurance for Puerto Rico: Do You Need It and What It Costs (2026)
- Travel Insurance for South Africa: Do You Need It and What It Costs (2026)
The decisions that define a travel policy
Four decisions build the policy. The insurable-amount decision adds up only prepaid, nonrefundable costs — insuring a refundable booking wastes premium and underinsuring a real one prorates the claim. The medical decision follows the destination: international travel needs real medical and evacuation limits, domestic travel mostly needs cancellation coverage. The flexibility decision chooses between the covered-reason list and the CFAR upgrade that waives it for 50–75% back. The timing decision is fixed: buy inside 14–21 days of the first payment or lose the two time-sensitive benefits.
Claim mistakes that get trips denied
- Skipping documentation — cancellation claims run on doctor letters, death certificates, and airline notices; collect evidence from the hour the covered event happens.
- Canceling before notifying the insurer — call the claims line when the event occurs, not after rebooking the trip.
- Under-insuring the trip — insuring $3,000 of a $5,000 trip prorates the payout on every claim.
- Buying late — no pre-existing waiver, no CFAR eligibility, and any storm named before purchase becomes a foreseeable loss.
- Assuming "any reason" — standard policies pay a list; the list is the contract, and it is readable before purchase.
Credit card benefits versus a policy
Premium cards bundle trip cancellation and interruption on card-paid fares, delay reimbursement, and lost-baggage coverage — real benefits, worth pricing before buying overlap. The gap is medical: card coverage rarely includes emergency treatment or evacuation abroad, and it never covers trips paid on a different card. The card covers the money; the policy covers the traveler. On international itineraries the two stack, and on prepaid-heavy domestic trips the card may be enough on its own.
Related guides
Travel insurance borrows from and hands off to the lines around it: the health policy that resumes at home, the auto policy that answers rental-car questions, and the property policies that cover belongings a travel bag benefit never fully replaces.
- Health Insurance: The Complete Guide — where U.S. major medical starts and stops, including abroad.
- Car Insurance: The Complete Guide — whether your policy or the rental counter should carry the damage waiver.
- Renters Insurance: The Complete Guide — off-premises theft coverage for belongings, at $15–$30 per month.
- Home Insurance: The Complete Guide — the personal-property line that backs up baggage benefits after a loss.
Sources
Frequently asked questions
What does travel insurance cover?
A comprehensive policy bundles four benefit groups: trip cancellation and interruption, which reimburse prepaid nonrefundable costs when a covered reason stops or cuts the trip; emergency medical care abroad; medical evacuation home; and baggage loss, delay, and travel-delay reimbursements. The covered-reason list defines cancellation coverage, and changed plans or work conflicts are never on it.
How much does travel insurance cost?
Comprehensive coverage prices at roughly 4–8% of the trip's prepaid cost — a $6,000 trip runs $240–$480. Trip cost, traveler age, trip length, and destination drive the rate, and the Cancel For Any Reason upgrade adds roughly 40–50% to the premium. A quote under 3% of trip cost usually signals trimmed medical or cancellation limits rather than a bargain.
Do I need travel insurance if I have health insurance?
For international trips, usually yes. Many U.S. health plans pay little or nothing abroad, Medicare covers almost no care outside the country, and a serious evacuation can cost $50,000 or more. For domestic trips your health coverage follows you, so the policy mainly protects the prepaid, nonrefundable trip cost against covered cancellations.
When should I buy travel insurance?
Within 14–21 days of the first trip payment. That window unlocks the two time-sensitive benefits: the pre-existing condition waiver and Cancel For Any Reason eligibility. Buying later still covers the standard benefits, but the waiver and CFAR are gone — and once a storm is named or an event is foreseeable, that cause is permanently excluded for the trip.
What does travel insurance not cover?
Standard policies never pay for changing your mind, work conflicts, or fear of traveling — cancellation coverage is defined entirely by its covered-reason list. Pre-existing conditions are excluded unless waived by early purchase, storms and events already known at buying are excluded as foreseeable, and most policies cap or exclude high-risk activities unless an adventure rider is added.
Is travel insurance worth it?
Worth it when one bad outcome would hurt: expensive prepaid, nonrefundable trips and international travel, where an evacuation alone can cost $50,000 or more. The test is the size of the loss, not the odds — a $150 loss is annoying, a $12,000 cruise loss is not. Cheap domestic trips with refundable bookings rarely justify the 4–8% premium.
How we researched this guide
Travel insurance pays on documented triggers, so our guides focus on what activates each benefit and what documentation the claim needs.
- Coverage triggers (trip cancellation reasons, medical evacuation standards, pre-existing waivers) are verified against policy wordings and the state DOI consumer guides that regulate them.
- Visa-entry insurance requirements (e.g., Schengen) are checked against U.S. State Department country guidance.
- Air-passenger rights cited in delay/cancellation guides come from U.S. DOT consumer rules, not airline policies.
- Destination health-risk context comes from CDC traveler health notices.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- U.S. State Department — travel — country conditions, visa insurance requirements, and emergency assistance programs.
- CDC — traveler health — destination health risks and vaccination requirements that affect medical coverage.
- U.S. DOT — Aviation Consumer Protection — airline passenger rules on cancellations, delays, and refunds.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.