
How to Choose the Best Travel Insurance Company (No Sponsored Rankings)
The best travel insurance company is the one whose underwriter, assistance line, and wording fit your trip type — five evaluation criteria, no sponsored rankings.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
There is no single "best travel insurance company" — there is the insurer whose underwriter, assistance operation, and policy wording match your trip type and claim risk. This page accepts no sponsored placements, so it delivers the evaluation criteria that decide real outcomes instead of a ranked list.
What "best" means for travel insurance
"Best" is a fit question, and five criteria do the fitting:
- Underwriter financial strength — the policy is a promise that pays months later; an A-range financial strength rating from AM Best or a similar agency is the sane floor.
- Claims handling — state DOI complaint indexes and claim-filtered reviews show how denials and payouts actually run, not how the brochure reads.
- The assistance line — in a real medical event abroad, 24/7 staffing with medical professionals and direct provider payment matter more than payout limits; direct payment is the difference between the insurer guaranteeing a hospital bill and you floating a $40,000 admission on a credit card.
- Policy transparency — insurers that publish the full policy wording before purchase earn trust; "sample available on request" funnels are a yellow flag, because the exclusions page decides claims (see exclusions).
- Product fit — the trip type determines which benefits carry the claim weight, and products specialize accordingly.
How to evaluate a travel insurer
- Identify the underwriter behind the brand — the underwriter appears in the policy documents and often the page footer; the brand answers the phone, the underwriter pays the claim.
- Check the underwriter's financial strength rating — an AM Best lookup, A-range or better.
- Pull the complaint data — your state insurance department's complaint index, with NAIC as the data backbone.
- Filter reviews for claims filed — purchase reviews are marketing; claim reviews reveal the insurer's actual exclusion enforcement and payment speed.
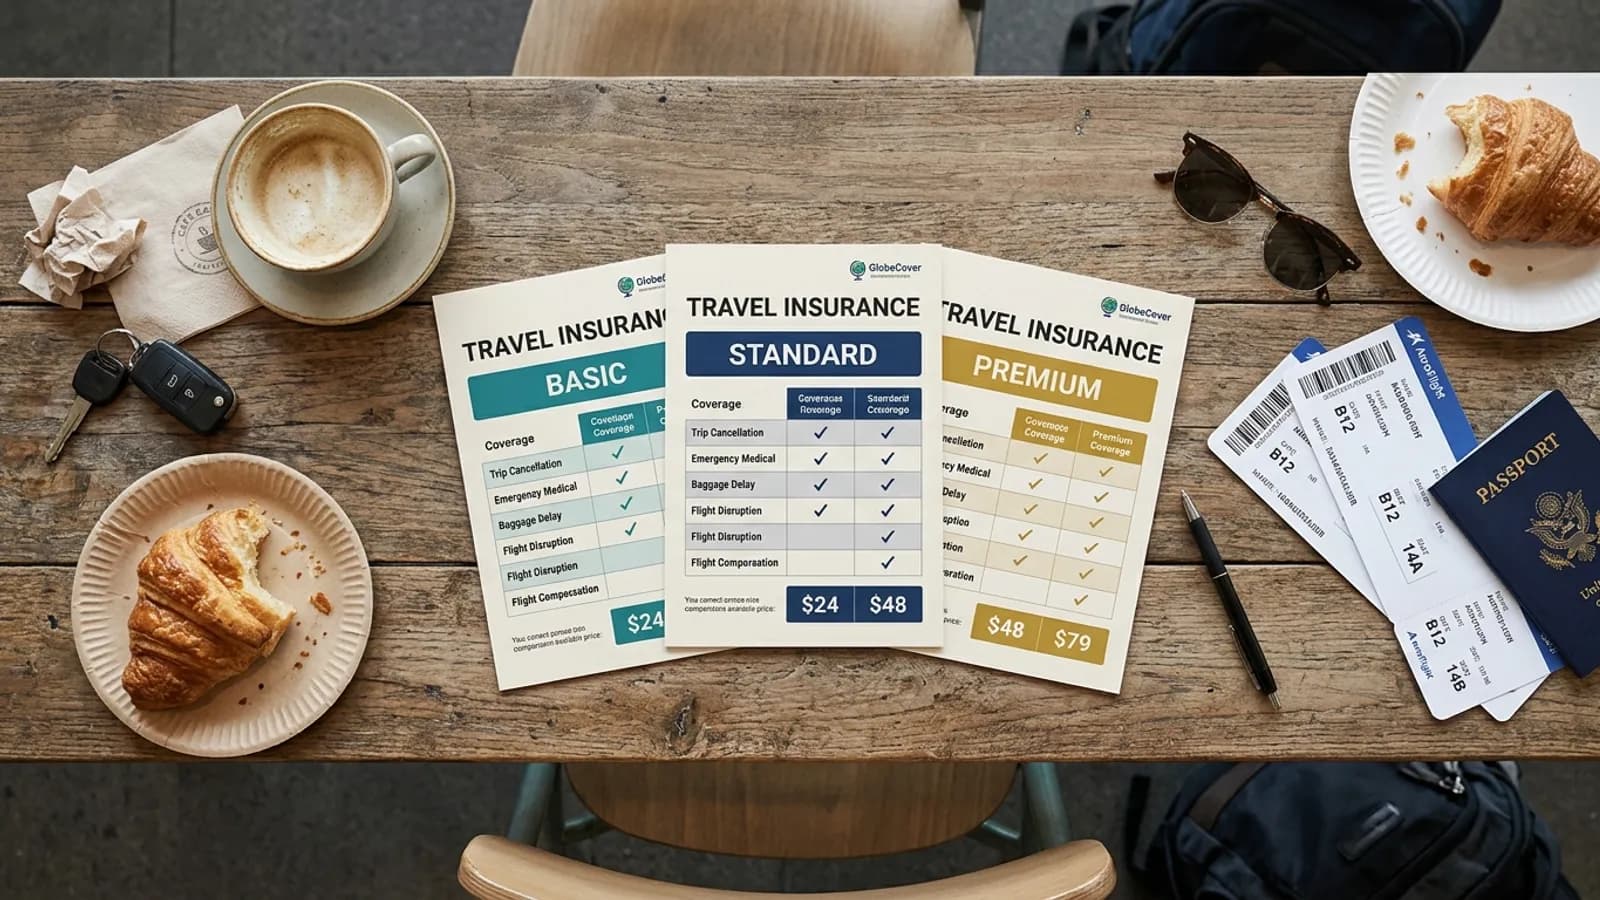
- Quote 3–5 carriers at identical settings — same trip cost, ages, limits, and add-ons, using the comparison method.
- Read the finalist's exclusions page end to end — the 15 minutes that decide claims.
- Buy inside the 14–21 day window — the pre-existing condition waiver and CFAR eligibility depend on it.
The travel insurance market's carrier categories
| Category | Model (not ranked) | Typical trade-off |
|---|---|---|
| National direct-to-consumer brands | Online quoting and purchase, no agent | Price transparency; service depth varies by underwriter |
| Aggregator and agent channels | One quote screen across multiple underwriters | Convenience for comparing wordings; the underwriter still decides claims |
| Trip-type specialists | Products built for adventure, cruise, senior, or long-stay risk | Better benefit fit; usually a higher premium |
| Medical-first and nomad underwriters | Monthly-renewing medical products without trip benefits | Duration flexibility; no cancellation or baggage coverage |
The categories describe distribution and product models, not quality. The same underwriter can sit behind several brands, which is why the underwriter check outranks brand recognition — and why "cheap" and "unsafe" are different questions: price tracks the product, while claim-paying ability tracks the underwriter's rating (see what an insurance carrier is for the entity behind the policy).
Red flags when shopping
- An unrated or weakly rated underwriter behind a polished marketing brand
- Sample policies available only "on request" instead of published documents
- An assistance line that reimburses instead of guarantee-paying providers
- Review pages full of purchase praise but silent on claim outcomes
- CFAR terms buried — 48-hour notice rules and 50–75% reimbursement mechanics (see CFAR coverage)
- Coverage levels on quote screens that quietly differ between carriers
Trip-type evaluation notes
The best carrier is trip-dependent because products specialize. Cruise trips reward carriers with strong evacuation limits, cabin-confinement benefits, and missed-port handling (see cruise insurance). Adventure itineraries reward specialists with real activity riders, because mass-market exclusion lists quietly delete the trip. Senior travelers reward carriers with stable pre-existing-condition waivers and high medical limits without age cliffs. Long-stay and digital-nomad trips are a different product family entirely — monthly-billed, medical-first policies.
The comparison method that works: name the trip's two dominant risks (for a cruise, sea evacuation and prepaid fare; for trekking, altitude medical and rescue), then score carriers on those two before price. The trip decision framework sizes the exposure first.
The buyer's pattern changes the evaluation too. A once-a-year traveler evaluates on price, the exclusions page, and the assistance line. A four-trip-a-year traveler evaluates annual-product mechanics instead: per-trip duration caps, medical limits that renew each year, and whether the annual policy renews without re-underwriting after a claim. The same carrier can grade differently across those two buyer profiles, which is another reason no single "best" holds.
Most travel insurance brands are administratively light: marketing and service layers on policies written by a small number of underwriters, often through managing general agencies. That structure explains two shopping facts: identical policy wording under different brands is common, and a brand's claim reputation often tracks its underwriter's claims operation rather than its marketing. Rating first, brand second, price third.
Reading claim reviews takes two filters. Filter by claim type: complaints about denied cancellation claims where the traveler never read the covered-reasons list describe a market literacy problem, not carrier conduct. Filter by resolution: complaints that end with the state insurance department or a documented good-will exception are conduct signals (see claim denials); complaints that end with "they excluded my condition, which was indeed excluded" are wording signals. The useful review question is narrower than "is this company good": did this company pay this claim type, on this wording, at the speed its documents promise.
When a smaller or specialist carrier is fine
Size matters less than fit in travel insurance, because the underwriter's rating — not the marketing budget — backs the claim. A specialist adventure underwriter with an A-range rating and published wordings is a better fit for a dive expedition than a national brand whose exclusion list deletes the trip; the same logic holds for cruise and long-stay products. The small-carrier check mirrors the big-carrier check: rating, complaint data, published policy, direct-pay assistance. When all four pass, price can decide.
The policy types the rankings sit on
A "best travel insurance company" ranking is only meaningful once the product type is fixed, because the same carrier prices very different products:
| Product type | What it covers | When it fits |
|---|---|---|
| Comprehensive trip insurance | Trip cancellation/interruption + medical + baggage | The default for prepaid trips |
| Travel medical (standalone) | Emergency medical and evacuation only | Long stays, coverage-gap travelers |
| Cancel-for-any-reason (CFAR) upgrade | Refunds commonly 50–75% of prepaid costs for any reason, typically adding 40–50% to the premium | Uncertain plans, nonrefundable bookings |
| BG/Evacuation memberships | Evacuation logistics, not insurance | Adventure travel, remote regions |
The cost anchors that frame every comparison: medical evacuation commonly runs $40,000+ on a serious event and foreign hospitalization $60,000+ — figures from the evaluation section above — while comprehensive trip insurance typically prices at roughly 4–10% of the insured trip cost. A CFAR upgrade is the only product that pays when you simply change your mind, and it must be bought within 14–21 days of the initial trip payment at most carriers.
How we evaluate (methodology)
This page accepts no placement payments or affiliate compensation. The evaluation reads each carrier's sample policy rather than its marketing page, and checks the claim-time clauses in order: medical coverage limits and the pre-existing-condition waiver rules, evacuation benefit structure, cancellation coverage definitions, claim-filing windows and app support, and — the differentiator most rankings skip — the underwriter behind the policy, because the fronting brand is not always the risk taker. State insurance department complaint indexes finish the check.
The profile-to-product fit matrix
The same trip prices into five different products depending on who is traveling and what can go wrong. Match the profile first, the carrier second:
| Traveler profile | Product that fits | The clause that decides it |
|---|---|---|
| Family vacation, prepaid resort | Comprehensive trip insurance | Cancellation definitions and the CFAR window |
| Cruise (foreign ports, ship medical) | Comprehensive with high medical + evacuation | Ship-to-shore evacuation and port medical coverage |
| Adventure / ski / diving | Comprehensive + activity riders | The activity exclusion list — most policies exclude the headline sports |
| Long stay / digital nomad | Travel medical (standalone), renewable | Home-country coverage carve-outs and renewal rules |
| Senior / Medicare-eligible | Travel medical with pre-existing waiver | Medicare does not travel — the waiver purchase window (60–180 days) |
| Short cross-border trip | Travel medical budget product | The deductible and the network — not the trip-cost coverage |
The fit logic: cancellation coverage scales with prepaid, nonrefundable trip cost, while medical coverage scales with what your domestic health plan does abroad — usually very little. Two different buyers, two different products, same ranking page.
A travel claim from start to finish
Worked sequence for the most common serious claim — a medical event abroad:
- At the event: call the insurer's 24/7 assistance line before arranging non-emergency treatment; the assistance team directs you to in-network facilities and opens the claim file. For hospitalizations, the guarantee-of-payment call is the step that prevents a $60,000+ foreign hospital bill from landing on your card.
- Documentation: itemized invoices with diagnosis codes, prescriptions, proof of payment, police report for theft, and the physician's note for trip interruption. Claims deny on documentation gaps more than on coverage gaps.
- Filing: most carriers now file through app or portal within 90 days of the event; the claim number ties to the assistance-line record from step 1.
- Reimbursement: medical claims often pay direct-to-provider when the guarantee was issued; trip-cancellation claims reimburse the nonrefundable costs the policy's cancellation definition covers — the reason the cancellation clause mattered at purchase.
The evaluation consequence: carriers with 24/7 assistance lines that actually answer — and app-based filing with per-claim status tracking — turn the same coverage into a materially different experience. Complaint indexes capture the gap.
Pre-existing condition waivers: the clause that changes rankings
Travel medical coverage is uniquely strict about pre-existing conditions — and uniquely generous to early buyers. The look-back window on most policies runs 60–180 days before the effective date, and the pre-existing waiver (an add-on or automatic feature on comprehensive plans) erases that exclusion if the policy is bought within a short window after the initial trip payment — commonly 14–21 days, matching the CFAR window. For travelers over 65 — the demographic whose rankings matter most and whose claims are most likely to involve pre-existing conditions — the waiver clause is the ranking. A carrier that prices better but waives worse loses this segment's real comparison, and the waiver's fine print (stable condition definitions, the documentation it requires) is where the differences hide.
Related guides
These guides apply the evaluation criteria to the products and decisions around the purchase:
- Travel Insurance: The Complete Guide — the hub: what the product covers and how claims run.
- What Is Travel Insurance? Types, Coverage, and How It Works — the product being evaluated, defined component by component.
- Adventure Sports Travel Insurance: Skiing, Diving, and Climbing Coverage — the specialty market for activity risk.
- Travel Insurance for Seniors: Coverage After 65 (and 75) — where waiver quality and medical limits decide the carrier.
- Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements — the medical-first product family and its underwriters.
- What Does an Insurance Broker Do? — the agent and aggregator channel, explained.
Sources
Frequently asked questions
Who is the best travel insurance company?
There is no universal best — the right insurer depends on the trip type (cruise, adventure, family vacation), traveler ages, and claims service in practice. The honest evaluation checks the underwriter's financial strength rating, state complaint data, assistance-line quality, policy transparency, and product specialization for the trip.
What should I look for in a travel insurance company?
Five things: an underwriter with an A-range financial strength rating, a claims record checked through state insurance department complaint indexes, a 24/7 assistance operation that pays providers directly, policy documents published in full before purchase, and a product built for the trip type being insured.
How do I check a travel insurer's reputation?
Three free sources: the state insurance department's complaint index (NAIC maintains the underlying data), the underwriter's financial strength rating from AM Best or similar agencies, and customer reviews filtered for claims-filed experiences rather than purchase experiences. Claim stories are the product; purchase stories are marketing.
Are cheap travel insurance companies safe to buy from?
Check the underwriter, not the brand. Identical policies are often sold under several brands, and claim-paying ability tracks the underwriter's financial strength rating — an AM Best A-range rating is the standard floor for a product that may need to fund a six-figure evacuation.
Do travel insurers pay out most claims?
Paid claims concentrate in trip cancellation, emergency medical, and baggage, and policies pay when the event matches the covered-reasons list and the documentation exists. Denials cluster at pre-existing conditions and activity exclusions — both disclosed in the wording before purchase.
Should I buy from a comparison site or the insurer directly?
Prices are usually identical because the product is identical. Comparison sites win for seeing many wordings at once; buying direct can make service questions easier. Either way, the underwriter and the policy wording are the product, so verify both before paying.
How we researched this guide
Travel insurance pays on documented triggers, so our guides focus on what activates each benefit and what documentation the claim needs.
- Coverage triggers (trip cancellation reasons, medical evacuation standards, pre-existing waivers) are verified against policy wordings and the state DOI consumer guides that regulate them.
- Visa-entry insurance requirements (e.g., Schengen) are checked against U.S. State Department country guidance.
- Air-passenger rights cited in delay/cancellation guides come from U.S. DOT consumer rules, not airline policies.
- Destination health-risk context comes from CDC traveler health notices.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 17, 2026.
- U.S. State Department — travel — country conditions, visa insurance requirements, and emergency assistance programs.
- CDC — traveler health — destination health risks and vaccination requirements that affect medical coverage.
- U.S. DOT — Aviation Consumer Protection — airline passenger rules on cancellations, delays, and refunds.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Travel Insurance: The Complete Guide
Travel insurance reimburses prepaid trip costs after covered cancellations and pays medical bills abroad — how policies work, what they cost, and when they pay.
Read guide
What Is Travel Insurance? Types, Coverage, and How It Works
Travel insurance reimburses prepaid trip costs after a covered cancellation or interruption and pays emergency medical and evacuation abroad — the product, defined.
Read guide
Adventure Sports Travel Insurance: Skiing, Diving, and Climbing Coverage
Standard travel policies exclude or cap adventure sports, and off-piste skiing, deep scuba, and climbing need riders or specialty coverage priced 10–40% higher.
Read guide
Travel Insurance for Seniors: Coverage After 65 (and 75)
Senior travel insurance turns on the Medicare gap abroad, the pre-existing condition waiver, and higher medical limits — the coverage structure after 65 and 75.
Read guide
Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements
Travel medical insurance pays for treatment and evacuation abroad — no trip-cancellation benefits — the product for long stays, nomads, and Schengen visa rules.
Read guideWhat Does an Insurance Broker Do?
An insurance broker represents you, not one insurer — quoting multiple carriers, advising on coverage, and servicing claims, paid by carrier commissions or fees.
Read guide