
Pet Insurance: The Complete Guide
Pet insurance explained: what accident-and-illness policies cover and exclude, real monthly costs for dogs and cats, and the rules that decide claims.
9 in-depth guides
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
How Much Is Pet Insurance? Costs for Dogs and Cats
Pet insurance costs roughly $55–$70 per month for dogs and $25–$40 for cats with accident-and-illness coverage — how age, breed, and your three dials move the price.
Read guide
How to Choose the Best Pet Insurance (No Sponsored Rankings)
The best pet insurance is the policy whose claim-time clauses match your pet's breed risks — six criteria decide the outcome, not sponsored rankings.
Read guide
Is Pet Insurance Worth It? The Honest Math
Pet insurance is worth it as catastrophe protection, not as a savings account — a $600-per-year dog policy against $3,000–$10,000 emergency bills.
Read guide
Pet Insurance for Cats: Costs, Coverage, and Breed Notes
Cat insurance costs $25–$40 per month for accident-and-illness coverage — half of dog pricing — with claims concentrated in urinary blockages and kidney disease.
Read guide
Pet Insurance for Dogs: Costs, Coverage, and Breed-Specific Traps
Dog insurance costs about $55–$70 per month for accident-and-illness coverage — breed moves that number more than anything, so price your dog's signature risk.
Read guide
Pet Insurance for Puppies: When to Enroll and What to Watch
Enroll a puppy at 8 weeks — the earliest age most insurers accept — before any documented symptom becomes a permanent pre-existing exclusion at every carrier.
Read guide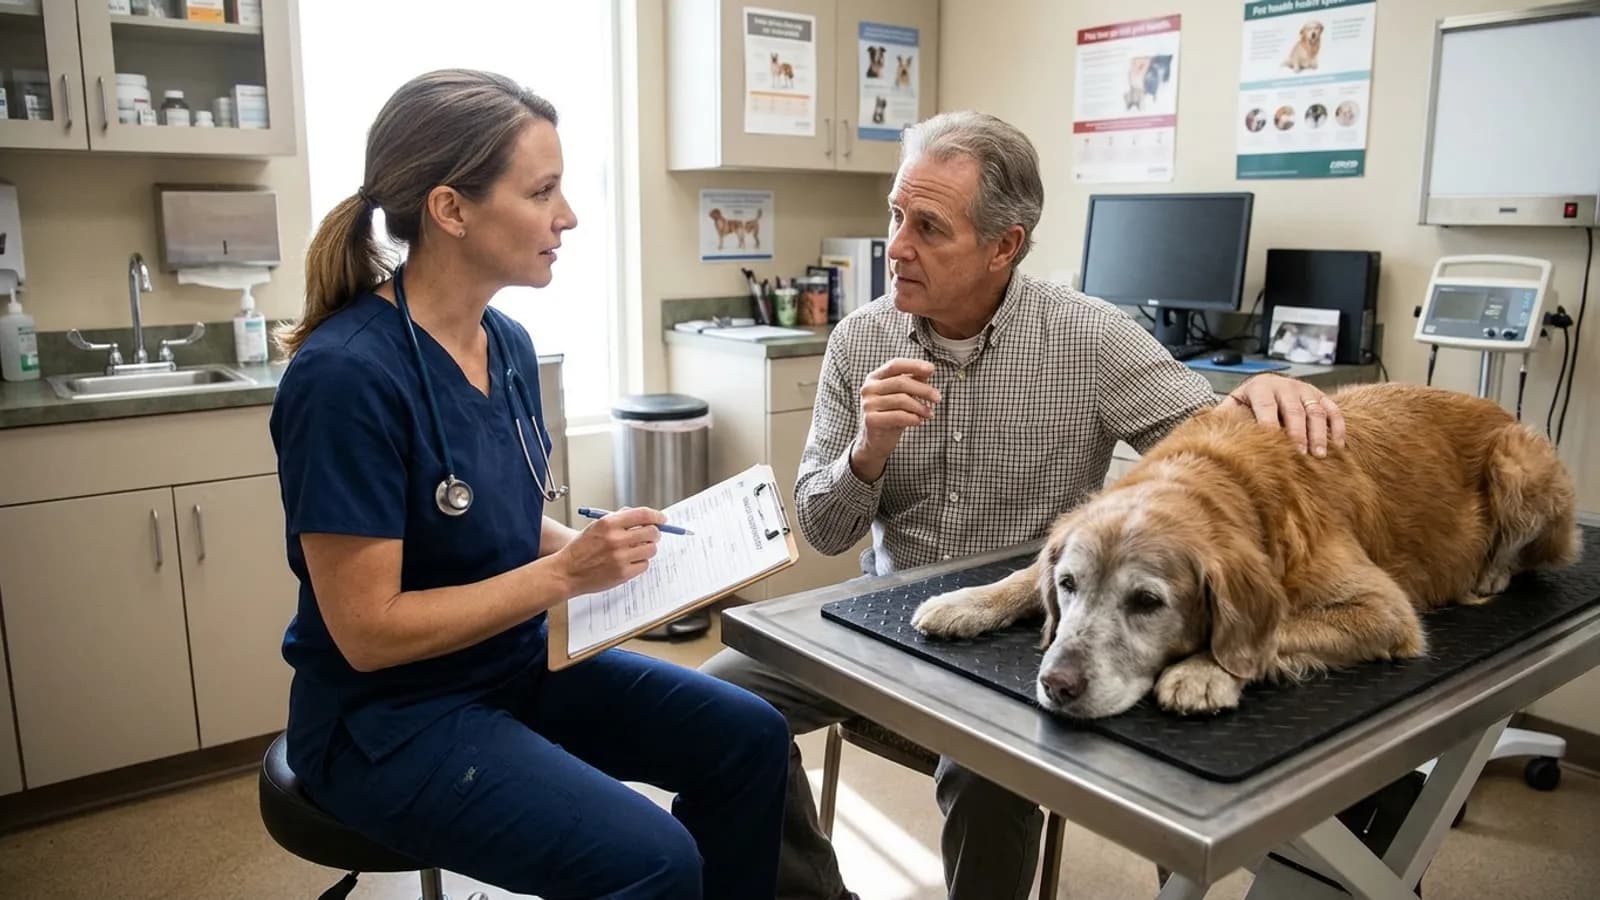
Pet Insurance Pre-Existing Conditions: The Rule That Decides Everything
Pet insurers exclude pre-existing conditions — anything documented before coverage starts — with curable windows and enrollment timing the only real controls.
Read guide
Pet Insurance vs Savings Account: The Honest Comparison
Pet insurance wins when catastrophe arrives before the fund does; savings wins for disciplined savers — the side-by-side math and the hybrid most households land on.
Read guide
Pet Insurance Waiting Periods: The Clause That Decides Claims
Pet insurance waiting periods run 1–15 days for accidents, 14–30 for illness, and 6–12 for orthopedic conditions — anything noticed during the wait is excluded.
Read guidePet insurance reimburses 70–90% of eligible vet bills after your annual deductible — roughly $55–$70 per month for dogs and $25–$40 for cats — and the pre-existing condition rule makes enrollment timing the single decision that matters most.
What pet insurance covers (and what it never covers)
Pet insurance is reimbursement, not networks and copays. You pay any licensed vet at the counter, file a claim with the invoice, and the insurer repays your chosen percentage — typically 70%, 80%, or 90% — of eligible costs after the annual deductible, up to your annual or lifetime limit. Two policy types dominate: accident-only (injuries: breaks, swallowed objects, lacerations, toxin ingestion) and accident-and-illness (everything above plus cancer, diabetes, infections, allergies, and arthritis). Wellness riders prepay routine care — vaccines, exams, dental cleanings — at roughly break-even economics.
The exclusions decide more than the coverage list. Pet policies universally exclude pre-existing conditions, cosmetic procedures, and breeding costs, and most exclude routine care unless the wellness rider is added. Every exclusion locks in at enrollment, which is why the claim rules below matter more than the premium comparison.
What pet insurance costs
Monthly figures with standard accident-and-illness coverage; industry association (NAPHIA) averages run near $55–$70 for dogs and $25–$40 for cats:
| Policy type | Dog per month | Cat per month |
|---|---|---|
| Accident-only | $10–$20 | $6–$12 |
| Accident + illness | $40–$70 | $25–$40 |
| + Wellness rider (add-on) | +$10–$30 | +$8–$20 |
Four drivers move your quote. Species: cats insure for roughly half of dogs. Breed: flat-faced breeds (French Bulldogs, Pugs) and large orthopedic-risk breeds (Shepherds, Rottweilers, Bernese) price highest. Age at enrollment: premiums rise as pets age, so a 1-year-old locks a base that climbs gently while a 9-year-old starts high with conditions already excluded. Location: metro vet-cost levels feed the reimbursement math.
The dial math, worked
One dog shows the trade-off. A 4-year-old Labrador at 80% reimbursement with a $500 deductible quotes near $65 per month. Raise the reimbursement to 90% and the deductible to $100, and the quote approaches $95 per month — while your share of a $6,500 TPLO knee repair falls to about $1,140. Drop to 70% reimbursement with a $1,000 deductible and a $10,000 limit, and the quote falls near $45 per month — while the same surgery leaves you with roughly $2,650 out of pocket. The cheap configuration still caps your worst case; the question each household answers is whether the savings are worth the larger share of a claim.
The same arithmetic at the household level: a 2-year-old mixed-breed dog on a mid-dialed policy ($500 deductible, 80% reimbursement) quotes near $35 per month, or $420 for the year. One foreign-object ingestion — a $3,200 surgery — returns roughly $2,560 after the deductible and coinsurance. A claim-free year costs the $420 and buys the certainty that the $3,200 scenario is covered; that asymmetry is the entire product, and the worth-it question is whether the year's premium is a fair price for removing the tail risk.
The rules that decide claims
The pre-existing condition rule comes first. Anything documented before coverage starts — including anything noticed during the waiting period — is excluded permanently, at every major carrier. A few insurers cover a "cured" condition after 12 symptom-free months; most do not. Pet Insurance Pre-Existing Conditions: The Rule That Decides Everything explains the clause and the cure windows, and Pet Insurance for Puppies: When to Enroll and What to Watch covers why enrollment at 8 weeks is the cheapest decision you will ever make.
Waiting periods delay coverage, and the clock is unforgiving. Policies typically impose 1–15 day waits for accidents, 14–30 days for illness, and 6–12 months for orthopedic conditions such as cruciate tears and hip dysplasia — anything noticed during the wait is excluded. Pet Insurance Waiting Periods: The Clause That Decides Claims maps the clocks condition by condition.
How to use this guide set
- Choosing a carrier. How to Choose the Best Pet Insurance (No Sponsored Rankings) compares reimbursement bases (actual vet bill versus benefit schedule), bilateral-condition clauses, waiting periods, and rate stability — six criteria, no sponsored placements.
- Pricing your animal. The pet-type guides in the map below carry species-level pricing and the breed-specific traps, from brachycephalic airway surgery to dysplasia waiting periods.
- Testing the purchase. Pet Insurance vs Savings Account: The Honest Comparison runs the side-by-side math and lands on the hybrid most households actually choose.
The pet insurance decision framework
Policy type. Accident-and-illness is the product with real financial value; accident-only is a cheap floor for owners with strong savings; wellness riders are prepaid routine care, not insurance.
The three dials. Your annual deductible ($100–$1,000), reimbursement rate (70/80/90%), and annual limit ($5,000–unlimited) move the premium by 30–50%. A $250–$500 deductible with 80% reimbursement is the honest sweet spot for most households.
The insurer criteria. Reimbursement basis first: benefit-schedule plans read cheaper and pay less. Then the bilateral clause — a cruciate tear on one knee often leads insurers to treat the other knee as pre-existing, so how a carrier words that clause decides a large share of big-dog orthopedic claims. Dental-disease coverage, ongoing chronic-condition coverage (allergies, diabetes), and claim speed complete the list.
The alternative. A disciplined savings account beats insurance for routine-heavy years and loses to it in year one of a $6,000 surgery — the comparison guide above works both sides.
The pet insurance cluster, mapped
The card grid above lists every page in this cluster. These are the entry points:
Pet-type guides
- Pet Insurance for Dogs: Costs, Coverage, and Breed-Specific Traps
- Pet Insurance for Cats: Costs, Coverage, and Breed Notes
Coverage questions
Related guides
Pet insurance behaves differently from every other product on this site — no networks, cash reimbursement, exclusions locked in at enrollment — and its nearest conceptual neighbors are the human-premium products built on the same trade-offs.
- Health Insurance: The Complete Guide — the human-system contrast: networks, copays, and deductibles pet insurance deliberately skips.
- Dental & Vision Insurance: The Complete Guide — the other prepaid-routine-care product, with the same annual-maximum mechanics.
- Supplemental Insurance: The Complete Guide — fixed cash benefits for named events, the design pet accident-only riders echo.
- What Is an Annual Maximum? — the payout cap pet policies share with dental plans.
Sources
Frequently asked questions
How does pet insurance work?
Pet insurance is reimbursement, not networks: you pay any licensed vet at the counter, file a claim with the invoice, and the insurer repays your chosen percentage (typically 70–90%) of eligible costs after your annual deductible. There are no provider networks — emergency and specialty hospitals work the same as your regular vet. Plans are annual, and premiums rise as your pet ages.
How much is pet insurance for a dog or a cat?
Recent industry data averages roughly $55–$70 per month for dogs and $25–$40 per month for cats with accident-and-illness coverage. Accident-only policies run $10–$20 for dogs and $6–$12 for cats. Species and breed set the base, age at enrollment sets its trajectory, and your deductible, reimbursement percentage, and annual limit move the quote by 30–50%.
What does pet insurance not cover?
Every major insurer excludes pre-existing conditions — anything documented before coverage starts, including symptoms noticed during the waiting period. Most policies also exclude cosmetic procedures, breeding costs, and routine care unless a wellness rider is added. Waiting periods apply at the start: 1–15 days for accidents, 14–30 days for illness, and up to 6–12 months for some orthopedic conditions.
Is pet insurance worth it?
As catastrophe protection, yes; as a savings account, no. A dog policy at roughly $600 per year exists for the $3,000–$10,000 emergency — the TPLO knee repair, the foreign-object surgery, the cancer treatment — not for the $80 ear-infection visit. If a surprise $5,000 veterinary bill would strain your finances, the premium buys real protection; if you could self-fund it, a dedicated savings account works too.
When should I enroll my pet?
Enroll at 8 weeks — the earliest age most insurers accept — and ideally while the pet is symptom-free. The pre-existing condition rule is the reason: any documented symptom before coverage starts becomes a permanent exclusion at every carrier. Early enrollment also locks a lower base rate, so premiums climb from a lower starting point than late enrollment.
What is the difference between accident-only and accident-and-illness coverage?
Accident-only policies pay for injuries — broken bones, swallowed objects, lacerations, toxin ingestion — at $6–$20 per month. Accident-and-illness adds the diseases that actually dominate vet bills: cancer, diabetes, infections, allergies, arthritis, urinary blockages. It costs roughly $25–$70 per month depending on species. The illness half is where most of the financial value of pet insurance sits.
How we researched this guide
Pet policies differ more than most consumers expect — reimbursement model, exclusions, and waiting periods — so our guides decode the contract structure.
- Reimbursement mechanics (accident-and-illness vs wellness riders, deductible/coinsurance math, pre-existing-condition rules) are verified against sample policies and insurer rate filings.
- Enrollment and claims-market statistics come from NAPHIA's industry studies.
- Veterinary cost context comes from AVMA data, so 'is it worth it' math uses realistic treatment prices.
- Wellness-plan value is evaluated against published fee ranges, and we say plainly when self-insuring the routine care makes more sense.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- NAPHIA — North American Pet Health Insurance Association — industry-wide enrollment and claims statistics.
- AVMA — American Veterinary Medical Association — veterinary cost data and pet-health context for coverage decisions.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.