
Pet Insurance for Puppies: When to Enroll and What to Watch
Enroll a puppy at 8 weeks — the earliest age most insurers accept — before any documented symptom becomes a permanent pre-existing exclusion at every carrier.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Insure the puppy at 8 weeks — the minimum age most insurers accept — because every symptom documented before enrollment becomes a permanent pre-existing exclusion. Puppy insurance is less about this year's vet bills and more about which conditions the policy will still cover in year eight.
The enrollment-day decision
| Timing | Outcome |
|---|---|
| 8 weeks (adoption day) | Lowest base premium for life + zero documented symptoms = maximum insurability |
| After the first vaccination series | Fine — but any documented GI upset, cough, or limp in the interim is now pre-existing |
| After the first real problem | That condition is excluded forever at every insurer |
The premium savings from waiting are trivial; the insurability cost is not. See the waiting-period mechanics for how the clocks interact with symptoms.
What the policy covers in year one
- Accidents: swallowed socks and toys (the #1 puppy claim), fractures, lacerations
- Illness: parvovirus, kennel cough complications, GI disease, UTIs
- Hereditary conditions emerging early: luxating patella in small breeds, early dysplasia signs in large breeds
Not covered: vaccinations (wellness-rider territory), pre-existing anything, and — read the clause — curable puppy issues that recur (some policies treat recurring GI episodes as one ongoing condition).
The enrollment window that sets lifelong insurability
Puppyhood is the one moment when insurability is total: no documented history means no pre-existing exclusions, and premiums sit in the lowest age band. The mechanics reward early enrollment: illness coverage commonly starts after a 14-day waiting period, orthopedic coverage after 6–12 months — so a puppy enrolled at 8 weeks has full orthopedic insurability before its first birthday, exactly when growth-plate and cruciate issues first appear. Every month of delay adds documented history the carrier can exclude later. The single best move in puppy insurance is enrolling before the first full vet visit, not after it.
The three breed clauses to read before buying
- Hereditary/congenital definition — German Shepherds (dysplasia), Cavaliers (mitral valve disease), French Bulldogs (BOAS/airway), Dachshunds (IVDD): confirm the breed's signature condition is covered, not excluded by definition. The dog breed traps page lists each breed's signature risk.
- Bilateral conditions — a cruciate tear in one knee can mark the other knee pre-existing; large breeds need this clause confirmed.
- Orthopedic waiting period — 6–12 months at some insurers; the enrollment-exam waiver exists at qualifying carriers — ask before buying, not after the first limp.
What the first policy year actually pays for
Work a representative puppy year on a mid-dialed policy ($35 per month, $250 deductible, 80% reimbursement): $420 in premiums. Covered events in a normal puppy year: the swallowed-sock surgery ($2,800 bill → $2,040 back), the parvovirus hospitalization in unvaccinated litters ($1,800–$3,500 → mostly reimbursed), and the soft-palate or growth-plate issues in flat-faced and giant breeds. Not covered: the vaccination series, spay/neuter, microchipping, and routine deworming — those ride the wellness rider ($10–$25 per month) or stay out-of-pocket. The honest framing: the base policy exists for the two or three four-figure surprises of year one; the wellness rider is a budgeting tool, not insurance.
The puppy-year checklist
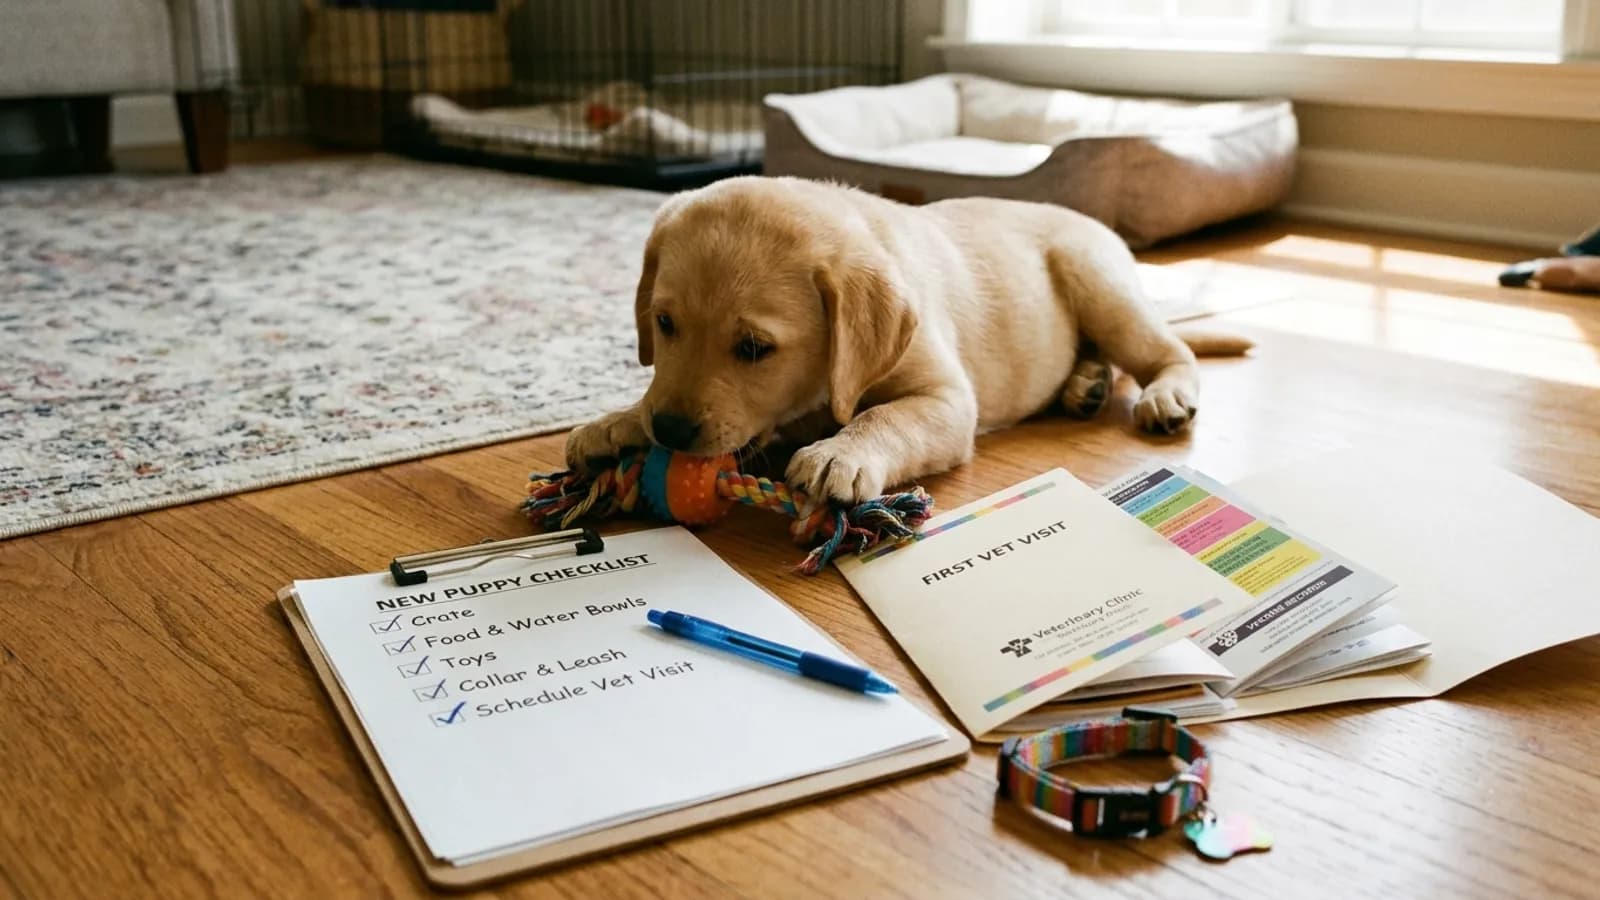
- Enroll at 8 weeks — before the first vet visit if possible; choose the policy first, then the exam documents a healthy baseline.
- Ask for the exam-day activation/waiver — some insurers start coverage or waive orthopedic waits after a clean initial exam.
- Budget the vaccine series directly — wellness riders mostly prepay routine care; decide honestly (the carrier criteria cover the wellness-rider economics).
- Fix the dials for the decade: a $500 deductible with 80% reimbursement — puppyhood is when the cheap configurations are most tempting and most regretted later.
- Set the renewal calendar — premiums rise with age; annual re-quoting keeps the base honest.
Related guides
Puppyhood is the entry point to every other pet insurance decision — the exclusion rule, the clocks, and the price all trace back to it.
- Pet Insurance Pre-Existing Conditions — the rule early enrollment is designed to defeat.
- Pet Insurance: The Complete Guide — the hub: coverage mechanics and claim flow.
- How Much Is Pet Insurance? — monthly pricing by species, breed, and age.
- Is Pet Insurance Worth It? — the catastrophe math that favors enrolling young.
- Pet Insurance for Cats — the kitten-side version of the timing rule.
Sources
Frequently asked questions
When should I insure my puppy?
At 8 weeks — the minimum age most insurers accept, and ideally on adoption day. Pre-existing conditions (anything documented before coverage starts, including during waiting periods) are excluded by every insurer, so the first cough, limp, or soft stool documented before enrollment can lock that condition out permanently.
What does puppy insurance cover?
Accident-and-illness policies cover the puppy classics — swallowed objects, parvovirus and other infections, injuries from falls and rough play — plus the later-life conditions (allergies, orthopedic disease, cancer) that trace back to the policy bought in puppyhood. Vaccinations and routine care need a wellness rider.
Does pet insurance cover vaccinations for puppies?
Not on standard accident-and-illness policies — the vaccination series is routine care, covered only by wellness riders (which mostly prepay what you'd pay anyway). The catastrophic value sits in illness coverage; budget the vaccine series directly, and treat any rider as a budgeting choice, not protection.
Can I enroll a puppy at six weeks old?
Some carriers accept enrollment at 6 weeks; most set the minimum at 8 weeks. Enrolling at the earliest allowed age starts the illness and orthopedic waiting clocks immediately, maximizing the window before growth-related conditions appear. The puppy needs no prior vet history — a lack of records is precisely why early enrollment carries no pre-existing risk.
Does puppy insurance cover spay or neuter surgery?
No — spay/neuter is elective preventive care, excluded from standard accident-and-illness policies. It is covered only under wellness riders (typically reimbursing a fixed schedule amount) or paid out of pocket. Complications from a spay/neuter can be covered on some carriers as illness or accident events — another clause to confirm in the sample policy.
What should I check before insuring a specific breed?
Three clauses: the hereditary/congenital condition definition (German Shepherds and dysplasia, Cavaliers and heart disease, French Bulldogs and airway issues), the bilateral condition rule (a cruciate tear in one knee can mark the other knee pre-existing), and the orthopedic waiting period — some insurers impose 6–12 months unless waived by a documented healthy-joint exam.
How we researched this guide
Pet policies differ more than most consumers expect — reimbursement model, exclusions, and waiting periods — so our guides decode the contract structure.
- Reimbursement mechanics (accident-and-illness vs wellness riders, deductible/coinsurance math, pre-existing-condition rules) are verified against sample policies and insurer rate filings.
- Enrollment and claims-market statistics come from NAPHIA's industry studies.
- Veterinary cost context comes from AVMA data, so 'is it worth it' math uses realistic treatment prices.
- Wellness-plan value is evaluated against published fee ranges, and we say plainly when self-insuring the routine care makes more sense.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- NAPHIA — North American Pet Health Insurance Association — industry-wide enrollment and claims statistics.
- AVMA — American Veterinary Medical Association — veterinary cost data and pet-health context for coverage decisions.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Pet Insurance: The Complete Guide
Pet insurance explained: what accident-and-illness policies cover and exclude, real monthly costs for dogs and cats, and the rules that decide claims.
Read guide
Pet Insurance Waiting Periods: The Clause That Decides Claims
Pet insurance waiting periods run 1–15 days for accidents, 14–30 for illness, and 6–12 for orthopedic conditions — anything noticed during the wait is excluded.
Read guide
Pet Insurance for Dogs: Costs, Coverage, and Breed-Specific Traps
Dog insurance costs about $55–$70 per month for accident-and-illness coverage — breed moves that number more than anything, so price your dog's signature risk.
Read guide
How to Choose the Best Pet Insurance (No Sponsored Rankings)
The best pet insurance is the policy whose claim-time clauses match your pet's breed risks — six criteria decide the outcome, not sponsored rankings.
Read guide
Pet Insurance Pre-Existing Conditions: The Rule That Decides Everything
Pet insurers exclude pre-existing conditions — anything documented before coverage starts — with curable windows and enrollment timing the only real controls.
Read guide