
Homeowners Insurance in Nebraska: Costs and What to Know (2026)
Homeowners insurance in Nebraska costs $1,700–$2,700 per year, with hail-alley deductibles, tornado corridors, and Missouri River flood memory shaping the market.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.

On this page
Homeowners insurance in Nebraska costs $1,700–$2,700 per year for a standard HO-3 policy on a typical single-family home. The state's position in hail alley, a tornado corridor through the east, and the 2019 Missouri River flood memory shape both pricing and policy structure.
What Nebraska homeowners pay
| Home profile / city | Typical annual cost |
|---|---|
| Statewide typical (standard HO-3) | $1,700–$2,700 |
| Omaha | $1,800–$2,900 |
| Lincoln | Near the statewide range |
| Eastern hail-corridor counties | Upper half of the range, percentage deductibles common |
| Rural western counties | Near the lower half, thinner carrier menus |
| Home + auto bundle with one carrier | Usually trims 5–15% off both premiums |
Omaha's metro premium runs above the statewide line because convective-storm loss activity concentrates there. Roof age is the biggest rating lever, and a recent hail claim follows both the owner and the property through CLUE reports for 5–7 years.
Nebraska's rules and regulators
The Nebraska Department of Insurance licenses carriers, reviews rate filings, and operates the consumer affairs division at doi.nebraska.gov. No state statute requires homeowners insurance; the floor comes from mortgage lenders, who mandate replacement-cost dwelling coverage while the loan exists and force-place insurance at 5–10 times market price after a lapse. Percentage wind/hail deductibles, typically 1–2% of dwelling coverage, are standard structure on Nebraska policies in the hail corridor, layered over the flat deductible for other perils. Escrowed premiums turn a hail-season renewal jump into a higher monthly mortgage payment without a letter from the carrier.
The Nebraska claim landscape
- Hail alley outbreaks — spring and summer supercells cross the eastern counties repeatedly, producing the state's dominant claim type; the percentage wind/hail deductible decides how much of every hail claim the homeowner pays.
- Tornado corridors — Grand Island's 1980 "Night of the Twisters" remains the benchmark event; tornado damage is covered wind damage, paying through the same wind/hail deductible structure.
- Missouri River and Platte flooding — the March 2019 flood overtopped levees near Offutt Air Force Base and forced thousands of evacuations, ranking among the state's costliest natural disasters; river flooding is excluded from the HO-3 and lives on an NFIP or private flood policy, which the NFIP vs private flood comparison lays out.
- Straight-line wind and downbursts — prairie thunderstorms deliver hurricane-force gusts across open counties, peeling roofs and flattening outbuildings.
- Winter ice and freeze claims — ice storms and deep freezes generate the cold-season mix of burst pipes and branch-load roof damage; sudden damage pays, gradual seepage is denied.
Coverage setup that fits Nebraska
- Dwelling at rebuild cost — keep Coverage A within 5% of a local builder's estimate; metro construction costs have climbed faster than rural labor rates.
- The hail deductible decision — a percentage wind/hail deductible trades premium for per-storm exposure; 2% on a $400,000 dwelling is $8,000 every hail event, and raising the flat deductible from $500 to $1,000 typically saves 10–25% on the premium.
- Roof valuation clarity — confirm whether the roof pays replacement cost or depreciated ACV before the next outbreak; the math is in ACV vs replacement cost.
- Flood stacking for river-adjacent homes — NFIP caps at $250,000/$100,000 with a 30-day wait and $30,000 of Increased Cost of Compliance; private flood covers levee-adjacent homes above the caps.
- Water backup endorsement — excluded by default at roughly $50–$250 per year; the sewer backup pattern spikes when saturated ground floods storm drains.
- Bundle discipline — a home-plus-auto bundle trims 5–15% off both premiums, compounding against hail-rated territory pricing.
Hail alley math: the deductible reshapes every roof claim
Nebraska's hail exposure does not change what the policy covers — hail is a covered peril — it changes what every hail claim pays. Carriers respond to the loss frequency with percentage deductibles and roof-valuation limits. Work the same hail claim ($45,000 in roof and siding damage, $400,000 dwelling coverage) under the structures Nebraska carriers use:
| Deductible option | Out of pocket | Claim payout |
|---|---|---|
| $1,000 flat | $1,000 | $44,000 |
| 1% ($4,000) | $4,000 | $41,000 |
| 2% ($8,000) | $8,000 | $37,000 |
Then the roof-valuation layer: an ACV roof endorsement on a 12-year-old shingle roof pays the depreciated value of a $12,000 replacement — often $6,000–$8,000 — while replacement-cost treatment pays the full job minus the deductible. The ACV-vs-RCV delta is routinely larger than the annual premium saved by accepting it, which is why eastern Nebraska owners read both line items before renewing.
Related guides
Nebraska's hail season and river flooding each get a dedicated playbook, and the same corridor runs into Iowa and Kansas.
- Home Insurance: The Complete Guide — the HO-3 structure and claim strategy behind every Nebraska policy.
- Home Insurance in Omaha, NE — $1,800–$2,900 per year in the state's largest hail market.
- Does Homeowners Insurance Cover Hail Damage? — how hail claims pay and what deductibles change.
- Homeowners Insurance in Iowa — $1,500–$2,400 per year across the Missouri River.
- Homeowners Insurance in Kansas — $2,000–$3,200 per year in the southern half of hail alley.
- Best Home Insurance Companies — comparing carriers on claims handling and financial strength.
Compare home insurance in other states
Requirements and rate bands move at the state line:
Sources
- Nebraska Department of Insurance — Nebraska consumer resources and complaint process
- FloodSmart / NFIP — flood policy caps, waiting periods, and zone rules
- III — Homeowners and renters insurance facts
Frequently asked questions
How much is homeowners insurance in Nebraska?
Homeowners insurance in Nebraska costs roughly $1,700–$2,700 per year for a standard HO-3 policy on a typical single-family home. Omaha runs $1,800–$2,900, and eastern Nebraska counties inside the hail corridor price toward the upper half because percentage wind/hail deductibles and roof claims concentrate there.
Why does Nebraska sit in hail alley?
Spring and summer supercells cross Nebraska repeatedly, producing some of the nation's highest hail-loss tallies. The state's response shows up in policy structure: many Nebraska carriers attach a separate percentage wind/hail deductible — typically 1–2% of dwelling coverage — charged per storm event on every hail claim.
Does Nebraska require homeowners insurance?
No state law requires homeowners insurance in Nebraska. Mortgage lenders set the requirement — full replacement-cost dwelling coverage while the loan exists — and homes in mapped Missouri River or Platte River flood zones add an NFIP or private flood policy. The Nebraska Department of Insurance handles consumer complaints.
Is flood damage covered by homeowners insurance in Nebraska?
No. River flooding is surface water, excluded from every standard policy. The March 2019 flood pushed the Missouri and Platte rivers over their banks and inundated homes near Offutt Air Force Base; NFIP coverage caps at $250,000 for the building and $100,000 for contents with a 30-day wait, and private flood fills above.
How does an ACV roof endorsement change a Nebraska hail claim?
An actual-cash-value roof endorsement pays the depreciated value of the roof, not the replacement. On a $12,000 shingle-roof replacement for a 12-year-old roof, ACV often pays $6,000–$8,000; replacement-cost coverage pays the full job minus the deductible. That gap routinely exceeds the annual premium saved.
What percentage wind/hail deductible is typical in Nebraska?
Most Nebraska policies in the hail corridor carry 1–2% of dwelling coverage for wind and hail losses. A 2% deductible on a $400,000 home is $8,000 per storm event, charged each time a hail outbreak crosses the property — the flat $1,000–$2,500 deductible still applies to fire, water, and liability.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Home Insurance: The Complete Guide
Homeowners insurance pays to rebuild, replace, and defend after fire, storms, and lawsuits — this guide maps coverage, exclusions, deductibles, and costs by state.
Read guideHome Insurance in Omaha, NE: Costs and Guide (2026)
Home insurance in Omaha costs $1,800–$2,900 per year. Hail-corridor deductibles and the 2019 Missouri River flood legacy shape the local coverage setup.
Read guide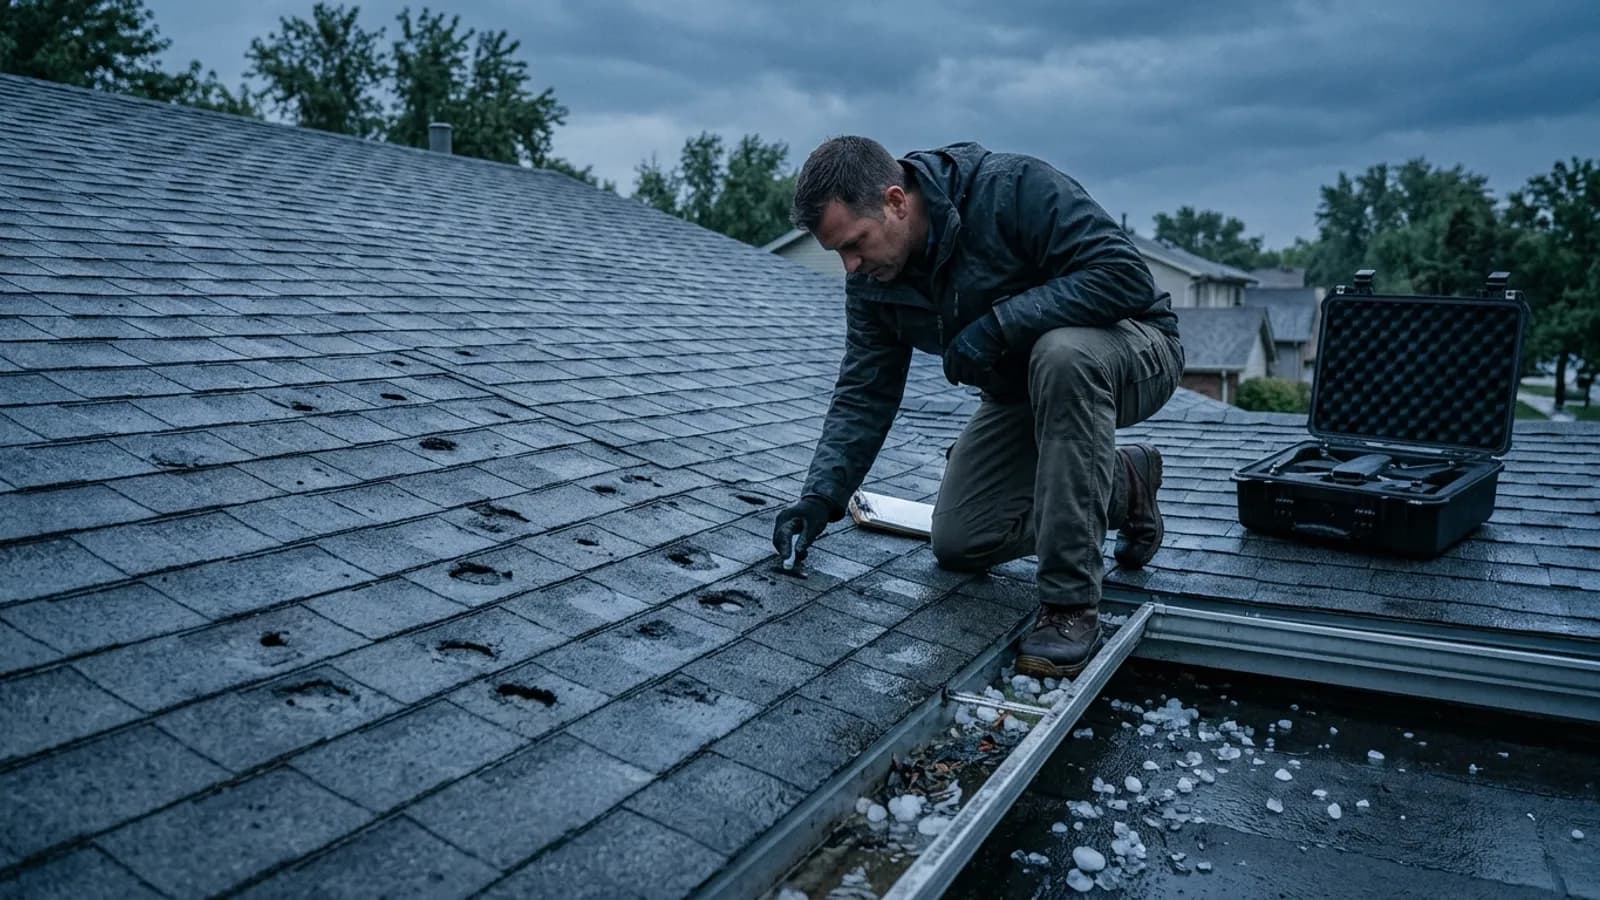
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance covers hail damage to roofs, siding, and contents, and hail-belt states price it with percentage wind/hail deductibles and ACV roof schedules.
Read guideHomeowners Insurance in Iowa: Costs and What to Know (2026)
Homeowners insurance in Iowa costs $1,500–$2,400 per year, with derechos, hail, and river flooding shaping what homeowners in each ZIP code pay.
Read guideHomeowners Insurance in Kansas: Costs and What to Know (2026)
Homeowners insurance in Kansas costs $2,000–$3,200 per year, with hail, tornadoes, and straight-line winds shaping what homeowners in each ZIP code pay.
Read guide
How to Choose the Best Home Insurance Company (No Sponsored Rankings)
Choose a home insurer on claims satisfaction, financial strength, coverage breadth, and state-market position — the criteria that replace sponsored rankings.
Read guide