
ACV vs Replacement Cost: The Claim-Payout Difference
Replacement cost pays today's price to rebuild; ACV pays that price minus depreciation. Learn which settlement basis your policy names before a claim arrives.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Replacement cost pays today's price to repair or replace damaged property; ACV pays that price minus depreciation. The two words on your declarations page decide claim payouts — check them before anything else.
Replacement cost and actual cash value in one line each
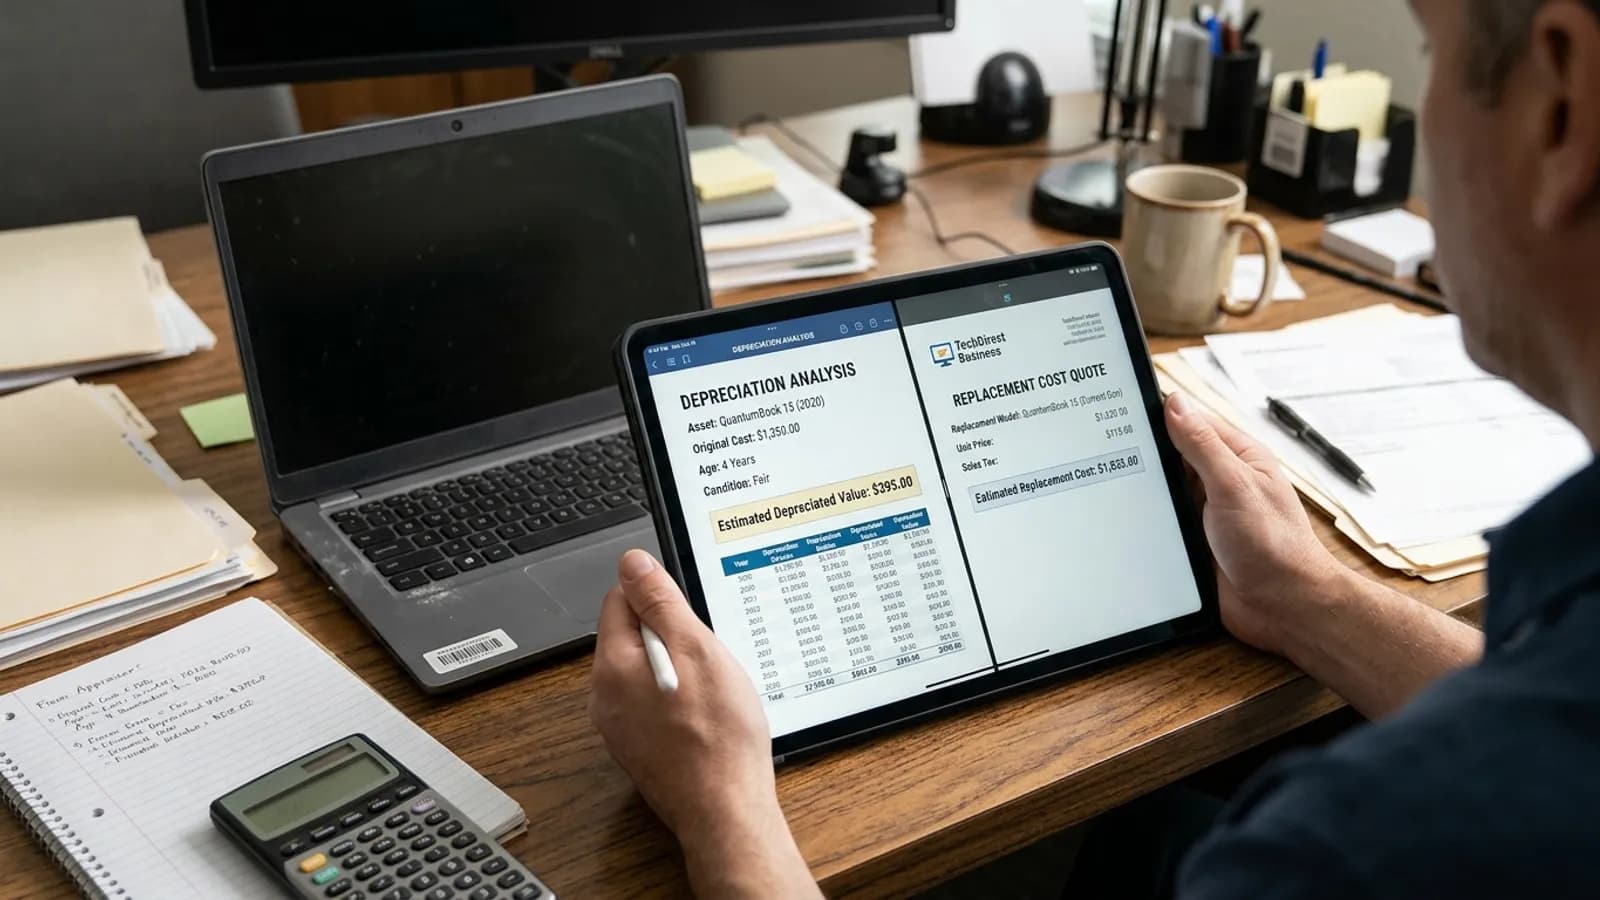
Replacement cost (RCV) pays what it costs to repair or replace damaged property at today's prices, without subtracting for age. Actual cash value (ACV) pays replacement cost minus depreciation — the value of a used item, not a new one. Both are settlement bases, not coverage types: the same peril list can pay out under either formula, and a single policy can use different bases for the dwelling, the roof, and the belongings.
Side-by-side comparison
| Dimension | Replacement cost (RCV) | Actual cash value (ACV) |
|---|---|---|
| Payout basis | Today's retail repair/replacement price | Replacement price minus depreciation |
| 15-year-old roof hail claim | $17,000 after a $1,000 deductible (on $18,000 work) | About $3,500 after the same deductible |
| 6-year-old TV | New comparable TV price | Used-market TV price |
| Premium | Higher | Lower |
| Holdback mechanics | Two checks — ACV first, depreciation released on repair proof | One check — settlement is final |
| Best fit | Owner-occupied homes you intend to rebuild properly | Deliberate cost-saving on old, low-value property |
When replacement cost is the better choice
Choose replacement cost wherever the premium gap is affordable — on the dwelling, on contents, and on the roof. The math from the table is the argument: the same $18,000 hail claim pays $17,000 under RCV and roughly $3,500 under ACV when insurers apply a 20-year useful life to a 15-year-old roof. Roof age appears on every application because it is the settlement formula in disguise, not underwriting trivia. Two upgrades sharpen RCV further: an extended replacement cost endorsement (commonly 25–50% above the dwelling limit) absorbs construction-cost inflation, and an RCV roof endorsement restores full settlement on older roofs.
When actual cash value is the better choice
Choose ACV deliberately, and only for property where the depreciated payout matches reality. Renters insuring modest contents, owners of older outbuildings, and landlords holding short-term investment flips are the defensible cases: the premium saving is real, and the property would be replaced with used-equivalent value anyway. The indefensible case is ACV on a home you intend to rebuild and live in — the discount buys a payout gap that runs five figures on the losses that matter most.
The two-check payout and the holdback
Replacement-cost policies rarely mail one check. The usual structure is ACV first: the insurer pays the depreciated value up front, repairs happen, and then the recoverable depreciation — the holdback — is released once you submit proof of completion: contractor invoices, paid receipts, photos. Many policies set the documentation window at 180 days from the date of loss, and missing it can forfeit the holdback. Two practical consequences follow. A claim that "pays less than expected" is often just the first check, not the settlement. And a contractor who offers to "cover your deductible" by inflating the invoice is committing fraud — insurers audit completion documents precisely because of that scheme.
Functional replacement cost and other cost-lowering variants
The RCV-versus-ACV choice is really three-way, because a third variant hides in some quotes: functional replacement cost. It pays the cost of repairing damaged material with cheaper, functionally equivalent materials — drywall for plaster, standard windows for custom ones. It prices below true RCV and suits simple homes, but it underpays on older homes with plaster walls, oak trim, or masonry that cannot be economically reproduced. Also check two riders: an RCV endorsement that extends replacement coverage to an older roof (the most common ACV trap), and an inflation-guard clause that nudges dwelling limits each year. The declarations page names which settlement basis applies to the dwelling, to the roof separately in some states, and to contents — the three can differ within one policy, and the annual policy audit includes that check among its steps.
Related guides
Settlement basis is one of three payout levers; the other two — the peril list and the limit — live on these pages.
- What Does Homeowners Insurance Cover? (And What It Never Covers) — the peril list and coverage buckets that feed the payout formula.
- The Home Insurance Claim Process: From Damage to Settlement — how the two-check timeline and supplements actually run.
- Does Homeowners Insurance Cover Roof Leaks? — where roof-age ACV schedules bite hardest.
- What Is Functional Replacement Cost? — the third settlement basis and when it fits.
Sources
Frequently asked questions
How is ACV actually calculated on a claim?
ACV equals today's replacement cost minus depreciation for age and wear. A common insurer method: replacement cost of $18,000 on a 15-year-old roof with a 20-year life means roughly 25% of value remains, so the ACV payout starts near $4,500 before the deductible. Insurers differ in how they set useful life, which is why identical roofs can receive different ACV figures.
Can I get replacement cost on an old roof?
Sometimes. Some carriers sell a replacement-cost roof endorsement for roofs up to a certain age (often 15–20 years), while others refuse RCV on any roof past about 10–15 years or pay a scheduled ACV table by shingle type. Compare that specific endorsement at quote time — it cannot be added after the hail claim is filed.
Does ACV vs replacement cost also apply to my belongings?
Yes. Contents are commonly paid at ACV unless you buy replacement-cost contents coverage, which is a cheap add-on compared with dwelling coverage. A 10-year-old TV has near-zero ACV; its replacement-cost payout is the retail price of a comparable new set. For electronics, furniture, and clothing, contents RCV is usually the highest-value dollar-per-premium upgrade in the policy.
Is replacement cost coverage worth the higher premium?
At claim time, almost always. The depreciation deduction on a roof or a household of contents runs from thousands to tens of thousands of dollars, while the premium gap between an ACV and an RCV policy is typically a modest percentage — often just a few dollars per month. The exception is deliberately self-insured, older property you would replace cheaply anyway; there, ACV coverage matches the real exposure.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

What Does Homeowners Insurance Cover? (And What It Never Covers)
A standard HO-3 covers fire, wind, hail, theft, and burst pipes — and never floods, earthquakes, or gradual damage. The coverage buckets, exclusions, and fixes.
Read guide
The Home Insurance Claim Process: From Damage to Settlement
How a homeowners claim actually works: mitigation, documentation before cleanup, the adjuster visit, the two-check payout, supplements, and common mistakes.
Read guide
Does Homeowners Insurance Cover Roof Leaks?
Homeowners insurance covers leaks caused by a covered peril — storm hail, wind, a fallen tree — while leaks from age, wear, or deferred maintenance are excluded.
Read guideWhat Is Functional Replacement Cost?
Functional replacement cost pays to repair with modern materials that do the same job — drywall for plaster — trimming premiums 10–25% on older homes.
Read guide