
Glossary
What Is a Depreciation Holdback?
A depreciation holdback is the portion of a replacement-cost claim the insurer withholds at first payment: the initial check pays actual cash value — replacement cost minus depreciation — and the holdback, the depreciation difference, releases only after invoices prove the repairs or replacements are complete.
How it works
Replacement cost coverage pays to buy new, but most policies pay in two stages to prevent windfalls for unreplaced property. The estimate carries two figures per line item — full replacement price and depreciated value — and the first check pays the depreciated sum minus the deductible. The holdback releases when you submit completion proof: contractor invoices, itemized receipts, photographs of finished work, and a signed statement of completion. Policies set a submission window for claiming it, and unclaimed holdbacks expire with that window.
Roof claims carry the largest holdbacks in practice because roof depreciation schedules run steep on older shingles. Contents claims run item-level holdbacks, each releasing against its own receipt, and discontinued items commonly settle at the closest comparable value instead of the original list price. This is the mechanics of actual cash value — the depreciated payment basis — operating inside a replacement-cost policy as an interim step. The first check is not the settlement; it is the claim's first act.
Three claim-side details decide whether the holdback actually releases. First, the contractor's bid must carry the full replacement figure — bids quoting only the depreciated amount leave the holdback unbilled, and the insurer pays what the invoice says. Second, the documentation standard is strict: cash payments without itemized receipts commonly stall release, so the invoice and the completion photos are the claim file's proof. Third, matching matters — where a matching endorsement applies, the added line items run through the same holdback math, and the receipts for the matched items release their share too. Confirming all three with the adjuster before work starts takes minutes and prevents the release fight afterwards.
Typical values
| Feature | Typical range |
|---|---|
| Holdback share of claim | Commonly 20–40% |
| Roof depreciation at 10 years | 30–50% of replacement cost, schedule-dependent |
| Release documentation | Invoices, receipts, completion photos |
| Submission window | Policy period or a stated number of days, extendable on request |
Depreciation holdback vs deductible
The holdback is recoverable with proof of replacement; the deductible is not. Both reduce the first payment, and only one returns. The distinction changes the claim decision: a policyholder weighing whether to complete repairs is weighing whether to recover the holdback — skipping repairs donates it to the insurer, while the deductible is lost in every scenario. Extended replacement cost and other valuation upgrades change the ceiling, not this two-stage mechanics.
Worked example
A hail claim prices a 10-year-old roof at $28,000 replacement cost. The roof schedule applies 40% depreciation, so the first check arrives at $16,800 minus the $1,000 deductible — $15,800. The replacement completes for the full figure, and the submitted invoices release the $11,200 holdback. The policyholder who treated the first check as the settlement and never submitted invoices donated $11,200 to the insurer; the invoice file was the entire difference.
Related guides
The holdback is the middle step between the two valuation standards — the replacement-cost promise and the ACV first payment.
- What Is Replacement Cost Coverage? — the pay-new standard that creates the holdback.
- What Is Actual Cash Value (ACV)? — the depreciated basis the first check pays.
- What Is Extended Replacement Cost? — the ceiling upgrade above the dwelling limit.
- Home Insurance Claims Guide — the claim sequence the holdback sits inside.
- ACV vs Replacement Cost — the valuation decision that decides whether a holdback exists.
Frequently asked questions
Do I get the depreciation holdback if I do the repairs myself?
Commonly yes — owner-performed work qualifies on most policies when you document costs with itemized receipts and photos of the finished work. Materials receipts are the core proof, and some carriers discount labor on owner-performed work. Confirm the proof requirements with the adjuster before starting, and keep every invoice.
Does a depreciation holdback apply to personal property claims?
Yes — on replacement-cost contents coverage, each item pays at depreciated value first and releases its own holdback against that item's replacement receipt. Unreplaced items forfeit their holdback, so a partially replaced inventory pays less than a fully documented one. Discontinued items commonly settle at the closest comparable value.
How is a depreciation holdback different from my deductible?
The holdback comes back; the deductible never does. Both reduce the first check, but the holdback is the recoverable portion of a replacement-cost claim — released when completion is proven — while the deductible is subtracted from every first-party claim and stays with you regardless of what you replace or repair.
Related guides
What Is Replacement Cost Coverage?
Replacement cost pays today's price to repair or replace damaged property with no depreciation subtracted; actual cash value subtracts depreciation.
Read guideWhat Is Actual Cash Value (ACV)?
Actual cash value (ACV) pays replacement cost minus depreciation — used value, not new. The cheaper premium option pays smaller claims on contents, roofs, and cars.
Read guideWhat Is Extended Replacement Cost?
Extended replacement cost pays a set percentage above your dwelling limit — commonly 25–50% — so a rebuild that outruns the policy still pays after a disaster.
Read guide
The Home Insurance Claim Process: From Damage to Settlement
How a homeowners claim actually works: mitigation, documentation before cleanup, the adjuster visit, the two-check payout, supplements, and common mistakes.
Read guide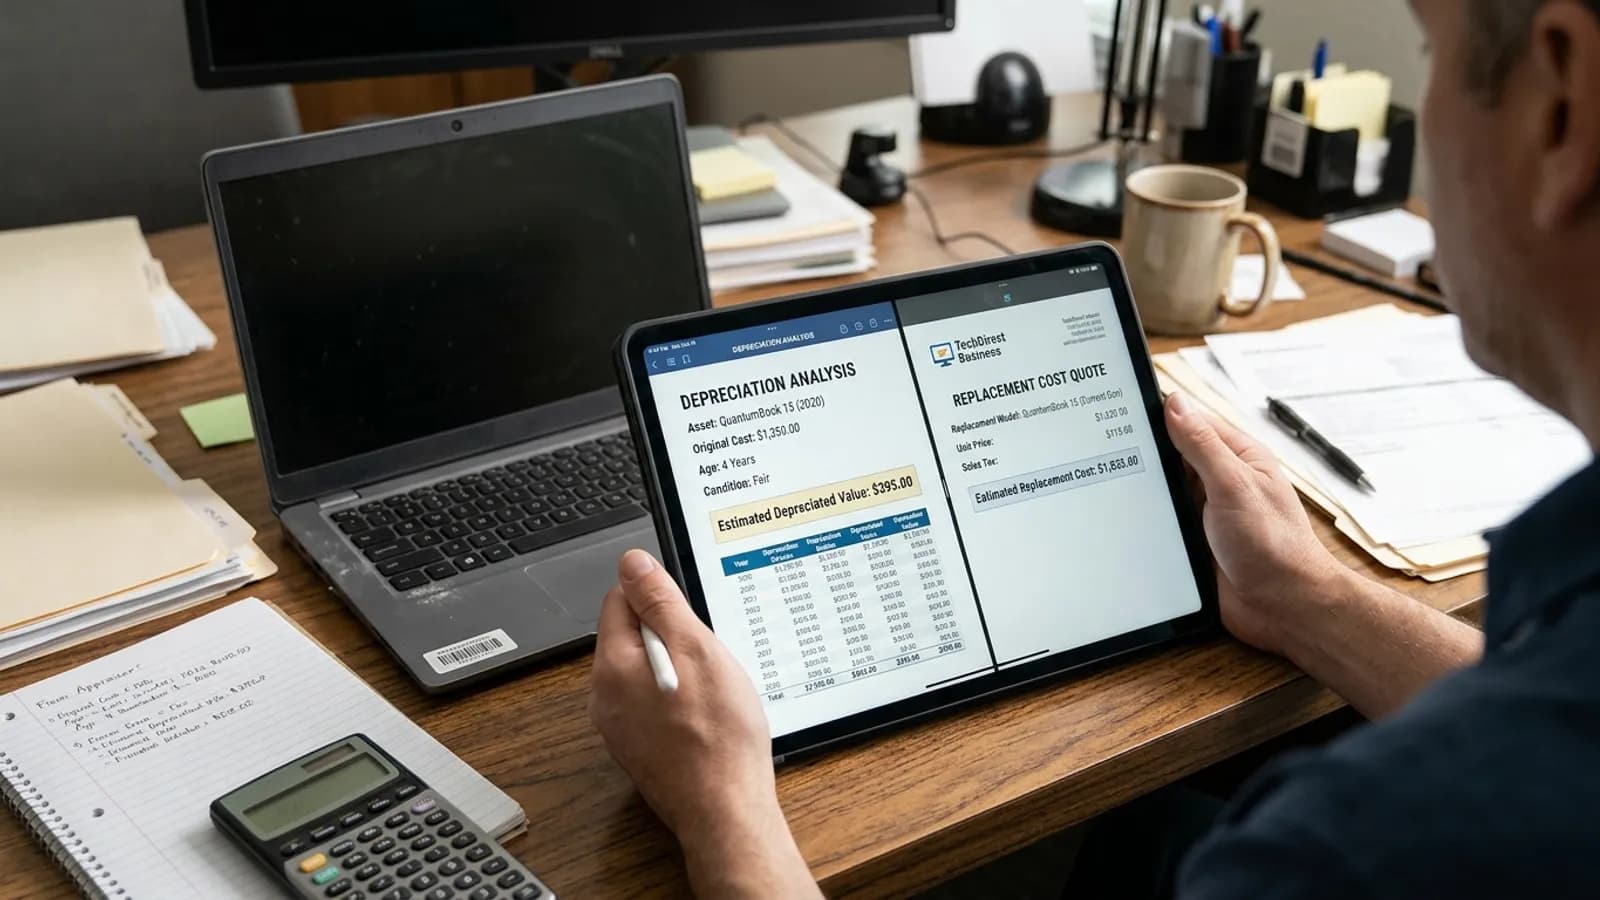
ACV vs Replacement Cost: The Claim-Payout Difference
Replacement cost pays today's price to rebuild; ACV pays that price minus depreciation. Learn which settlement basis your policy names before a claim arrives.
Read guide← Back to the full insurance glossary
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov Glossary — official ACA definitions for health-coverage terms.
- Insurance Information Institute (III) — property & casualty term definitions cross-checked against policy forms.
- NAIC consumer resources — regulator-authored guides and glossaries for each line of insurance.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.