
Glossary
What Is Replacement Cost Coverage?
Replacement cost (RCV) coverage pays today's price to repair or replace damaged property — no depreciation subtracted. Actual cash value (ACV), the alternative, pays replacement cost minus depreciation. The two words decide claim outcomes on roofs, contents, and everything else, which makes them the most consequential valuation terms on any property policy.
How it works
The valuation standard is stated per coverage on the declarations: dwelling coverage (Coverage A) sits at RCV on standard HO-3 forms, while contents (Coverage C) is ACV by default with the RCV endorsement as the paid upgrade. The contents claim pays in two steps: the adjuster's initial payment at ACV, then the depreciation holdback — the withheld difference — releases when you submit receipts showing the items were replaced, commonly within 180 days. Unreplaced items stay paid at ACV; the receipts, not the claim check, complete the coverage.
Roofs are the contested line. Carriers re-roof at age — commonly 15–20 years — moving roof claims from RCV to ACV or declining renewal, because roof claims are the largest and most frequency-prone home claims; the roof's condition report is the underwriting document that decides the treatment. The RCV family has tiers: full RCV, extended replacement cost with 25–50% cushions above the dwelling limit against construction inflation, and guaranteed-replacement forms. The ACV comparison runs on the same math in reverse — see the site's ACV vs replacement cost guide for the full premium-versus-payout trade.
Typical values
| Context | Typical value |
|---|---|
| Dwelling (Coverage A) | RCV standard on HO-3 forms |
| Contents (Coverage C) | ACV default; RCV endorsement upgrade |
| Contents RCV endorsement price | $50–$150 per year for ~$80,000 of contents |
| Roof RCV cutoff | Commonly 15–20 years of age |
| Extended RCV cushion | 125–150% of the dwelling limit |
| Holdback claim window | Commonly 180 days for replacement receipts |
Replacement cost vs actual cash value
Replacement cost pays the price of a new equivalent; actual cash value pays replacement cost minus depreciation — the garage-sale value. The delta concentrates in exactly the claims people file: a 6-year-old roof pays 40–60% of replacement at ACV, a 3-year-old laptop pays $450 instead of $1,200. RCV costs more in premium and pays multiples at claim time; the two-step holdback mechanic is its price at claim time — receipts required.
Worked example
A 10-year-old TV is destroyed in a kitchen fire. ACV pays $180 — the depreciated used value. RCV pays $650 — the price of the equivalent new TV. Across a whole household, the same logic spreads to a $15,000–$40,000 difference on contents claims. On the structure: a 14-year-old roof at ACV pays $4,200; at RCV it pays $14,800 — which is why carriers move roofs to ACV at age and why the roof-age line is the most-read item at renewal. The RCV premium trade ran a few dollars a month; the claim gap ran five figures.
Related guides
The valuation choice connects to the neighboring valuation forms and the claim workflow where it pays out.
- What Is Functional Replacement Cost? — the valuation that pays to replace with similar-function materials.
- What Is Scheduled Personal Property? — the route for the jewelry and antiques RCV contents does not cover.
- Home Insurance Claims Guide — the claim timeline where the two-step RCV payout plays out.
- Home Insurance: The Complete Guide — where valuation standards fit the full homeowners policy.
Sources
- Insurance Information Institute (III.org) — Homeowners coverage valuation options
- National Association of Insurance Commissioners (NAIC) — Homeowners insurance consumer guide
Frequently asked questions
How does a replacement-cost contents claim pay out?
In two steps: an initial payment at actual cash value (depreciated), then the depreciation holdback releases when you submit receipts showing the items were replaced — commonly within 180 days. Stopping at the first check leaves the holdback unpaid; the receipts are what trigger the full replacement-cost payment.
Why did my roof move to actual cash value?
Carriers re-roof at age — commonly 15–20 years — because roof claims are the largest and most frequency-prone home claims. The ACV switch means depreciation comes off every roof claim payout, and the premium savings are a fraction of the claim-time difference. A new roof resets the clock and often earns a premium credit.
Is replacement cost worth the extra premium?
At claim time, almost always. The depreciation gap runs from hundreds of dollars on a single item to tens of thousands across a household, while the contents RCV endorsement prices at roughly $50–$150 per year. Dwelling coverage is already replacement-cost on standard HO-3 forms, so the decision usually concentrates on contents and roof terms.
Does replacement cost cover antiques and jewelry?
No — appreciating and high-value items ride scheduled-property rules regardless of the RCV endorsement: fine art, antiques, and jewelry above sub-limits need individual scheduling with appraisals. The endorsement covers ordinary household goods, which is where its claim math does its work.
Related guides
What Is Actual Cash Value (ACV)?
Actual cash value (ACV) pays replacement cost minus depreciation — used value, not new. The cheaper premium option pays smaller claims on contents, roofs, and cars.
Read guideWhat Is a Depreciation Holdback?
A depreciation holdback is what a replacement-cost policy withholds at first payment — paying ACV now, releasing the rest once invoices prove the work is done.
Read guideWhat Is Extended Replacement Cost?
Extended replacement cost pays a set percentage above your dwelling limit — commonly 25–50% — so a rebuild that outruns the policy still pays after a disaster.
Read guideWhat Is Dwelling Coverage (Coverage A)?
Dwelling coverage (Coverage A) insures your home's structure at rebuild cost — not market value — and anchors the policy: other limits are percentages of it.
Read guide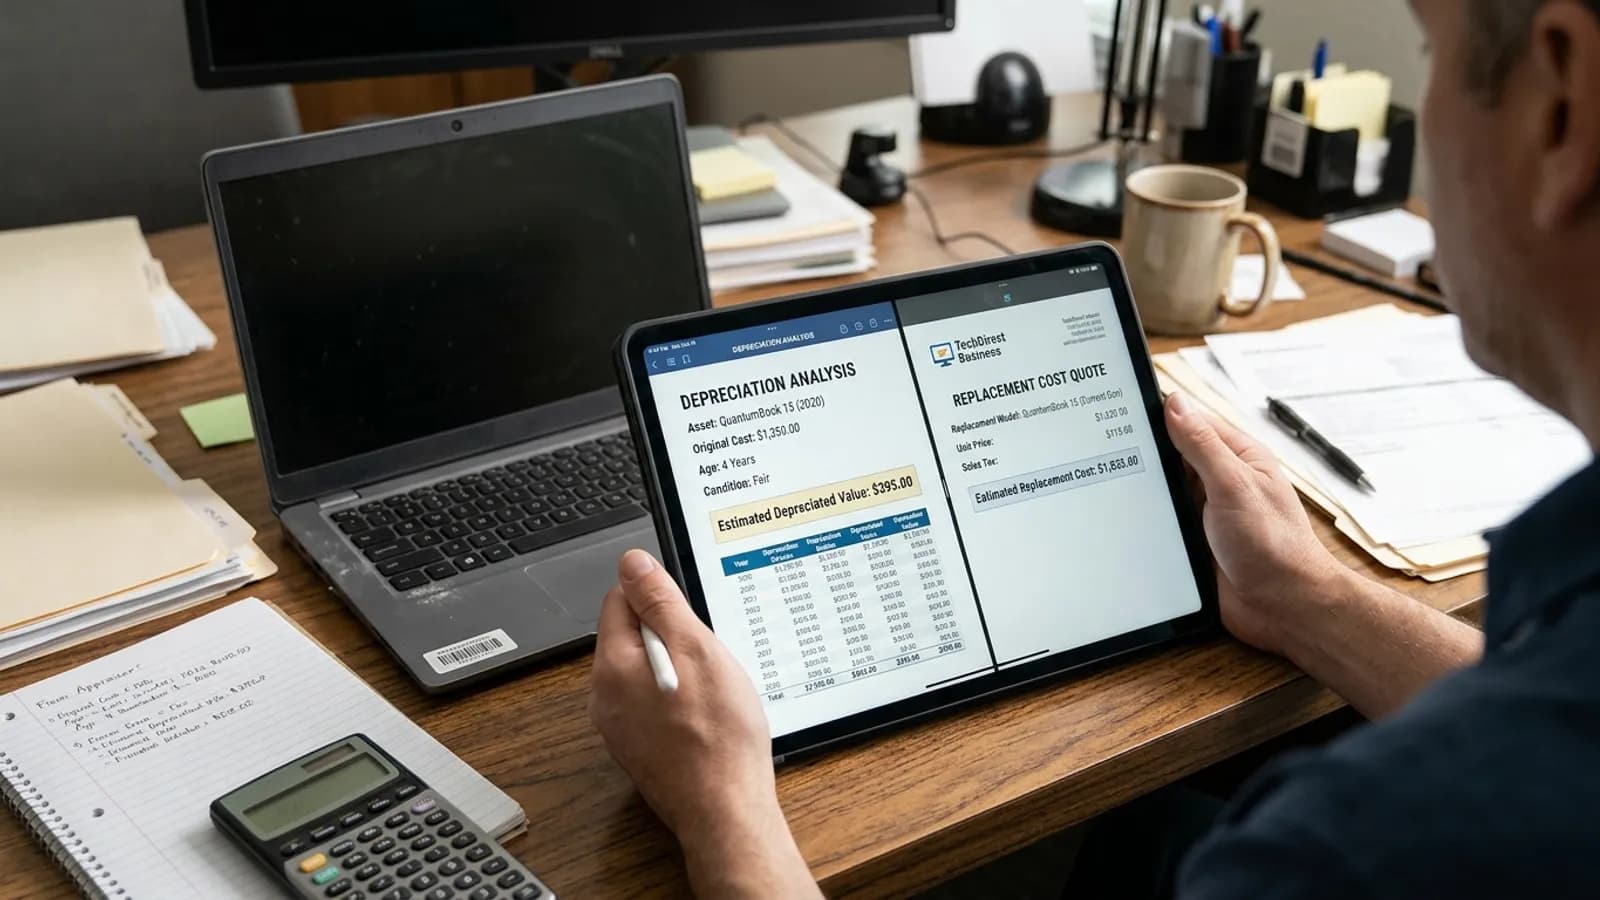
ACV vs Replacement Cost: The Claim-Payout Difference
Replacement cost pays today's price to rebuild; ACV pays that price minus depreciation. Learn which settlement basis your policy names before a claim arrives.
Read guide← Back to the full insurance glossary
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov Glossary — official ACA definitions for health-coverage terms.
- Insurance Information Institute (III) — property & casualty term definitions cross-checked against policy forms.
- NAIC consumer resources — regulator-authored guides and glossaries for each line of insurance.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.