
Glossary
What Is Actual Cash Value (ACV)?
Actual cash value (ACV) is the claim payout standard that pays an item's replacement cost minus depreciation — the used value of the damaged property at the time of loss, computed from age, life expectancy, and condition, not the cost to buy new.
How it works
The formula is replacement cost minus depreciation, and the depreciation schedule is the operative table: each carrier assigns property a useful life, then scales value down by age and condition. ACV appears in three places — contents coverage (by default on many policies), roof coverage (on older roofs or as a priced downgrade), and auto physical damage (ACV is the standard basis for total loss settlements).
Where a replacement-cost upgrade exists, the claim pays in two steps: the ACV check first, then the depreciation holdback released when you replace the item and submit receipts. Where no upgrade exists, the depreciated payment is final. The number is evidence-sensitive: purchase receipts reset the depreciation clock, and condition documentation argues the percentage line by line.
Typical values
| Example | ACV math |
|---|---|
| $1,000 TV, 5-year life, 3 years old | Roughly $400 |
| 14-year composite roof on a 25-year schedule | 44% of replacement — $6,600 on a $15,000 roof |
| Contents upgrade to replacement cost | Commonly $50–$150 more per year |
| Auto total loss | ACV is the standard settlement basis |
Actual cash value vs replacement cost
Replacement cost pays what it costs to buy the item new today; ACV pays what the used item was worth. The premium gap is small and the claim gap is large — the depreciation haircut concentrates in electronics, furniture, appliances, and roofs, the exact categories a household claims. The upgrade path runs through endorsements at renewal: replacement-cost contents riders, roof-surface certifications, or scheduled-property floaters for items that appreciate.
Worked example
A hail storm damages a 14-year-old composite-shingle roof on a 25-year life schedule. ACV pays 44% of replacement: $6,600 on a $15,000 roof, leaving $8,400 of the cost with the owner. The same roof on a replacement-cost policy pays the full $15,000 minus the deductible. In the same year, a kitchen fire destroys $30,000 of belongings; the ACV contents schedule pays $18,000 depreciated. The two upgrade decisions compounded across one house.
Related guides
ACV sits inside a valuation family — the replacement-cost standard, the holdback mechanics, and the extended forms that inflate the ceiling.
- What Is Replacement Cost Coverage? — the pay-new standard ACV discounts from.
- What Is a Depreciation Holdback? — the withheld amount released when you replace the item.
- What Is Extended Replacement Cost? — the percentage-over-limit upgrade for rebuilding cost overruns.
- ACV vs Replacement Cost — the claim-payout difference worked through real losses.
- Home Insurance: The Complete Guide — where the valuation choice sits in the full policy picture.
Sources
Frequently asked questions
How is actual cash value calculated?
Replacement cost minus depreciation, where depreciation follows the item's age and useful life on the carrier's schedule. A $1,000 television with a five-year life at three years of age computes to roughly $400. Purchase receipts and condition evidence move the calculation — the schedules are evidence-sensitive, not fixed.
Is ACV or replacement cost better for contents?
Replacement cost, at a premium difference commonly $50–$150 per year for a full household. The ACV haircut concentrates in the frequently-claimed categories — electronics, furniture, appliances — where depreciation runs fastest, which is exactly what a typical claim contains.
Related guides
What Is Replacement Cost Coverage?
Replacement cost pays today's price to repair or replace damaged property with no depreciation subtracted; actual cash value subtracts depreciation.
Read guideWhat Is a Depreciation Holdback?
A depreciation holdback is what a replacement-cost policy withholds at first payment — paying ACV now, releasing the rest once invoices prove the work is done.
Read guideWhat Is Extended Replacement Cost?
Extended replacement cost pays a set percentage above your dwelling limit — commonly 25–50% — so a rebuild that outruns the policy still pays after a disaster.
Read guideWhat Is a Total Loss?
A total loss is declared when repair costs plus salvage approach the car's actual cash value — thresholds run 70–100% — and the insurer pays ACV minus deductible.
Read guide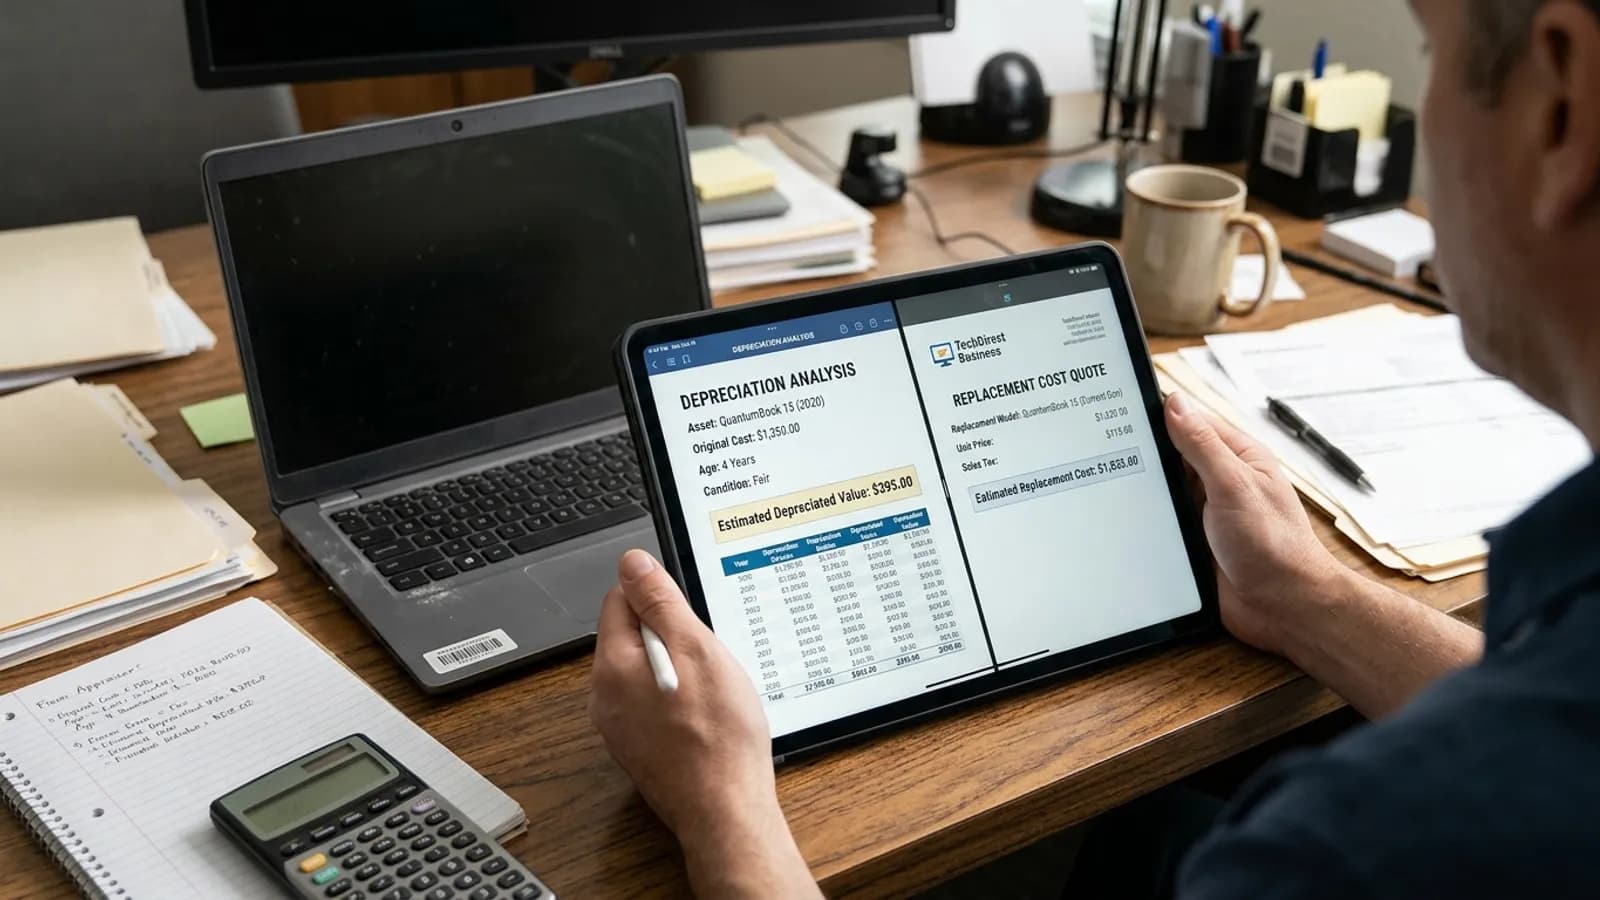
ACV vs Replacement Cost: The Claim-Payout Difference
Replacement cost pays today's price to rebuild; ACV pays that price minus depreciation. Learn which settlement basis your policy names before a claim arrives.
Read guide
Home Insurance: The Complete Guide
Homeowners insurance pays to rebuild, replace, and defend after fire, storms, and lawsuits — this guide maps coverage, exclusions, deductibles, and costs by state.
Read guide← Back to the full insurance glossary
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov Glossary — official ACA definitions for health-coverage terms.
- Insurance Information Institute (III) — property & casualty term definitions cross-checked against policy forms.
- NAIC consumer resources — regulator-authored guides and glossaries for each line of insurance.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.