
Homeowners Insurance in North Dakota: Costs and What to Know (2026)
Homeowners insurance in North Dakota costs $1,600–$2,500 per year, with a top-tier hail corridor, Red River flooding, and blizzard winters shaping the market.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.

On this page
Homeowners insurance in North Dakota costs $1,600–$2,500 per year for a standard HO-3 policy on a typical single-family home. A top-tier hail corridor, Red River spring flooding, and blizzard-grade winters set the state's claim pattern, and energy-boom construction adds rebuild-cost variance in the west.
What North Dakota homeowners pay
| Home profile / city | Typical annual cost |
|---|---|
| Statewide typical (standard HO-3) | $1,600–$2,500 |
| Fargo and the Red River Valley | Toward the upper half, hail-adjacent pricing |
| Grand Forks and Devils Lake | Near the range, flood-adjacent flood-policy stacking |
| Bismarck and central counties | Near the range |
| Williston and Bakken-area cities | Rebuild-cost variance from energy-boom housing |
| Home + auto bundle with one carrier | Usually trims 5–15% off both premiums |
City size moves North Dakota premiums less than hail history does. Rating territories track convective-storm loss activity, and a ZIP's recent hail seasons can outweigh every other pricing factor at renewal.
North Dakota's rules and regulators
The North Dakota Insurance Department licenses carriers, reviews rate filings, and operates the consumer complaint process at nd.gov/ndins/. No state statute requires homeowners insurance; the floor comes from mortgage lenders, who mandate replacement-cost dwelling coverage while the loan exists and force-place insurance at 5–10 times market price after a lapse. Percentage wind/hail deductibles, typically 1–2% of dwelling coverage, are common on North Dakota policies in the hail corridors, layered over the flat deductible for other perils. Escrowed premiums turn any renewal jump into a higher monthly mortgage payment without notice from the carrier.
The North Dakota claim landscape
- Hail across the central and eastern corridors — North Dakota sits in the same convective belt as South Dakota and Minnesota; summer hail outbreaks generate the state's biggest claim counts, and the percentage wind/hail deductible decides how much each storm costs the homeowner.
- Red River spring flooding — snowmelt plus spring rain floods the Fargo–Grand Forks valley in flat, meandering stages; the water is excluded from the HO-3, so valley homes stack an NFIP or private flood policy and lenders trigger the flood requirement in mapped zones.
- Blizzard winters — heavy snow loads, ice dams, and wind-driven cold snaps produce roof-stress and frozen-pipe claims; sudden damage pays, gradual seepage is denied as maintenance.
- Straight-line wind — prairie thunderstorms push downburst gusts across open terrain, peeling roofs and felling trees; wind claims share the wind/hail deductible where one applies.
- Devils Lake basin losses — a slowly rising closed-basin lake has consumed farmland and threatened homes around Devils Lake for decades, a slow-onset water problem the standard policy does not solve.
Coverage setup that fits North Dakota
- Dwelling at rebuild cost — keep Coverage A within 5% of a local builder's estimate; energy-boom-era construction inflated rebuild costs unevenly across the western counties.
- The hail deductible read — confirm both deductible types before binding; a percentage wind/hail deductible scales with dwelling value, not with the storm.
- Flood stacking in the valley — NFIP caps run $250,000 building and $100,000 contents with a 30-day wait and $30,000 of Increased Cost of Compliance; private flood covers higher-value valley homes.
- Water backup endorsement — excluded by default at roughly $50–$250 per year; sewer backup claims spike when valley flooding saturates storm drains.
- Roof valuation clarity — know whether the roof pays replacement cost or depreciated ACV; the math is in ACV vs replacement cost.
- Bundle discipline — a home-plus-auto bundle trims 5–15% off both premiums, meaningful on a hail-rated territory premium.
Hail first, flood second: the two-policy spring
North Dakota's loss season runs on two tracks that the same premium never covers. Hail arrives first — June outbreaks drop stones across the central and eastern corridors, and roof claims pay through the homeowners policy minus the wind/hail deductible. Then the Red River rises: snowmelt and spring rain fill a flat valley that floods from the bottom up, and that water is excluded from every standard policy. Work the same hail claim ($45,000 in roof and siding damage, $400,000 dwelling coverage) under the deductible structures North Dakota carriers use:
| Deductible option | Out of pocket | Claim payout |
|---|---|---|
| $1,000 flat | $1,000 | $44,000 |
| 1% ($4,000) | $4,000 | $41,000 |
| 2% ($8,000) | $8,000 | $37,000 |
The flood track has its own rules: NFIP coverage caps at $250,000 for the building and $100,000 for contents, activates after a 30-day wait, and adds $30,000 of Increased Cost of Compliance for elevation work. A North Dakota home that holds only the HO-3 has bought the hail half of the state's risk and carries the water half bare.
Related guides
North Dakota's hail and flood seasons each get a dedicated playbook, and the same convective belt runs through Minnesota and South Dakota.
- Home Insurance: The Complete Guide — the HO-3 structure and claim strategy behind every North Dakota policy.
- Does Homeowners Insurance Cover Hail Damage? — how hail claims pay and what deductibles change.
- Flood Insurance — the separate policy the Red River Valley depends on.
- Homeowners Insurance in Minnesota — $1,800–$2,800 per year across the eastern edge of the same hail belt.
- Homeowners Insurance in South Dakota — $1,600–$2,500 per year in the corridor to the south.
- Best Home Insurance Companies — comparing carriers on claims handling and financial strength.
More home insurance state guides
Every state sets its own minimums, rules, and market:
Sources
- North Dakota Insurance Department — North Dakota consumer resources and complaint process
- FloodSmart / NFIP — flood policy caps, waiting periods, and zone rules
- III — Homeowners and renters insurance facts
Frequently asked questions
How much is homeowners insurance in North Dakota?
Homeowners insurance in North Dakota costs roughly $1,600–$2,500 per year for a standard HO-3 policy on a typical single-family home. The Red River Valley (Fargo, Grand Forks) and the central hail corridors price toward the upper half, while western cities add rebuild-cost variance from energy-boom construction.
Is hail damage covered in North Dakota?
Yes — hail is a covered peril on a standard North Dakota HO-3 policy, and it drives the state's claim mix. The payment mechanics matter more than the coverage itself: many North Dakota policies carry a separate percentage wind/hail deductible, typically 1–2% of dwelling coverage, charged per storm event.
Does North Dakota require homeowners insurance?
No state law requires homeowners insurance in North Dakota. Mortgage lenders set the floor — full replacement-cost dwelling coverage while the loan exists — and mapped flood zones along the Red River add an NFIP or private flood policy. The North Dakota Insurance Department licenses carriers and handles complaints.
Is spring flooding covered on a North Dakota homeowners policy?
No. Snowmelt and Red River flooding are surface water, excluded from every standard policy. NFIP building coverage caps at $250,000 and contents at $100,000 with a 30-day waiting period, and Grand Forks (1997) and Fargo (2009) both demonstrated how fast valley flooding moves; private flood fills above the caps.
What deductible should a North Dakota homeowner carry?
A flat $1,000–$2,500 deductible covers most losses — water, fire, theft, liability. In the hail corridors many North Dakota carriers add a separate percentage wind/hail deductible; 2% on a $400,000 dwelling is $8,000 per storm. Both deductible types appear on the declarations page before you bind.
Why are roof claims in North Dakota so contested?
Hail frequency forces carriers to manage roof payouts. A policy with an actual-cash-value roof endorsement pays the depreciated value of a replacement — often $6,000–$8,000 on a $12,000 roof job for a 12-year-old shingle roof — while replacement-cost coverage pays the full job minus the deductible.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Home Insurance: The Complete Guide
Homeowners insurance pays to rebuild, replace, and defend after fire, storms, and lawsuits — this guide maps coverage, exclusions, deductibles, and costs by state.
Read guide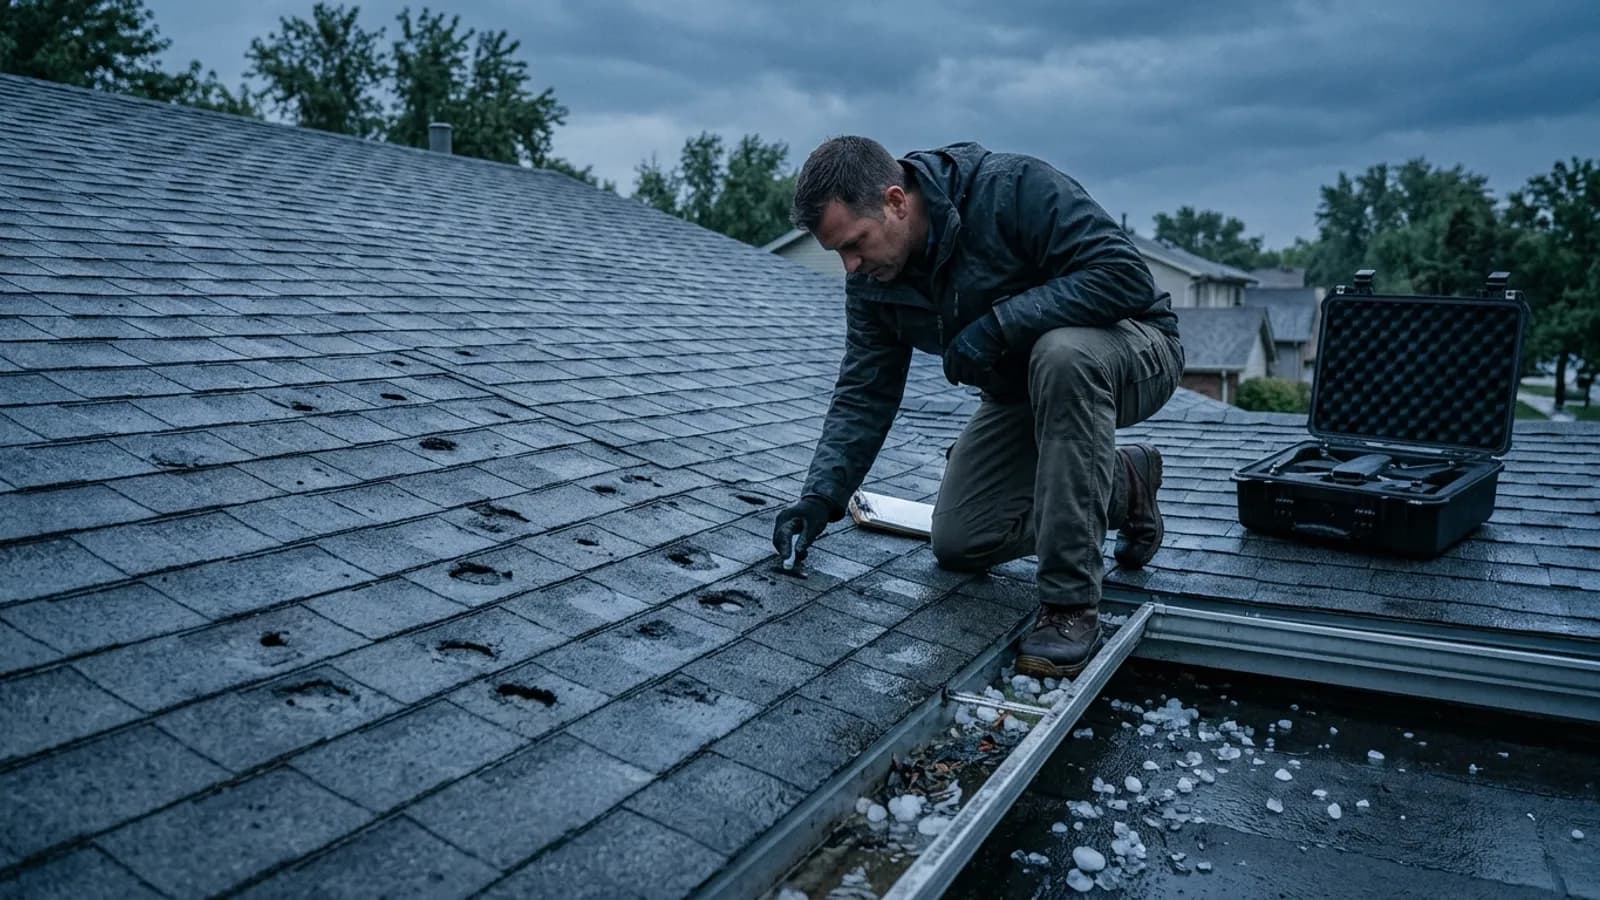
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance covers hail damage to roofs, siding, and contents, and hail-belt states price it with percentage wind/hail deductibles and ACV roof schedules.
Read guide
Flood Insurance: What It Covers, What It Costs, and Who Needs It
Flood insurance is never part of a standard home policy. Costs per year, the 30-day waiting period, NFIP limits, and why most claims come from outside flood zones.
Read guideHomeowners Insurance in Minnesota: Costs and What to Know (2026)
Homeowners insurance in Minnesota costs $1,800–$2,800 per year, with hail, tornadoes, and ice-dam winters shaping what homeowners in each ZIP code pay.
Read guideHomeowners Insurance in South Dakota: Costs and What to Know (2026)
Homeowners insurance in South Dakota costs $1,600–$2,500 per year, with top-ranked hail losses, prairie tornadoes, and blizzard winters shaping what each ZIP pays.
Read guide
How to Choose the Best Home Insurance Company (No Sponsored Rankings)
Choose a home insurer on claims satisfaction, financial strength, coverage breadth, and state-market position — the criteria that replace sponsored rankings.
Read guide