
Glossary
What Is a Wind/Hail Deductible?
A wind/hail deductible is a separate deductible applying only to windstorm and hail claims — usually a percentage of dwelling coverage (1–5%) rather than a flat dollar amount — standard in hurricane-exposed and hail-belt states, where a 2% deductible on a $400,000 home means $8,000 out of pocket before coverage pays.
How it works
The declarations page lists two deductibles, and the split is the policy's real cost-sharing story: the flat all-perils deductible (commonly $1,000–$2,500) handles fire, theft, and water claims, while the wind/hail percentage applies only to storm claims. The percentage multiplies dwelling coverage (Coverage A) — 1% of a $400,000 dwelling is $4,000; 2% is $8,000 — so the owner's storm share grows with the house. A rarer and harsher variant computes the percentage of the loss rather than of coverage.
Geography decides its presence: Gulf Coast, Atlantic coastal, and Plains hail-belt carriers apply it broadly, and some states regulate the disclosure or cap the percentage. Some coastal markets split it further into a hurricane-specific deductible for named storms, alongside a separate wind/hail line for ordinary storms. The claim mechanics compound with roof valuation: on an actual-cash-value roof policy, the depreciated roof payout minus the percentage deductible is the modern hail claim's arithmetic — which is why small hail claims often pay nothing and get pushed toward total roof-loss thresholds. Mitigation credits — impact-resistant roofing, opening protection — cut the premium, but the deductible stands; carriers in hard markets have pushed standard deductibles to 2% and even 3%, and the buy-down that moves 3% back to 1–2% is the household's main lever, priced into a higher premium.
Typical values
| Structure | Typical value |
|---|---|
| Percentage range | 1–5% of dwelling coverage |
| 2% on a $400,000 dwelling | $8,000 |
| All-other-perils deductible | $1,000–$2,500 flat |
| Buy-down economics | 1%→2% move commonly saves 10–20% of the wind premium |
| Hail-belt standard | 2% and moving to 3% in some markets |
Wind/hail deductible vs all-peril deductible
The all-peril deductible is flat and applies everywhere the percentage does not; the wind/hail deductible is percentage-based and storm-specific. The two interact at claim time: a $22,000 hail loss on a $400,000 dwelling with a 2% wind/hail deductible and a $1,000 all-peril deductible pays $14,000 — the storm line costs the owner $8,000 where the flat line would have cost $1,000. Carriers trade the deductible for premium, so the choice is a self-insurance election: the 1–2% range is the rational belt for most households, and the hail peril is the one that decides whether the election pays.
Worked example
A $400,000 home in a hail state carries a 2% wind/hail deductible ($8,000) and a $1,000 all-peril deductible. A hailstorm does $22,000 of roof damage: the claim pays $14,000, and the owner funds $8,000. The same damage on the same house in a flat-deductible market would have cost $1,000 out of pocket — the geography moved the deductible by $7,000. A smaller $6,000 hail claim against the same $8,000 deductible pays nothing and still posts to the claims record, which is why sub-deductible damage is usually repaired out of pocket.
Related guides
The percentage deductible connects to the dwelling basis it computes from and the storm perils it prices.
- What Is Hazard Insurance? — the storm-peril shorthand the deductible attaches to.
- What Is an Act of God in Insurance? — why storms stay covered while the cost-sharing shifts.
- What Is an Exclusion in Insurance? — the roof-surface and wear exclusions that pair with the deductible.
- Does Homeowners Insurance Cover Hail Damage? — the claim picture in hail-belt states.
- Home Insurance: The Complete Guide — where the deductible split sits in the full policy picture.
Sources
Frequently asked questions
How is a percentage wind/hail deductible calculated?
As a percentage of your dwelling coverage, not of the claim: 2% on a $400,000 dwelling limit is an $8,000 deductible on any wind or hail claim. The all-other-perils deductible (commonly $1,000–$2,500 flat) applies to every other peril. Both numbers appear on the declarations page.
Why do hail states have separate wind deductibles?
Because windstorm and hail are the most frequent and most expensive home claims in those regions — carriers separate the exposure to price it honestly and share more cost with owners. The percentage structure scales the owner's share with dwelling value, which is why the deductible grows with the house.
Can I lower my wind/hail deductible?
Through deductible buy-downs (a higher premium for a lower percentage, commonly 1–2% instead of 2–3%), mitigation credits for impact-resistant roofing and opening protection, and carrier shopping. Geography limits the range — in hail-belt and coastal markets, some percentage structure is usually unavoidable.
Related guides
What Is a Deductible? (Insurance, Explained)
A deductible is what you pay out of pocket for covered losses before insurance pays — health resets it yearly; auto and home apply it per claim.
Read guideWhat Is Dwelling Coverage (Coverage A)?
Dwelling coverage (Coverage A) insures your home's structure at rebuild cost — not market value — and anchors the policy: other limits are percentages of it.
Read guideWhat Is Actual Cash Value (ACV)?
Actual cash value (ACV) pays replacement cost minus depreciation — used value, not new. The cheaper premium option pays smaller claims on contents, roofs, and cars.
Read guideWhat Is a Peril?
A peril is the specific cause of loss a policy insures against — fire, windstorm, hail, theft — the list that separates named-peril from open-peril forms.
Read guide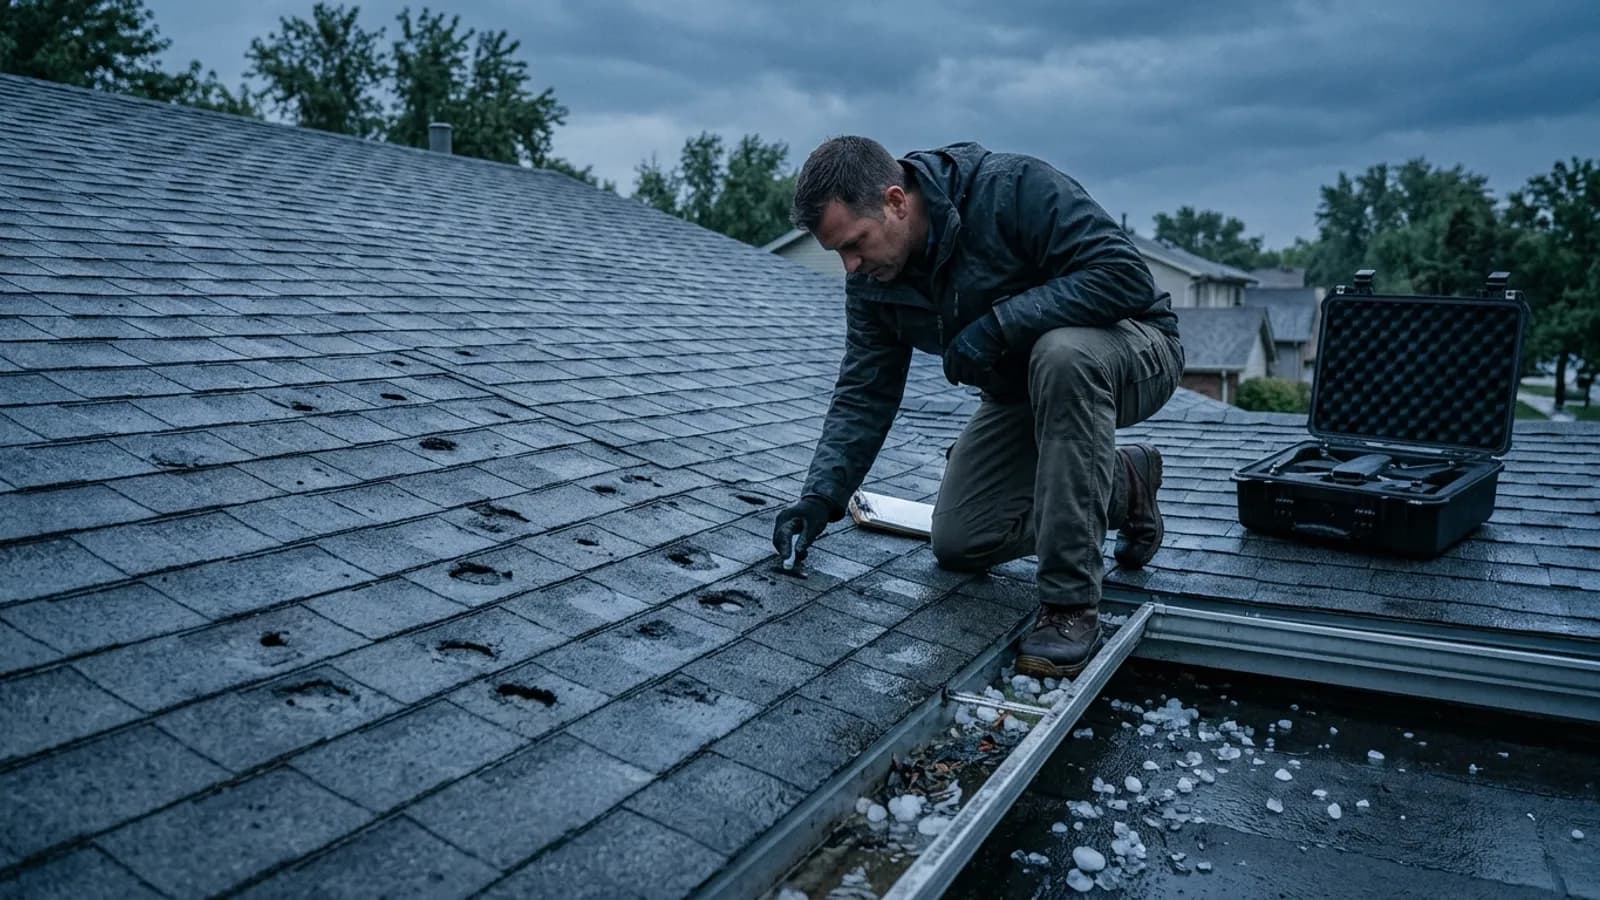
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance covers hail damage to roofs, siding, and contents, and hail-belt states price it with percentage wind/hail deductibles and ACV roof schedules.
Read guide← Back to the full insurance glossary
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov Glossary — official ACA definitions for health-coverage terms.
- Insurance Information Institute (III) — property & casualty term definitions cross-checked against policy forms.
- NAIC consumer resources — regulator-authored guides and glossaries for each line of insurance.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.