
Home Insurance in Fort Worth, TX: Costs and Guide (2026)
Home insurance in Fort Worth costs about $2,600–$4,200 per year. Hail-alley roof claims, wind/hail deductibles, and the claims discipline that keeps premiums down.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.

On this page
Home insurance in Fort Worth runs about $2,600–$4,200 per year for a standard HO-3 policy on a median-priced home. The city shares the DFW hail corridor's dynamics, and roof replacement is the premium lever that defines a Fort Worth policy. The roof documentation file — installation date, material class, inspection reports — is the most valuable paper a Fort Worth owner keeps. Statewide context sits in the Texas guide linked below.
What Fort Worth homeowners pay
| Profile in Fort Worth | Typical annual premium |
|---|---|
| Texas statewide median | $2,400–$4,200 |
| Median Fort Worth home, updated roof, $1,000 deductible | $2,600–$4,200 |
| Older roof (15+ years) | +15–40%, or an actual-cash-value roof settlement |
| Homes with recent hail claims on the address | quotes above the range; CLUE history prices in |
| New construction in growing subdivisions | −10–20% vs the Fort Worth median |
Fort Worth prices at the same top tier as Dallas — the hail corridor does not stop at the county line. The difference shows up in claim behavior: Tarrant County hail years can produce multiple claims on the same policy, which is where claims discipline earns its keep. The same roof that earns the discount today is the one the adjuster documents tomorrow — the file serves both.
Why Fort Worth prices the way it does
Hail geography is the base rate: storm tracks crossing Tarrant County have produced hail years with multiple claim waves, and carriers price that history into every Fort Worth roof. Tarrant County hail seasons have produced multiple claim waves in single years, and the territory rating carries that history forward. Roof replacement is the lever both ways — an impact-resistant or recently replaced roof pulls the premium down, while a 20-year roof draws actual-cash-value treatment or a decline. Growth in Tarrant County keeps construction costs climbing, so dwelling estimates go stale faster than renewals cycle. Trinity River geography adds a modest flood question on the low-lying blocks, but hail remains the peril that prices the policy. Claims density across the metro's compact residential corridors compounds the territory rating. DFW's deep competition keeps quotes comparable, but one hard hail spring reprices the whole territory.
Requirements and insurer norms in Fort Worth
Texas does not mandate homeowners insurance; mortgage lenders do, and replacement-cost claims require insuring at least 80% of the home's replacement value. The declarations page carries two deductible lines — flat for fire and water, percentage for wind/hail — and Fort Worth carriers commonly set the wind/hail percentage at 1–2% of dwelling coverage. Roof condition drives underwriting, with inspection requests common on older composition roofs. The Texas Department of Insurance publishes consumer rate comparisons and runs the complaint process for stalled claims. Impact-resistant shingle class (UL 2218) appears on Tarrant County applications for good reason: the credit prices in and the claims never start.
The Fort Worth claim pattern
- Hail waves — multi-claim seasons are the Fort Worth norm; the percentage deductible applies per claim, so a two-storm spring means two deductibles (wind/hail deductible mechanics).
- Claims discipline — contractor quotes before filing separate the roof damage worth claiming from the damage that costs more in renewal pricing than it pays; the May 1995 Mayfest hailstorm remains the corridor's reference event for what a single afternoon can do.
- Tornado-edge wind — wind events settle under the flat deductible, unlike hail; both are covered perils.
- Slab leaks on clay soil — North Texas clay movement cracks slab plumbing; resulting water damage is covered, foundation damage itself is excluded (foundation repair and coverage).
- Winter freeze bursts — the February 2021 freeze set the documentation standard: heat-on records decide disputed pipe claims.
Coverage setup that fits Fort Worth
- Dwelling at rebuild cost, with a buffer — add extended replacement cost so Tarrant County construction inflation does not strand the claim (extended replacement cost explained).
- Replacement-cost roof while offered — in the hail alley this is the most valuable single treatment on the policy (ACV vs replacement cost).
- Wind/hail deductible sized consciously — 1–2% of dwelling coverage is the common range; the number has to be fundable mid-claim.
- Water-backup endorsement at $50–$250 per year — the cheap answer to storm-water backflow.
- Ordinance-or-law coverage — post-loss rebuilds must meet current code, and Fort Worth's fast-building history hides that gap (ordinance-or-law coverage).
- Annual re-quote — hail years reprice Tarrant County territory-wide; add the comparison to the renewal calendar.
Related guides
Fort Worth shares the DFW hail-belt playbook with Dallas — roof documentation, deductible awareness, and quotes before claims — and these guides supply the mechanics.
- Homeowners Insurance in Texas — statewide pricing, TWIA notes, and the state claim path.
- Home Insurance: The Complete Guide — the HO-3 structure and exclusions behind every figure on this page.
- Does Homeowners Insurance Cover Hail Damage? — how hail claims settle and where percentage deductibles bite.
- Home Insurance in Dallas, TX — $2,600–$4,200 per year, the same corridor from the east side.
- What Is a CLUE Report? — the claims history that follows a Fort Worth address to its next buyer.
More home insurance guides for Texas
The state guide carries the minimums and the statewide rate band; the nearby metros carry their own:
Sources
- Texas Department of Insurance — consumer rate comparisons and complaint process
- III — Homeowners and renters insurance facts
Frequently asked questions
How much is home insurance in Fort Worth?
Fort Worth home insurance runs about $2,600–$4,200 per year for a standard HO-3 policy on a median-priced home — hail-alley pricing inside the DFW corridor. Roof age, the wind/hail deductible percentage, and the address's hail-claim history are the three lines that move an individual quote.
What deductible should a Fort Worth homeowner carry?
Expect two deductible lines: a flat $1,000–$2,500 for fire and water claims and a separate percentage wind/hail deductible — commonly 1–2% of dwelling coverage — applied per hail claim. On a $400k dwelling, 2% is $8,000; size the flat deductible for 10–25% savings and the percentage one for fundability.
Can one hail season push my Fort Worth premium through two deductibles?
Yes — the percentage wind/hail deductible applies per claim, not per year, so two hail events in one season mean two deductibles before coverage starts. That is why Fort Worth claims discipline matters double here: contractor quotes before filing keep small roof damage off the claims record.
How much dwelling coverage does a Fort Worth home need?
Insure the rebuild cost, not the purchase price — replacement-cost claims require at least 80% of the home's replacement value. Growth in Tarrant County keeps pushing construction costs up, so re-check the dwelling figure annually rather than trusting the original estimate.
What does the water-backup endorsement cost in Fort Worth?
A water-backup endorsement runs roughly $50–$250 per year and covers sewer or drain water that backs up into the home during storms — damage the base HO-3 excludes. Hail is Fort Worth's headline peril, but the sudden-storm water losses that follow are the rider's job.
Will a prior hail claim raise my premium when I buy a Fort Worth house?
Yes — the CLUE report follows the address, so prior roof claims price into the next buyer's quote. Pull the CLUE report before closing; a home with recent hail claims can quote above the city range or draw roof-age conditions at underwriting.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Homeowners Insurance in Texas: Costs and What to Know (2026)
Homeowners insurance in Texas costs $2,400–$4,200 per year, with billion-dollar hail outbreaks, Gulf hurricanes, and volatile carrier exits shaping the market.
Read guideHome Insurance: The Complete Guide
Homeowners insurance pays to rebuild, replace, and defend after fire, storms, and lawsuits — this guide maps coverage, exclusions, deductibles, and costs by state.
Read guide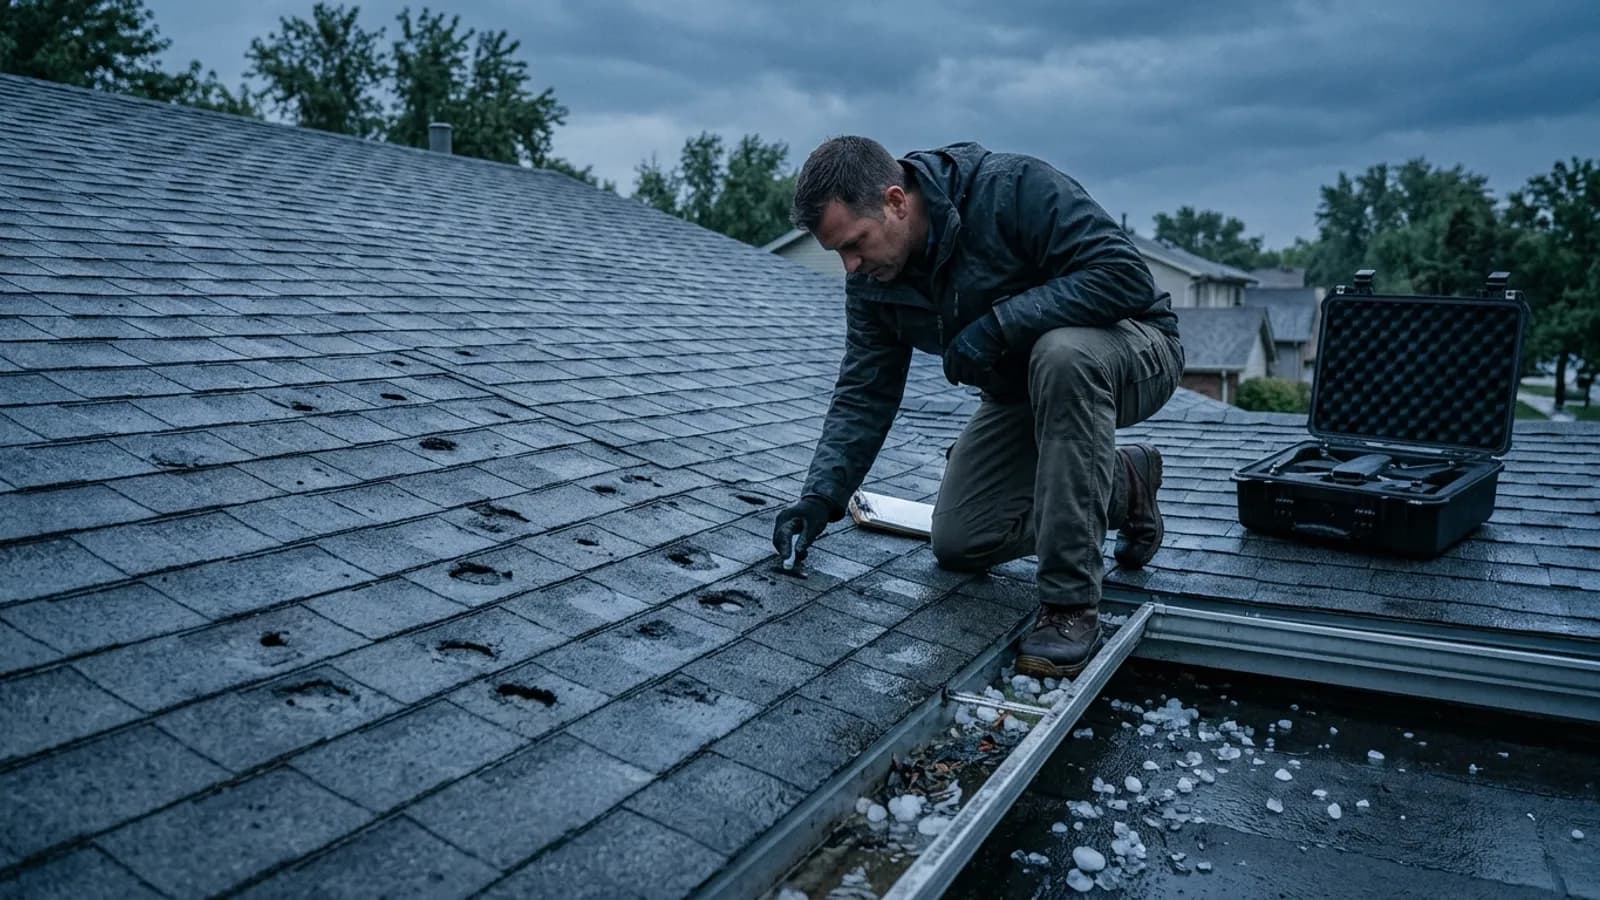
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance covers hail damage to roofs, siding, and contents, and hail-belt states price it with percentage wind/hail deductibles and ACV roof schedules.
Read guideHome Insurance in Dallas, TX: Costs and Guide (2026)
Home insurance in Dallas costs about $2,600–$4,200 per year. Top-tier DFW hail pricing, percentage wind/hail deductibles, and roof-age scrutiny at every renewal.
Read guideWhat Is a CLUE Report?
A CLUE report is your seven-year property and auto claims history from LexisNexis — every filed claim follows you and your home. Request the free annual copy.
Read guide