
Classic Car Insurance: Agreed Value, Restrictions, and Costs
Classic car insurance covers collector vehicles at agreed value instead of depreciated book — commonly $100–$600 per year, with mileage caps and no commuting.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
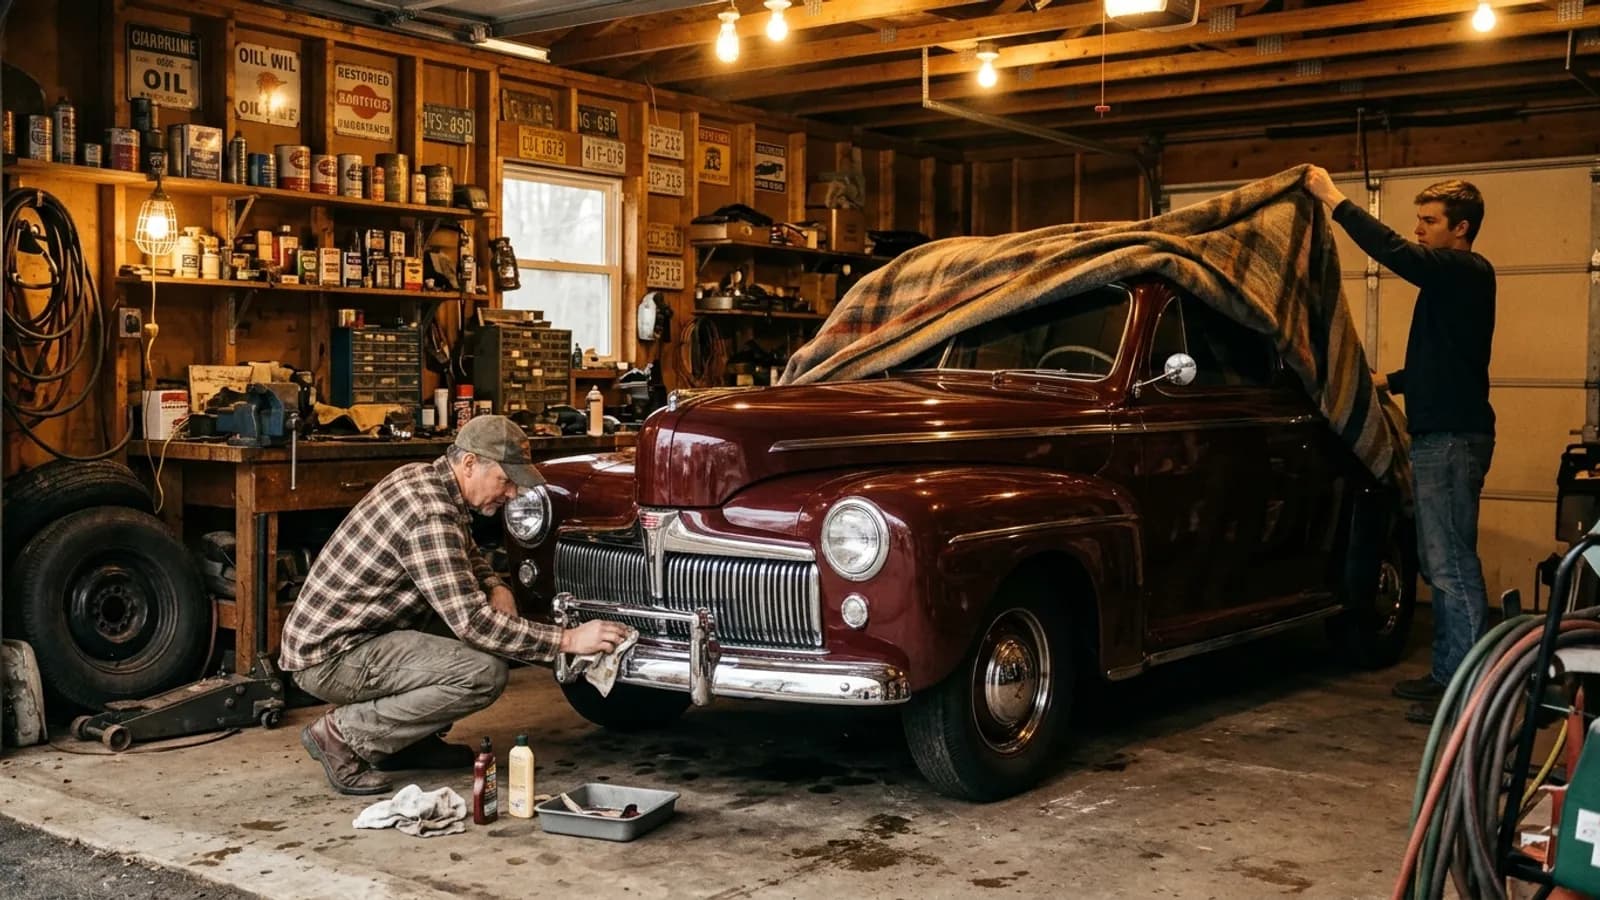
Classic car insurance insures your collector vehicle at an agreed value — a number set by appraisal, not depreciation — for a fraction of standard auto premiums, in exchange for usage limits. The model inverts normal auto insurance: the car appreciates, the driver rarely drives, and the policy prices both facts.
Agreed value vs actual cash value
| | Standard auto policy | Classic car policy | | | --- | --- | | Total-loss payout | Actual cash value (depreciated book) — you negotiate downward | Agreed value — the number on the policy, no depreciation | | Premium basis | Car's market value + your risk profile | Agreed value + limited usage | | Typical cost for a $40,000 collector | Standard rates on book value | $100–$600 per year | | After a total loss | Argue about comps | Paid the agreed number |
The agreed value is set at policy start (documentation: appraisals, photos, comparable sales) and updated at renewal as the market moves — the policy appreciates with the car. The actual cash value payout a standard policy produces is the contrast, and stated amount coverage is the halfway form some carriers sell.
What qualifies — and what the insurer expects from you
Vehicle eligibility: generally 20–25+ years old (antique/collector classes), select modern exotics, hot rods, restomods, and kits — programs vary.
Owner expectations (these make the cheap premium possible):
- A regular-use car for daily driving exists in the household
- Secure storage — locked garage (carports and street parking often disqualify)
- Clean-ish driving record
- Usage within policy rules — pleasure drives, shows, club events, parades, maintenance runs; no commuting
- Mileage caps — commonly 1,000–5,000 miles per year on standard programs; high-mileage programs exist
What it costs
| Vehicle | Agreed value | Typical annual premium |
|---|---|---|
| Driver-quality classic (mustang-era muscle) | $25,000–$40,000 | $100–$300 per year |
| Restored collector | $40,000–$75,000 | $150–$450 per year |
| Exotic / high-value | $75,000–$250,000+ | $300–$1,000+ per year |
Pricing scales with agreed value more than with horsepower — the inverse of regular auto insurance, where a supercar's premium dwarfs a sedan's.
The coverage details that matter
- Spare parts and tools coverage — often included or addable; restoration stashes are real money
- Inflation guard — automatic agreed-value increases at renewal (verify; update after major work)
- Roadside assistance — flatbed/tow-specific programs (not hook-and-drag)
- Deductibles — small ($0–$500); the usage limits are the real cost control
How to buy
- Inventory the car: photos, appraisal or market comps, restoration records.
- Confirm your household has a regular-use vehicle and secure storage.
- Get quotes from the collector-car specialists and compare agreed-value mechanics, mileage caps, and event usage terms.
- Revisit the agreed value annually — restorations and market moves should be reflected at renewal, not after a loss.
Setting an agreed value without underinsuring the car
The agreed value is the whole product — the number on the policy is what a total loss pays, no depreciation, no negotiation — and setting it is the owner's job with the insurer's sign-off. The working method: gather the restoration receipts, photos, and two or three comparable auction or classified results for the same year and condition, then propose the figure. The mistakes run both directions: under-agreeing to hold the premium down (a $38,000-restored Mustang agreed at $30,000 forfeits $8,000 at claim time) and over-agreeing without documentation (insurers push back or require a formal appraisal above their comfort threshold, commonly $50,000–$100,000 depending on the program). The number is revisited at every renewal — restorations, market moves, and major mechanical work all justify re-agreement, and most programs add automatic inflation guards that still need a human check after real work. The payout contrast with a standard policy's depreciated settlement is the mechanics in the collision guide — agreed value removes that argument entirely.
The usage rules that decide collector claims
Collector premiums are cheap because the exposure is tiny — and the usage clauses enforce it. The absolute line: no commuting, ever; driving the classic to work under a collector policy can void the claim, because the price was built for a Sunday drive, not a rush hour. Around that line sit the defined uses: pleasure driving, club events, shows, parades, and maintenance runs — most programs treat a drive to the shop as covered but want no ambiguity about a "shortcut to the office." Mileage caps commonly run 1,000–5,000 miles a year on standard programs, with high-mileage programs trading a higher premium for a bigger allowance; log the odometer, because the reading at claim time is checked against the cap. Track days are excluded by default everywhere. The household's regular-use car and locked-garage storage are standing conditions, not suggestions — the policy is priced on both, and the aftermarket parts rules apply to any modernized drivetrain or wheels on the car.
Insuring a car mid-restoration
The project car is its own coverage problem, and it changes three times. During the build: a standard auto policy on a non-running car in a garage is the wrong tool — specialist programs offer in-build or garage-only coverage that prices the car's parts and assembly value while it cannot be driven, and a parts stash (often five figures on a full restoration) needs scheduling as its own property line. The transition day: when the car first rolls, it moves onto the collector policy with its agreed value set from the build documentation — photograph everything before the first drive, because the documentation is the claim file. The tow-home moment: damage on a tow home from a seller claims differently depending on who owns the car and whose policy the car rides under, which is worth confirming before the trailer is hooked. Restomods and modified builds should read the aftermarket coverage rules as well — declared modifications are the collector version of the custom-parts question.
Related guides
Collector coverage borrows from and contrasts with the standard auto coverages — these pages carry both sides.
- Motorcycle Insurance: Coverage, Costs, and How to Save — the bike coverage stack, costs by bike type, and rider-specific details.
- What Does Full Coverage Car Insurance Cover? — what the liability-plus-comp-plus-collision package includes, excludes, and costs.
- How to Choose the Best Car Insurance Company — the no-sponsored-rankings criteria for evaluating any carrier.
- Car Insurance: The Complete Guide — the coverage structures, state rules, and savings levers every other page builds on.
Sources
Frequently asked questions
What is classic car insurance?
Specialty coverage for collector, antique, and modified vehicles that insures the car at an agreed value — a number you and the insurer set from appraisals and market data — instead of depreciating actual cash value. Premiums run a fraction of standard auto policies because usage is limited (pleasure driving, shows, club events — not commuting).
What qualifies as a classic car for insurance?
Typically vehicles 20–25+ years old, plus select modern exotics and modified builds. Insurers also underwrite the owner: most require a clean-ish record, a secure garage, and that you own a regular-use car for daily driving.
How much does classic car insurance cost?
Commonly $100–$600 per year for typical collector vehicles at agreed values of $25,000–$75,000 — often 50–80% less than insuring the same car on a standard policy at book value. Pricing follows the agreed value, mileage limits, storage, and your record rather than the car's age.
Can I drive a classic car with collector insurance?
Yes — within the policy's usage rules: pleasure driving, shows, club events, and maintenance trips, while excluding commuting and regular-use driving. Mileage caps (commonly 1,000–5,000 miles per year) apply on many policies; higher-mileage programs exist at higher premiums.
Does classic car insurance cover spare parts and tools?
Most collector programs include some spare-parts and tools coverage and offer higher limits by endorsement — worth doing, because a restoration parts stash commonly runs into five figures. Inventory the parts with photos and values; the unscheduled stash is the underinsured one.
What happens if I exceed my classic car's mileage cap?
Depends on the program: some reconcile pro-rated at renewal with a small additional premium, others treat cap-overrun claims as exposure they never priced and contest them. Log odometer readings, and if the driving pattern is growing, move to a high-mileage program at renewal rather than after a claim.
How we researched this guide
Car insurance pricing is set per driver, per ZIP code — so our guides anchor on regulator and industry statistics and explain the factors, not a fake exact price.
- Premium ranges are anchored to NAIC statewide average-expenditure data, the most complete public dataset on what drivers actually pay per state.
- State minimum-coverage requirements are checked against each state's motor-vehicle financial-responsibility statute and the state insurance department's consumer pages.
- What a coverage actually pays for is verified against policy declarations and specimen forms, not marketing copy.
- Discount and surcharge rules cite the state DOI consumer bulletin where each state regulates them differently — for example credit-based insurance scores, which most states permit but a few ban.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- IIHS — Insurance Institute for Highway Safety — crash-test data, vehicle loss statistics, and safety-feature research.
- NHTSA — National Highway Traffic Safety Administration — recalls, crash data, and state traffic-safety requirements.
- FMCSA — Federal Motor Carrier Safety Administration — commercial vehicle and carrier insurance requirements.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Motorcycle Insurance: Coverage, Costs, and How to Save
Motorcycle insurance runs $200–$500 per year for liability-only and $500–$1,500 full coverage — the coverage stack, rider-specific details, and savings levers.
Read guide
What Does Full Coverage Car Insurance Cover?
Full coverage car insurance is liability plus comprehensive and collision — what each part pays, what it excludes, what it costs, and when liability-only wins.
Read guide
How to Choose the Best Car Insurance Company (No Sponsored Rankings)
How to evaluate car insurance companies on claims service, financial strength, rate stability, and discount fit — the evaluation method with no sponsored rankings.
Read guide
Car Insurance: The Complete Guide
Car insurance bundles liability, collision, comprehensive, and medical coverage — this guide explains state minimums, full coverage, and how to lower the premium.
Read guide