
Renters Insurance in Jacksonville, FL: Costs and Guide (2026)
Renters insurance in Jacksonville costs about $15–$23 per month. Beaches ZIP wind pricing, St. Johns flooding, and hurricane legacy shape the price.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
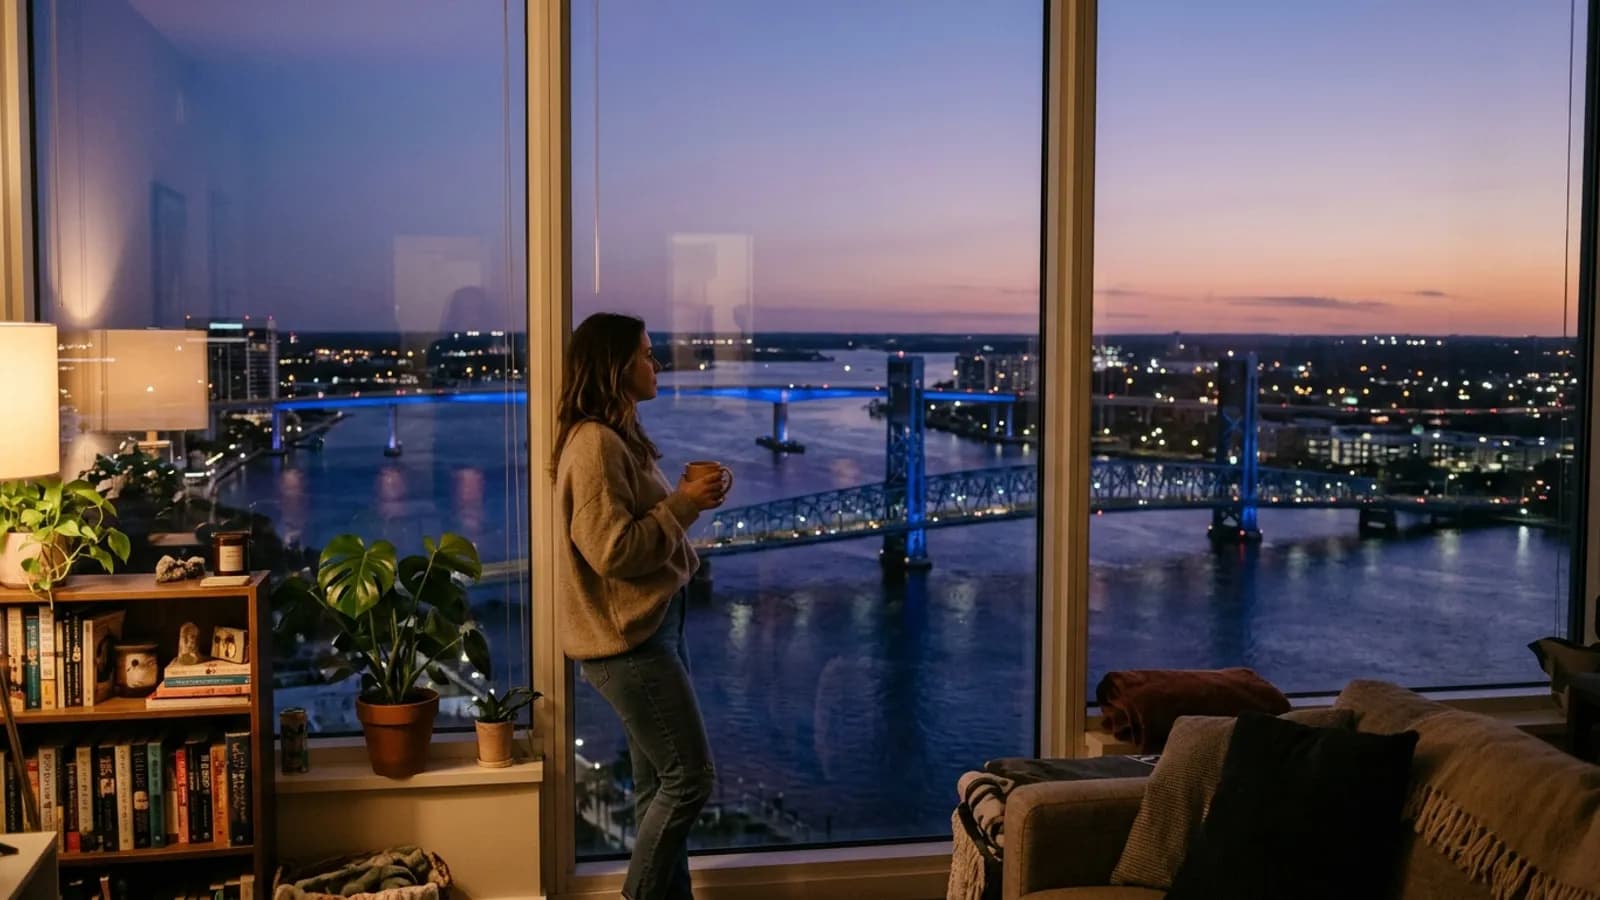
Renters insurance in Jacksonville costs about $15–$23 per month for a standard policy — $20,000–$30,000 of property coverage and $100,000 of liability. The beaches ZIPs price higher on wind. Jacksonville's size means surge and wind claims both reach well inland along the St. Johns River, and the flood policy is the coastal renter's default rather than an optional extra.
What Jacksonville tenants pay
| Profile | Typical cost |
|---|---|
| Florida statewide average | $14–$25 per month |
| Jacksonville standard policy ($20k–$30k property, $100k liability) | $15–$23 per month |
| Add $300k liability + replacement-cost valuation | +$3–$6 per month |
| Auto bundle discount | −5–25% off both policies |
The beaches ZIPs — Atlantic Beach, Neptune Beach, Jacksonville Beach — quote toward the top of the range on wind exposure. Riverside, Avondale, and San Marco sit mid-range with historic-stock water exposure. Downtown and the Southbank towers price on building value. Southside and the suburban corridors quote lowest on newer construction. Jacksonville runs below Miami on every line and roughly level with Tampa; Florida's Gulf-facing metros carry comparable wind pricing.
Why Jacksonville prices the way it does
Wind is Jacksonville's pricing engine: the metro sits on the Atlantic, and its hurricane record — Dora in 1964, Matthew's and Irma's floods in 2016 and 2017 — proves wind and water reach far inland through the St. Johns basin. Carriers price the beaches ZIPs up on wind exposure while the inland corridors carry the same storm frequency at lower loss severity. Florida's statewide reinsurance costs lift the whole market above national norms. Modest theft density keeps the urban lift small compared with the weather line.
Requirements and landlord norms in Jacksonville
Jacksonville complexes require renters insurance, typically at $100,000 of liability, and enforcement is per lease. The repeat move-in checks are the liability limit, the management company listed as an interested party for renewal and cancellation notices — notification only, no coverage granted — and a bound policy rather than a quote. Each leaseholder certifies separately; unrelated roommates each need their own policy. Beaches-area and waterfront-complex landlords increasingly expect tenants to acknowledge the flood exclusion explicitly, since Irma made tenant-side flood surprises a recurring dispute.
The Jacksonville claim pattern
- Hurricane and tropical-storm wind — covered. Matthew and Irma proved the pattern: wind-driven breaches destroy contents well inland, and the renters policy pays the contents side.
- Storm surge and river flooding — excluded. Surge pushes up the St. Johns and ponds through low blocks far from the coast; only a separate NFIP contents-only policy, about $100 per year, pays that claim.
- Water backup in the historic districts — heavy rain overwhelms drains in Riverside and Avondale; backup through drains is endorsable, typically $50–$150 per year. The water damage question page splits backup from flood.
- Theft in Riverside and San Marco — package theft and vehicle break-ins feed claims up to category caps of about $1,500 for electronics and bikes.
- Displacement after a wind event — a covered wind loss that makes the unit unlivable triggers loss of use coverage, priced against post-storm demand that spikes across Northeast Florida.
Coverage setup that fits Jacksonville
- $25,000–$30,000 property with replacement cost — wind events destroy contents at once; the $2–$4-per-month upgrade is the Florida default.
- $300,000 liability — the step above the $100,000 landlord ask costs a dollar or two per month.
- NFIP contents-only flood policy — about $100 per year; the coastal renter's default and the St. Johns-basement renter's too.
- Water backup endorsement — typically $50–$150 per year for the historic-district stock.
- $500 deductible — the $1,000 step saves $1–$3 per month; keep the low deductible at renters price points.
- Landlord certificate and interested-party listing — bind first; complexes verify before key release.
The base-policy guide explains the standard form end to end, and the scheduled property endorsement closes the electronics gap above the $1,500 caps.
Related guides
The Florida state page carries the statewide wind-and-flood rules, and Jacksonville's wind-versus-surge split pairs with the Florida metros that share the exposure.
- Renters Insurance in Florida: Costs and What to Know — statewide wind pricing behind the $15–$23-per-month metro range.
- Renters Insurance: The Complete Guide — the full standard-policy mechanics.
- Renters Insurance in Tampa, FL — bay surge modeling and sinkhole questions on the Gulf side ($15–$23 per month).
- Renters Insurance in Miami, FL — wind-versus-surge at its most acute ($16–$26 per month).
- Does Renters Insurance Cover Natural Disasters? — which hurricane perils ride along and which need separate policies.
Sources
- Florida Office of Insurance Regulation — Florida consumer resources
- NAIC — Consumer resources
Frequently asked questions
How much is renters insurance in Jacksonville?
Renters insurance in Jacksonville runs about $15–$23 per month for a standard policy — $20,000–$30,000 of property coverage and $100,000 of liability. The beaches ZIPs price higher on wind exposure, and the rest of the metro sits mid-range for Florida — below Miami, roughly level with Tampa.
Do Jacksonville landlords require renters insurance?
Yes. Jacksonville complexes require renters insurance, typically at $100,000 of liability. Management adds itself as an interested party and confirms a bound policy — not a quote — before key release. Each leaseholder on a shared lease certifies separately, and verification happens before occupancy, not at renewal.
Does renters insurance cover hurricane wind in Jacksonville?
Yes. Hurricane and tropical-storm wind is a covered peril. Jacksonville's hurricane legacy — Dora crossed the city in 1964, and Matthew and Irma hammered it in 2016 and 2017 — proves the exposure is real well inland. Wind-driven breaches that damage contents file under the standard policy.
Does renters insurance cover storm surge flooding in Jacksonville?
No. Storm surge and any rising water are excluded from every standard renters policy. Jacksonville's size means surge claims reach well inland along the St. Johns River, not just at the beaches. Coastal renters default to an NFIP contents-only flood policy, which starts around $100 a year.
Why do the beaches ZIPs price higher in Jacksonville?
Wind. Atlantic Beach, Neptune Beach, and Jacksonville Beach sit closest to the ocean, so carriers price the wind exposure up in those ZIPs. A standard policy that costs $15–$18 per month inland can run $23 or more at the coast — the difference is wind pricing, not theft or building value.
Is replacement cost coverage worth adding in Jacksonville?
For most Jacksonville tenants, yes. Replacement-cost valuation adds roughly $2–$4 per month over actual cash value and pays today's prices after a loss. Wind events destroy contents all at once, and depreciated payouts cut recovery sharply in exactly the claims Jacksonville generates most.
How we researched this guide
Renters coverage is small and simple, but landlord requirements and state rules vary — so we verify both sides of the lease.
- What HO-4 policies cover (and the liability and loss-of-use mechanics) is verified against standard policy forms and DOI consumer guides.
- Landlord-side insurance requirements are framed against HUD tenant-rights resources, since required coverage limits appear in lease terms, not statutes.
- Cost figures are ranges by state and coverage limit, anchored to NAIC statistics.
- Disaster-aid expectations are set from FEMA guidance: federal assistance is not a replacement for coverage, and we explain exactly what it does pay.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HUD — tenant rights and responsibilities — state landlord-tenant rules that affect liability requirements.
- FEMA — renters and disaster assistance — what federal disaster aid does and does not cover for tenants.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Renters Insurance in Florida: Costs and What to Know (2026)
Renters insurance in Florida costs about $14–$25 per month. Hurricane wind-versus-flood fine print, sinkhole ground, and carrier churn shape what tenants buy.
Read guide
Renters Insurance: The Complete Guide
Renters insurance covers your belongings, your liability, and your hotel bill when the rental is unlivable — what it pays, what it excludes, and how to pay less.
Read guide
Renters Insurance in Tampa, FL: Costs and Guide (2026)
Renters insurance in Tampa costs about $15–$23 per month; what tenants pay, hurricane wind versus storm surge coverage, and the flood questions every season raises.
Read guide
Renters Insurance in Miami, FL: Costs and Guide (2026)
Renters insurance in Miami costs about $16–$26 per month; what Miami tenants pay, the wind-versus-surge coverage line, landlord rules, and the endorsements that matter here.
Read guide
Does Renters Insurance Cover Natural Disasters?
Split — renters insurance covers wildfire, tornado, hail, and hurricane wind damage to belongings; floods and earthquakes are excluded without separate policies.
Read guide