
Renters Insurance in Cincinnati, OH: Costs and Guide (2026)
Renters insurance in Cincinnati costs about $12–$17 per month. Hillside water backup, winter pipe bursts, and Ohio River flood exposure shape the price.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Renters insurance in Cincinnati costs about $12–$17 per month for a standard policy — $20,000–$30,000 of property coverage and $100,000 of liability. The range sits below the national average. Cincinnati's hillside housing and Ohio River exposure pair two water risks the standard policy treats oppositely: backup through drains is endorsable, river flood never is.
What Cincinnati tenants pay
| Profile | Typical cost |
|---|---|
| Ohio statewide average | $12–$18 per month |
| Cincinnati standard policy ($20k–$30k property, $100k liability) | $12–$17 per month |
| Add $300k liability + replacement-cost valuation | +$3–$6 per month |
| Auto bundle discount | −5–25% off both policies |
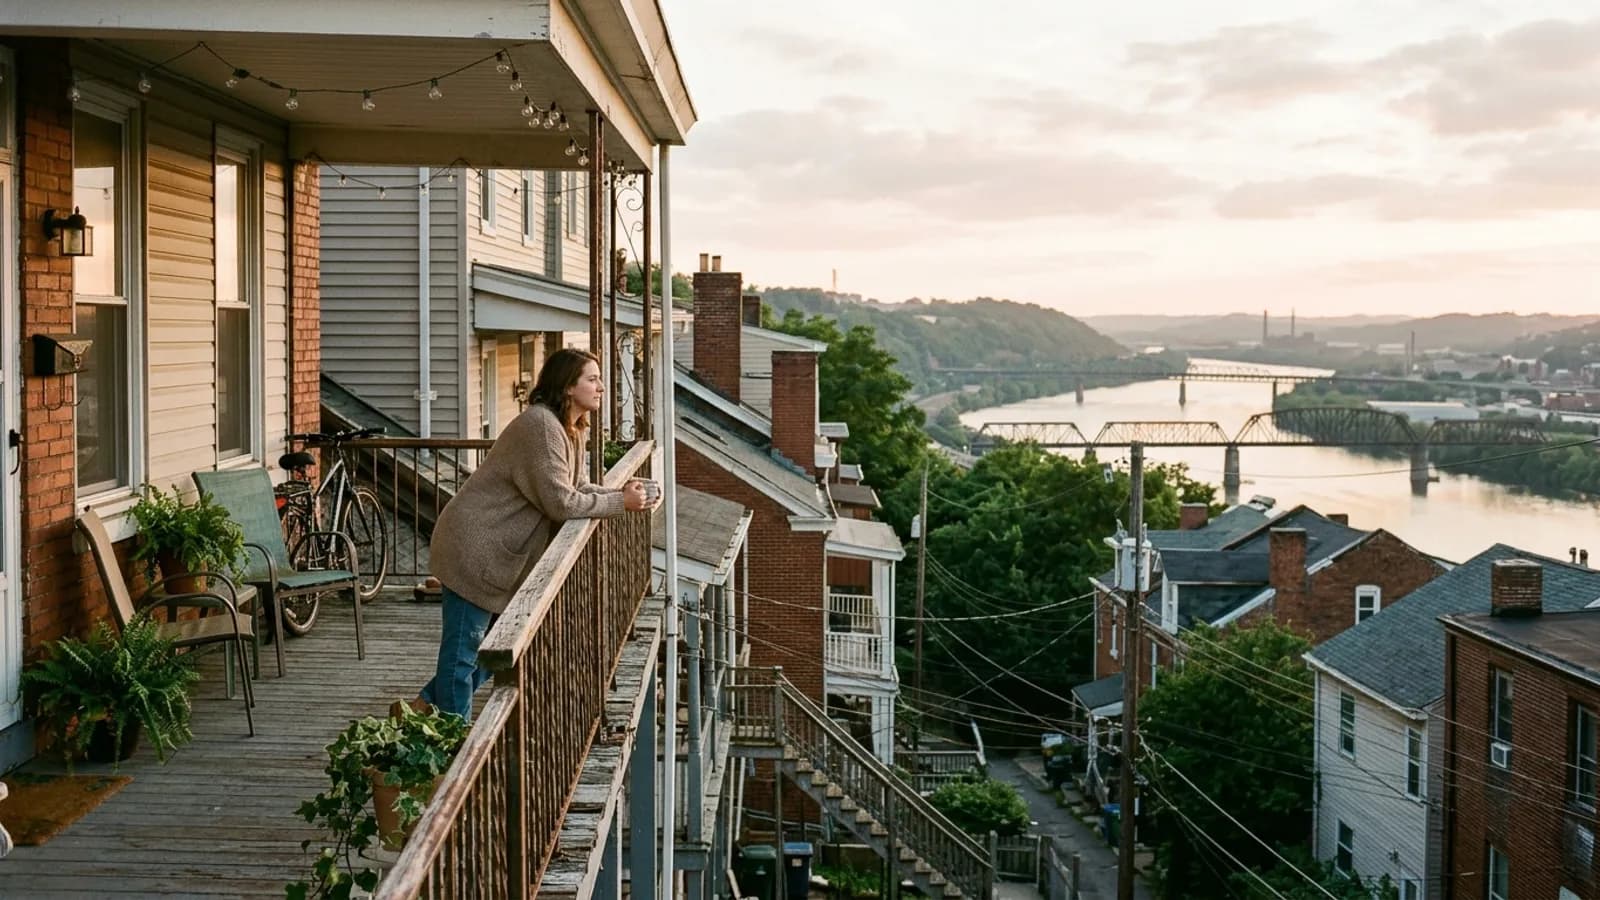
Pricing follows the hills and the housing stock. Over-the-Rhine's redeveloped historic stock quotes toward the top of the range on replacement costs. Mount Adams and Hyde Park sit mid-range with elevated building age. Clifton's university-adjacent rentals price on student turnover theft. Price Hill and Camp Washington's hillside housing quotes lower on rent value but carries the city's steepest backup exposure. Columbus and Cleveland price similarly; Cincinnati's edge is the river.
Why Cincinnati prices the way it does
Building age on the hills drives the claim mix: Over-the-Rhine's pre-war stock and the hillside neighborhoods' aging plumbing concentrate backup and freeze losses in ways Ohio's newer metros do not. Steep terrain accelerates runoff — heavy rain collects in the basin and overwhelms the older combined drains. The Ohio River sets the flood boundary: low-lying blocks along the riverfront flood when the pool rises, as in the 1997 flood, and that risk never prices into the renters premium because the peril is excluded. University of Cincinnati turnover adds theft lift around Clifton.
Requirements and landlord norms in Cincinnati
Cincinnati landlords require renters insurance commonly, at $100,000 of liability as the standard ask. The repeat move-in checks are the liability limit, the landlord or management company listed as an interested party for renewal and cancellation notices — notification only, no coverage granted — and a bound policy rather than a quote. Each leaseholder certifies separately; unrelated roommates each need their own policy. OTR redevelopment management and the university-area landlords increasingly ask student tenants to confirm coverage before August move-ins.
The Cincinnati claim pattern
- Water backup in the hilly districts — heavy rain overwhelms combined drains in Over-the-Rhine, Price Hill, and Camp Washington. Excluded by default; the endorsement runs $50–$150 per year. The water damage question page separates backup from flood.
- Ohio River flooding — riverfront and Mill Creek lowlands flood when the pool rises. Rising water is excluded outright; river-adjacent tenants buy an NFIP contents-only policy at about $100 per year.
- Winter pipe bursts — sudden bursts in hillside older housing are covered; units vacant between tenancies are the classic loss. Slow leaks are maintenance and denied.
- Student-corridor theft — UC turnover drives theft claims around Clifton; category caps of about $1,500 apply to electronics and bikes.
- Displacement after a water event — a covered burst or backup that makes the unit unlivable triggers loss of use coverage for extra living costs.
Coverage setup that fits Cincinnati
- $25,000–$30,000 property with replacement cost — backup and burst events damage whole floors at once; the $2–$4-per-month upgrade is the default.
- $300,000 liability — the step above the $100,000 landlord ask costs a dollar or two per month.
- Water backup endorsement — the essential Cincinnati add-on; typically $50–$150 per year.
- $500 deductible — the $1,000 step saves $1–$3 per month; keep the low deductible.
- NFIP contents-only flood policy — about $100 per year for riverfront and Mill Creek-adjacent units.
- Landlord certificate and interested-party listing — bind first; OTR and university-area landlords verify before key release.
The base-policy guide explains the standard form end to end, and the claim process guide walks the documentation steps water claims demand.
Related guides
The Ohio state page carries the statewide rules, and Cincinnati's backup-and-river pairing links to the Ohio River sibling and the state's other big rental market.
- Renters Insurance in Ohio: Costs and What to Know — the statewide cost picture behind the $12–$17-per-month metro range.
- Renters Insurance: The Complete Guide — the full standard-policy mechanics.
- Renters Insurance in Columbus, OH — winter pipes and student turnover theft in the state capital ($13–$18 per month).
- Renters Insurance in Louisville, KY — the Ohio River flood exposure on the downstream side ($12–$17 per month).
- The Renters Insurance Claim Process — from documentation to reimbursement for water claims.
Sources
- Ohio Department of Insurance — Ohio consumer resources
- NAIC — Consumer resources
Frequently asked questions
How much is renters insurance in Cincinnati?
Renters insurance in Cincinnati runs about $12–$17 per month for a standard policy — $20,000–$30,000 of property coverage and $100,000 of liability. That range sits below the national average and at the low end of Ohio, with hillside and river-adjacent neighborhoods carrying the different risk mix.
Do Cincinnati landlords require renters insurance?
Yes. Cincinnati landlords require renters insurance commonly, particularly in the Over-the-Rhine and Clifton rental stock and the larger multifamily operators. Most leases set a $100,000 liability minimum, add the landlord as an interested party, and confirm a bound policy before move-in.
Does renters insurance cover water backup in Cincinnati?
Not by default. Backup through drains and sewers is excluded from the standard policy, and Cincinnati's hilly older districts — Over-the-Rhine, Price Hill, Camp Washington — concentrate that exposure. The water backup endorsement typically costs $50–$150 per year and is the city's essential add-on.
Does renters insurance cover Ohio River flooding in Cincinnati?
No. River flooding is rising water, and rising water is excluded from every standard renters policy regardless of the source. The 1997 flood remains the benchmark Cincinnati event. Belongings damaged by river flood need a separate NFIP contents-only flood policy, which starts around $100 a year.
Does renters insurance cover burst pipes in a Cincinnati winter?
Sudden pipe bursts are covered. Cincinnati's older hillside housing freezes through cold snaps, and units left vacant between tenancies burst lines most often. Keep the unit heated, document the burst immediately, and note that slow leaks are treated as maintenance and denied.
Is replacement cost coverage worth adding in Cincinnati?
For most Cincinnati tenants, yes. Replacement-cost valuation adds roughly $2–$4 per month over actual cash value and pays today's prices after a loss. Backup and burst events damage whole floors of belongings at once, and depreciated payouts cut recovery sharply in that scenario.
How we researched this guide
Renters coverage is small and simple, but landlord requirements and state rules vary — so we verify both sides of the lease.
- What HO-4 policies cover (and the liability and loss-of-use mechanics) is verified against standard policy forms and DOI consumer guides.
- Landlord-side insurance requirements are framed against HUD tenant-rights resources, since required coverage limits appear in lease terms, not statutes.
- Cost figures are ranges by state and coverage limit, anchored to NAIC statistics.
- Disaster-aid expectations are set from FEMA guidance: federal assistance is not a replacement for coverage, and we explain exactly what it does pay.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HUD — tenant rights and responsibilities — state landlord-tenant rules that affect liability requirements.
- FEMA — renters and disaster assistance — what federal disaster aid does and does not cover for tenants.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Renters Insurance in Ohio: Costs and What to Know (2026)
Renters insurance in Ohio costs about $12–$18 per month, among the cheapest. Hard freezes, tornado winds, and old-sewer backups shape what Ohio tenants set up.
Read guide
Renters Insurance: The Complete Guide
Renters insurance covers your belongings, your liability, and your hotel bill when the rental is unlivable — what it pays, what it excludes, and how to pay less.
Read guide
Renters Insurance in Columbus, OH: Costs and Guide (2026)
Renters insurance in Columbus costs about $13–$18 per month. Winter pipe bursts, sewer backup, and OSU-area student turnover theft shape the price.
Read guide
Renters Insurance in Louisville, KY: Costs and Guide (2026)
Renters insurance in Louisville costs about $12–$17 per month. Ohio River flood exclusion, tornado wind, and below-average rates shape the price.
Read guide
The Renters Insurance Claim Process: From Theft to Reimbursement
Renters claims are won by documentation — police report, photos before cleanup, itemized inventory — and most simple claims pay within one to two weeks.
Read guide