
Does Homeowners Insurance Cover Trampolines?
Trampoline coverage depends on the insurer: some allow them with safety conditions, some exclude trampoline liability, and some decline or non-renew the policy.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Trampoline coverage depends on the insurer: some cover them with safety conditions (netting, fencing), some exclude trampoline liability entirely, and some require removal before binding. The injury statistics — tens of thousands of emergency visits a year, mostly children — drive the restriction.
The carrier's four positions, and which one yours takes
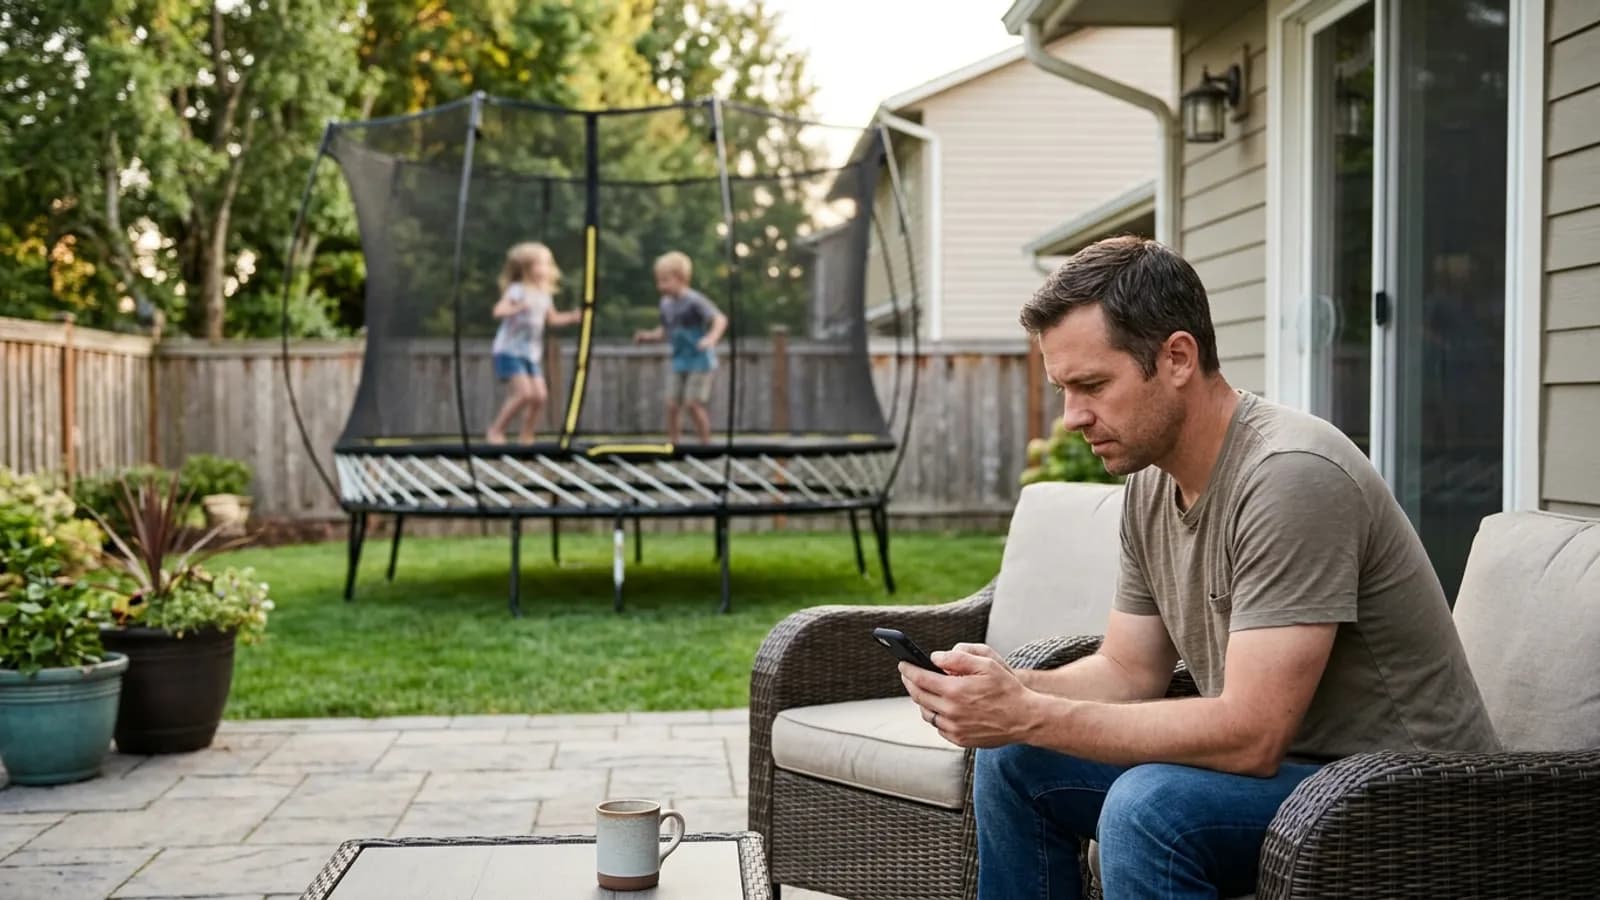
Trampoline underwriting sorts into four positions, and knowing yours before the purchase beats discovering it after an injury. Permitted with conditions is the most common standard: netting, fencing, or both, with the carrier's conditions listed in writing. Permitted without conditions is rare, usually on policies without trampoline-specific wording. Excluded from liability is the middle position — some carriers write a trampoline liability exclusion endorsement, which makes any bounce-related injury claim yours to fund. Decline or non-renewal is the hard position, common when a trampoline exists undisclosed and the carrier finds it at inspection or renewal. The structural driver is the injury profile: trampoline injuries send tens of thousands of people, disproportionately children, to emergency departments each year, with fractures and head injuries leading the list. Because the injured party is usually a neighbor child on an uninvited bounce, the attractive-nuisance doctrine applies, and the liability claim can exceed the base limit — which is why carriers scrutinize trampolines more than the trampoline's cost would suggest.
| Carrier position | What it means at claim time |
|---|---|
| Permitted with conditions | Coverage stands while netting and fencing requirements are met |
| Permitted without conditions | Rare; usually a policy with no trampoline-specific wording |
| Liability exclusion endorsement | Bounce-related injury claims become the homeowner's to fund |
| Decline or non-renewal | The common outcome after an undisclosed trampoline is found |
Position two deserves a caution: permitted-without-conditions means the general liability section answers a bounce injury, with no trampoline-specific terms to violate — but it also means no carrier guidance on the safety setup, which is why the written position matters more than the verbal one. Ask the carrier to state its position in writing and file the answer with the policy. The written record decides two later disputes at once: whether a claim is covered, and whether a safety condition was violated before the injury.
The disclosure question and the inspection reality
Trampolines are visible from the street and from aerial imagery, and carriers underwrite renewals with geospatial inspection increasingly often, so the undisclosed trampoline is discovered, not hidden. The consequences of discovery: mid-term cancellation in some states, non-renewal at term end in most, or a forced exclusion endorsement. Disclosure, by contrast, is a five-minute call that produces one of the four positions and usually a modest premium adjustment. The second timing question is the sale-of-home scenario: a trampoline you own sits on the policy, while a trampoline that came with the house needs a coverage answer at application, not at the first claim. And the rental-property version: a landlord whose tenant installs a trampoline faces both the liability exposure and the lease question — the standard landlord move is a lease clause barring trampolines precisely because the carrier's position is unknowable mid-lease. The clause converts an unknowable insurance position into an enforceable contract term, and the landlord's DP-3 carrier faces the same four positions.
The safety specification carriers actually ask for
The carrier checklist maps to injury data. Netted enclosure: reduces fall-off injuries, the leading mechanism — most carriers that permit trampolines require it. Four-foot fencing with a self-latching gate: the attractive-nuisance control that addresses uninvited use, the highest-severity liability scenario. Placement away from concrete, fences, and structures: landing-surface injuries are the fracture mechanism. One-bounce rule: the majority of serious injuries happen with multiple simultaneous users, so household rules matter at claim time — an incident report noting three children on the trampoline complicates the defense. Maintenance: torn nets and missing pads convert a compliant trampoline into the non-compliant version carriers photograph at renewal. The coverage-side supplement: raise liability to $300,000–$500,000 and consider an umbrella policy — the injury profile is the classic claim that outruns a base limit. Nondisclosure of the trampoline, like any material fact, creates a concealment problem carriers act on. The pool version of this underwriting profile is covered in the swimming pool guide.
Related guides
Trampoline underwriting sits beside the other liability-magnet pages, because carriers apply the same disclosure-and-conditions logic to each.
- Does Homeowners Insurance Cover Swimming Pools? — the attractive-nuisance duty ladder behind both backyard hazards.
- Does Homeowners Insurance Cover Dog Bites? — the third classic liability exposure carriers underwrite by breed and history.
- What Is Umbrella Insurance? — how $1M of extra liability sits over the home policy for roughly $20 a month.
- How to Choose the Best Home Insurance Company — finding a carrier whose trampoline and hazard positions match your property.
Sources
Frequently asked questions
Will my insurance drop me for having a trampoline?
Some will, many will not — the position depends on the carrier and your state. The common outcomes at disclosure: permitted with netting and fencing conditions, a small surcharge, or a trampoline liability exclusion. The outcomes for nondisclosure are worse: non-renewal or mid-term cancellation after discovery. Call before installing, get the carrier's conditions in writing, and photograph the safety setup once complete.
Does homeowners insurance cover a neighbor kid injured on my trampoline?
Generally yes if your policy permits trampolines — your personal liability coverage answers injury claims from guests and trespassing children alike, subject to the attractive-nuisance doctrine. If your policy carries a trampoline exclusion, the same claim becomes your personal financial exposure, which is the scenario umbrella policies and trampoline exclusions are argued over. Know which position your carrier took, in writing.
What trampoline safety features do insurers require?
The common requirements: a full-perimeter safety net in good repair, four-foot fencing with a self-latching gate to control uninvited use, and placement away from hard surfaces and structures. Some carriers add spring-cover and pad requirements. Requirements vary by carrier, so get the specific list from yours — a trampoline that meets one carrier's standard may fail another's, and the difference shows up at claim time.
What happens if I do not disclose a trampoline?
Discovery is likely, because trampolines are visible from the street and from the aerial imagery carriers use at renewal. The consequences run from a forced exclusion endorsement to non-renewal to mid-term cancellation in some states, and an injury claim on an undisclosed trampoline hands the insurer a concealment defense. The disclosure call is five minutes; the denial is permanent.
How much liability coverage do trampoline owners need?
Commonly $300,000–$500,000 on the home policy, with an umbrella policy above it — the injury profile behind trampoline claims, child fractures and possible head injuries, is the classic claim that outruns a base limit. Because the injured party is often an uninvited neighbor child, the attractive-nuisance doctrine makes the claim hard to defend. Limits are the lever you control before the bounce.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Does Homeowners Insurance Cover Dog Bites?
Usually yes — homeowners liability covers dog bites. Breed exclusions and bite-history rules vary by insurer; the average claim pays $50,000+.
Read guide
What Is Umbrella Insurance? How $1M of Liability Costs ~$20/Month
Umbrella insurance adds $1M+ of liability protection over your auto and home policies for roughly $150–$400 per year. What it covers and requires.
Read guide
What Does Homeowners Insurance Cover? (And What It Never Covers)
A standard HO-3 covers fire, wind, hail, theft, and burst pipes — and never floods, earthquakes, or gradual damage. The coverage buckets, exclusions, and fixes.
Read guide
How to Choose the Best Home Insurance Company (No Sponsored Rankings)
Choose a home insurer on claims satisfaction, financial strength, coverage breadth, and state-market position — the criteria that replace sponsored rankings.
Read guideWhat Is Liability Insurance?
Liability insurance pays others when you're legally responsible for their injuries or property damage — plus the legal defense — and never pays your own losses.
Read guide