
Does Homeowners Insurance Cover Dog Bites?
Usually yes — homeowners liability covers dog bites. Breed exclusions and bite-history rules vary by insurer; the average claim pays $50,000+.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
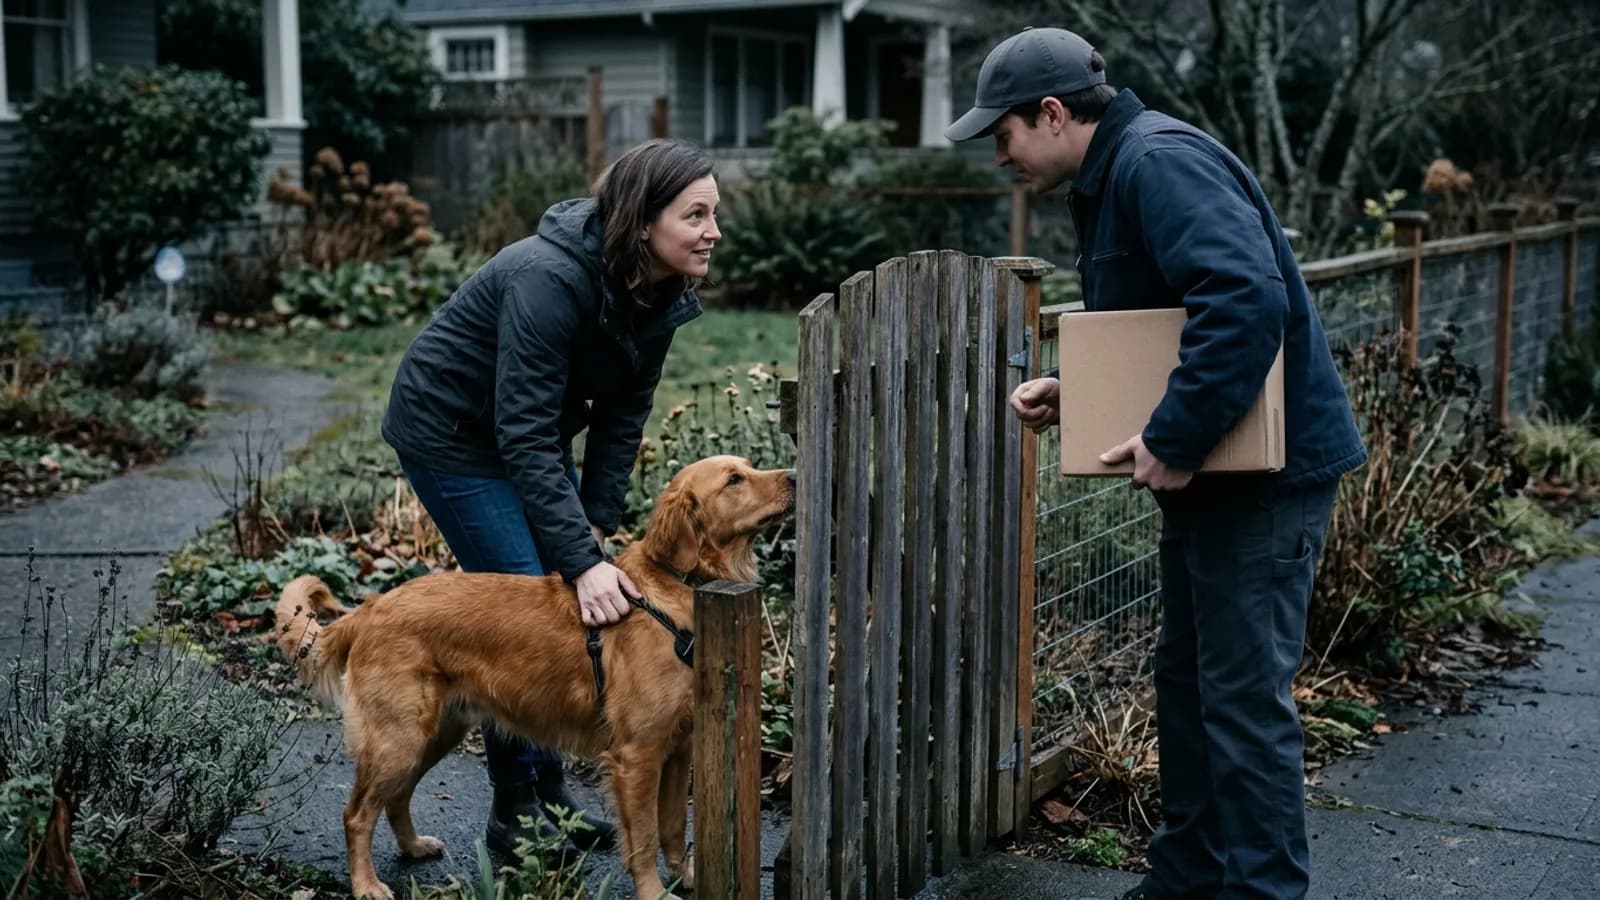
Usually yes — homeowners liability covers dog bites on or off your property, subject to breed exclusions and bite-history rules that vary by insurer. The average bite claim pays $50,000 or more, which is why this is the liability claim that introduces owners to umbrellas.
The deciding line: liability, subject to the dog
Dog bites run through the liability section of the homeowners policy — they are liability claims, not property claims, and they count for over a third of homeowners liability claims nationally. The coverage: medical bills, lost wages, and legal claims for bites on or off your property. The edges: breed lists (carrier-specific), known aggressive history, and sometimes undisclosed dogs. The coverage map shows where liability sits in the policy; the umbrella guide covers the layer above it.
What actually gets paid on a bite claim
A serious bite claim runs through two coverage layers with different jobs. Medical payments coverage (typically $1,000–$5,000) settles the small stuff quickly: the ER visit, stitches, tetanus shot — no fault-finding required, which is why it is worth offering immediately. The liability layer is the real exposure: reconstructive surgery, infection treatment, lost wages, and scarring claims routinely reach five figures, and the average bite claim across the industry is commonly reported at $50,000 or more. Liability pays the injured party's damages up to your limit — commonly $100,000–$300,000 on standard policies — and funds your legal defense inside that limit. This is the claim type that most often exhausts a base liability limit: a child bitten in the face is the scenario where settlement demands exceed $300,000.
The state-law split: strict liability versus one-bite
Whether you pay turns on state law as much as policy terms. Strict-liability states hold owners responsible for bites regardless of the dog's history — no proof of negligence needed. One-bite states require the victim to show the owner knew or should have known the dog was dangerous — a prior incident, a complaint on file. A middle tier applies negligence standards with statutory thresholds. The practical consequence is on the documentation side: in every state, a documented prior bite or aggressive incident becomes evidence in the next claim, which is why the application question ("has the animal bitten anyone?") is answered honestly or not at all — an undisclosed bite history is a textbook misrepresentation denial. Also verify your municipality's reporting duty; most require reporting bites to animal control within 24 hours.
The underwriting ladder for the dog the carrier dislikes
Carriers sort dogs into three tiers. Accepted breeds are covered normally. Restricted breeds (a carrier-specific list that often includes pit bull-type dogs, Rottweilers, Presa Canarios, and wolf hybrids) may be excluded from liability, accepted with conditions like certification completion, or priced with a surcharge — a few states restrict how far breed-based exclusions can go, so the state DOI is the authority on the limits. Excluded or declined risks leave owners with the specialty market: standalone canine liability policies and animal-liability endorsements written for exactly this exposure, commonly offering $25,000–$300,000 limits for a few hundred dollars a year. Two rules hold across all tiers: the dog must be disclosed at application and at any new-adoption moment, and fencing, leashing, and training certifications are the cheapest premium lever in this niche.
Related guides
The bite claim connects to the attractive-nuisance exposures, the small-claims layer, and the coverage map behind the verdict.
- Does Homeowners Insurance Cover Trampolines? — the other attractive-nuisance liability in the same policy.
- Does Homeowners Insurance Cover Swimming Pools? — the attractive-nuisance exposure with the same claim anatomy.
- What Is Medical Payments (MedPay) Coverage? — the small-claims layer that settles the ER visit fast.
- What Is Policy Rescission? — the remedy for an undisclosed bite history.
- Home Insurance: The Complete Guide — the hub framing the whole policy.
Sources
Frequently asked questions
How much does a dog bite claim pay?
The average industry dog-bite claim commonly pays $50,000 or more, through the liability section of the homeowners policy. Medical payments coverage (typically $1,000–$5,000) settles the small emergency-room claims quickly without fault-finding; liability pays the injured party's damages up to your limit — commonly $100,000–$300,000 — and funds your legal defense inside that limit.
Which dog breeds do insurers exclude?
Commonly: pit bull types, Rottweilers, Dobermans, Chows, Presa Canarios, and wolf hybrids — carrier lists differ, and a few states restrict breed-based exclusions. Restricted breeds may be excluded from liability, accepted with conditions like training certification, or surcharged. The canine-liability endorsement and the standalone animal-liability market are the routes for excluded breeds.
Does my homeowners liability cover a bite at the dog park?
Generally yes — your dog is your liability exposure wherever it is, subject to policy terms, though a leash-law violation can complicate the negligence picture. The off-premises liability of an HO-3 normally follows the dog, and some policies narrow it for dogs with bite histories or excluded breeds. Check the animal-liability wording rather than assuming the park is covered space.
Will my insurer cancel me after one bite claim?
A single bite claim is more likely to produce a surcharge, a breed-specific exclusion, or a non-renewal than an immediate cancellation, depending on severity and state rules. Carriers treat dog-bite losses among the highest-severity liability claims, so two bites commonly ends the relationship. The mitigation is coverage structure: higher liability limits and an umbrella so one incident does not become a personal financial event.
Can I buy liability coverage for a breed most insurers exclude?
Yes — the canine-liability and animal-liability specialty market exists for exactly this. Standalone policies commonly offer $25,000–$300,000 limits, underwrite the individual dog (training, containment, history) instead of only the breed, and price from a few hundred dollars a year. Expect requirements: sterilization or training certification, secure fencing, and a signed disclosure of bite history.
What if my dog bit someone before I bought the policy?
Prior bite history is disclosable and insurable at some carriers (with surcharges or conditions) and uninsurable at others — concealing it is rescission territory, and an undisclosed bite history is a textbook misrepresentation denial. Disclose on the application and at any new-adoption moment; a mid-term addition is an endorsement call, not a hope.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Home Insurance: The Complete Guide
Homeowners insurance pays to rebuild, replace, and defend after fire, storms, and lawsuits — this guide maps coverage, exclusions, deductibles, and costs by state.
Read guide
What Is Umbrella Insurance? How $1M of Liability Costs ~$20/Month
Umbrella insurance adds $1M+ of liability protection over your auto and home policies for roughly $150–$400 per year. What it covers and requires.
Read guide
Does Homeowners Insurance Cover Trampolines?
Trampoline coverage depends on the insurer: some allow them with safety conditions, some exclude trampoline liability, and some decline or non-renew the policy.
Read guide
What Does Homeowners Insurance Cover? (And What It Never Covers)
A standard HO-3 covers fire, wind, hail, theft, and burst pipes — and never floods, earthquakes, or gradual damage. The coverage buckets, exclusions, and fixes.
Read guideWhat Is Liability Insurance?
Liability insurance pays others when you're legally responsible for their injuries or property damage — plus the legal defense — and never pays your own losses.
Read guide