
How to Lower Homeowners Insurance: 10 Moves Ranked by Impact (2026)
Ten moves lower homeowners insurance: the deductible, the roof, bundling, claims discipline, and the annual re-shop, with the traps that cost more than they save.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
The biggest levers on homeowners insurance are structural — your deductible, your roof, and your claims discipline — and the biggest mistake is loyalty. This page ranks the ten moves by what they actually save per year, then works the math behind the three that matter most.
1. The deductible dial (10–25% savings)
Moving from $1,000 to $5,000, or from a low flat deductible to a higher one, cuts the premium 10–25% on typical profiles: a $2,200 policy commonly saves $250–$400 per year at $2,500 and $400–$650 at $5,000. The test stays the same — payable tomorrow? In wind and hail states, check whether the policy uses percentage wind deductibles of 1–5% of dwelling, which means $4,000–$20,000 on a $400,000 home; the mechanics sit in the deductible explainer and the wind/hail deductible guide.
2. The roof (the surcharge king)
Insurers price roof age and material more than almost any property factor. Replacing a 20-year roof produces 10–25% savings in many states plus replacement-cost roof schedules, and impact-resistant shingles earn dedicated discounts in hail states. Document the work: the contractor invoice is the discount, and it belongs with the renewal quote, not in a drawer.
3. Claims discipline (the invisible savings)
The CLUE report follows you and the property for 5–7 years. Run repair quotes before filing sub-deductible losses, mitigate small damage yourself, and bank the claim-free record. Loss type matters as much as count: one water-damage claim can trigger non-renewal more reliably than two hail claims, because carriers read water losses as a maintenance signal.
4. The annual re-shop (loyalty is not rewarded)
Re-quote every 1–2 years with an independent agent or aggregator — the same house sees pricing dispersion of 20% or more between carriers, especially in disrupted markets such as Florida, California, and Texas. The switching mechanics mirror car insurance: never lapse coverage, match limits line by line, and mind the escrow payoff when you switch mid-escrow-year. The escrow note in practice: the servicer's payoff check follows the switch, and the old carrier's refund for unused months belongs to the escrow account rather than to you personally.
5. Bundle (5–25%)
Auto plus home with one carrier remains the easiest discount in insurance, worth 5–25% off both policies. Renters bundles work the same way for tenants — see renters insurance — and the bundle survives a move, so it is the discount to preserve through every relocation.
6. Security and systems discounts
Monitored alarms, smart water-shutoff devices, deadbolts, sprinkler systems, and updated electrical, plumbing, and HVAC all earn credits. The water-shutoff device is the rare discount that also prevents the claim type that gets policies non-renewed — a $1,000–$2,500 install that converts five-figure water losses into sub-deductible ones.
7. Right-size the dwelling coverage
Insure rebuild cost, not market price — and do not carry inflated coverage from a stale estimate. Conversely, under-insuring is the costlier error, because partial losses settle proportionally; the coverage map in what homeowners insurance covers explains the mechanics. Extended-replacement-cost riders cost little and protect the limit against construction inflation.
8. Ask for the full discount list
New-home, claims-free (3–5 years), retiree or age 55+, non-smoker, profession and affinity groups, new wiring and plumbing — several never apply automatically. The annual discount audit on a stale policy commonly finds $150–$400 per year, which makes it the highest-value 10 minutes in this whole list.
9. Mitigate the liability surprises
Pools, trampolines, and certain dog breeds trigger surcharges or coverage restrictions. Fencing, alarms, and disclosure keep the policy clean; concealment is how claims get denied and policies get cancelled. The liability surcharges are the premium you pay for exposure you chose — manage the exposure instead of shopping away the surcharge.
10. Consider the surplus-lines reality check
In hard markets, admitted carriers exit and surplus-lines carriers fill the gap at higher prices. Before assuming insurance is just expensive now, re-shop the admitted market annually — entry windows reopen, and a carrier that declined three years ago may write the home today at standard terms.
What not to do
- Dropping liability or dwelling limits to cut cost — the savings are trivial and the exposure is not.
- Skipping flood insurance because the premium rose — the flood exclusion is independent of your budget.
- Under-reporting the trampoline, pool, or dog — a denial plus rescission risk for a small surcharge saved.
- Chasing the cheapest quote onto an ACV roof schedule — the savings reappear as a five-figure gap at the first hail claim.
- Leaving a coverage gap between policies during a move — a one-week lapse is the gap that reprices the next quote and voids the claim in between.
The claims-surcharge payback rule, quantified
The cheapest premium reduction is the one you never spend: the small claim not filed. The mechanics of a small claim's true cost: a $1,200 water loss on a $1,000 deductible pays $200 — and adds a loss entry to the CLUE report and the carrier's internal file, where it commonly surcharges renewals for three to five years. The surcharge on a typical $2,200 premium commonly runs 10–30% in the years after a property claim, or $220–$660 per year, so the $200-payout claim can cost $1,000 or more across its lifetime. The payback rule agents use: self-fund losses under roughly two deductibles' worth of damage, and reserve claims for events that genuinely require them — water losses exceeding mitigation-plus-repairs you can absorb, liability events, anything with an injury. The household that self-funds two small losses per decade saves more than most discount programs deliver, and the claims process guide covers the filing decision in detail.
The roof certification and wind-mitigation route
In wind and hail states, two documents reprice the premium more than any purchase. The wind-mitigation report — Florida's system is the model, with an inspector documenting roof deck attachment, roof-to-wall connections, opening protection, and secondary water resistance — commonly earns double-digit-percentage discounts on the wind portion of the premium for a report that costs a few hundred dollars, with a payoff period of one to two years in Florida. The roof certification is an inspector's statement of the roof's remaining life, commonly 3–5 years, that converts a 22-year-old roof from a decline risk into a writable one, keeping the home in the standard market at all. The wider mitigation list insurers price: impact windows and opening protection in hurricane states, monitored alarms everywhere, leak-detection devices, and updated-systems documentation from your renovation invoices. Submit the reports with the renewal quote rather than mid-term, and ask every carrier to price them. The percentage-deductible context these reports interact with is worked in the hail damage guide.
The re-shop discipline and the discount audit
Two habits produce savings that outlast any single discount. The re-shop discipline: price the same coverage through three carriers every one to two years, because each carrier's loss models and appetite move independently and repricing variance on an unchanged home commonly runs 20% or more; the agent channel does this for you if you ask for a market sweep at each renewal, and the direct channel requires you to do it yourself. The discount audit: most carriers apply discounts only when asked — the annual list to run covers bundled auto (5–25% off both policies), new-home or new-roof discounts, claims-free status, security devices, age or retiree discounts, professional-affinity programs, paid-in-full and paperless billing, and the mitigation reports above. The math worth knowing: the discount audit on a stale policy commonly finds $150–$400 per year, the re-shop on a repriced market commonly finds more, and the cost guide explains which rating factors each lever actually moves. Neither habit requires changing coverage — both require a calendar reminder, and the annual audit checklist is the template.
Related guides
The levers on this page connect to the cost and coverage pages, because every dollar saved starts with knowing what the premium prices.
- How Much Is Homeowners Insurance? — the annual cost bands and the rating factors behind them, quoted per year.
- Annual Insurance Audit Checklist — the 30-minute review that applies this page's moves at renewal.
- Does Homeowners Insurance Cover Hail Damage? — percentage deductibles and roof schedules that shape the deductible and roof moves.
- Flood Insurance — the separate policy the "what not to do" list warns against skipping.
- How to Choose the Best Home Insurance Company — how to run the annual re-shop without cutting coverage.
Sources
Frequently asked questions
How can I lower my homeowners insurance premium?
Ranked by impact: raise the deductible to a payable level (10–25% savings), replace an aging roof (the single biggest surcharge trigger), bundle with auto (5–25%), keep the claims record clean (a $1,400 claim costs more than it pays once CLUE surcharges count), add monitored security, ask for every discount, and re-shop every 1–2 years — loyalty pricing rarely rewards staying.
Does filing a small claim raise home insurance?
Yes — claims history via CLUE reports follows you and the property for 5–7 years and drives renewal surcharges or non-renewals. The math to run before filing: payment after deductible versus the multi-year surcharge. A claim that pays $500 net can cost $1,000 or more over the surcharge window, which is why agents recommend self-funding losses under roughly two deductibles.
Does a new roof lower home insurance?
Often significantly — insurers price roof age and material heavily, and many now surcharge or restrict policies on roofs over 15–20 years. A replacement can cut the premium 10–25% in hail and wind states and upgrade an ACV roof schedule to replacement cost. Keep the contractor's documentation and submit it with the renewal, because the invoice is the discount.
Why did my home insurance go up when I never filed a claim?
Three forces: rebuild-cost inflation, because labor and materials feed the dwelling coverage number; reinsurance repricing after record catastrophe years; and your state's risk environment — hail, wildfire, and hurricane losses. None of it is personal, and none of it means you cannot re-shop: repricing variance across carriers on an unchanged home commonly runs 20% or more.
How much does raising my deductible actually save?
Commonly 10–25% of the premium: on a $2,200 policy, the step from $1,000 to $2,500 typically saves $250–$400 per year, and $1,000 to $5,000 saves $400–$650. The break-even is the claim you absorb instead: at $300-per-year savings, five claim-free years fund the difference. The honesty check comes first — the deductible must be payable tomorrow from your emergency fund.
Do impact windows pay for themselves in insurance savings?
Partly — opening protection earns meaningful wind-portion discounts in hurricane states, and Florida's wind-mitigation discounts are the documented model. The premium savings commonly contribute 10–20% of the installation cost over the years. The larger payback is the claim that never happens and the insurability that persists: impact-rated homes stay writable in markets where carriers are exiting.
How we researched this guide
Home policies are forms-driven: the peril list in the form decides what gets paid, so our guides follow the policy form structure.
- Coverage explanations track the standard HO-3/HO-5 form structure — Coverage A through E — because that's the contract language adjusters apply.
- Flood facts come from FEMA's National Flood Insurance Program (floodsmart.gov), since standard home policies exclude flood.
- Regional cost ranges are built from NAIC home-owners insurance statistics, with the drivers of variation (construction, age, wind/hail exposure) named explicitly.
- Mitigation and eligibility claims cite IBHS research and state fair-plan rules where standard market access is an issue.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- FEMA — National Flood Insurance Program (FloodSmart) — flood coverage, which standard homeowners policies exclude.
- Insurance Institute for Business & Home Safety (IBHS) — property-loss research and mitigation standards that affect eligibility and discounts.
- U.S. Department of Housing and Urban Development (HUD) — FHA-insured property requirements and disaster assistance programs.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
How Much Is Homeowners Insurance?
Homeowners insurance costs $1,500–$3,000 per year for typical coverage, and state risk, roof age, and your deductible choices decide where you land.
Read guide
Annual Insurance Audit Checklist (30 Minutes)
A 30-minute annual audit: verify dwelling limits against rebuild cost, pull the CLUE report, sweep endorsements and beneficiaries, and re-shop both policies.
Read guide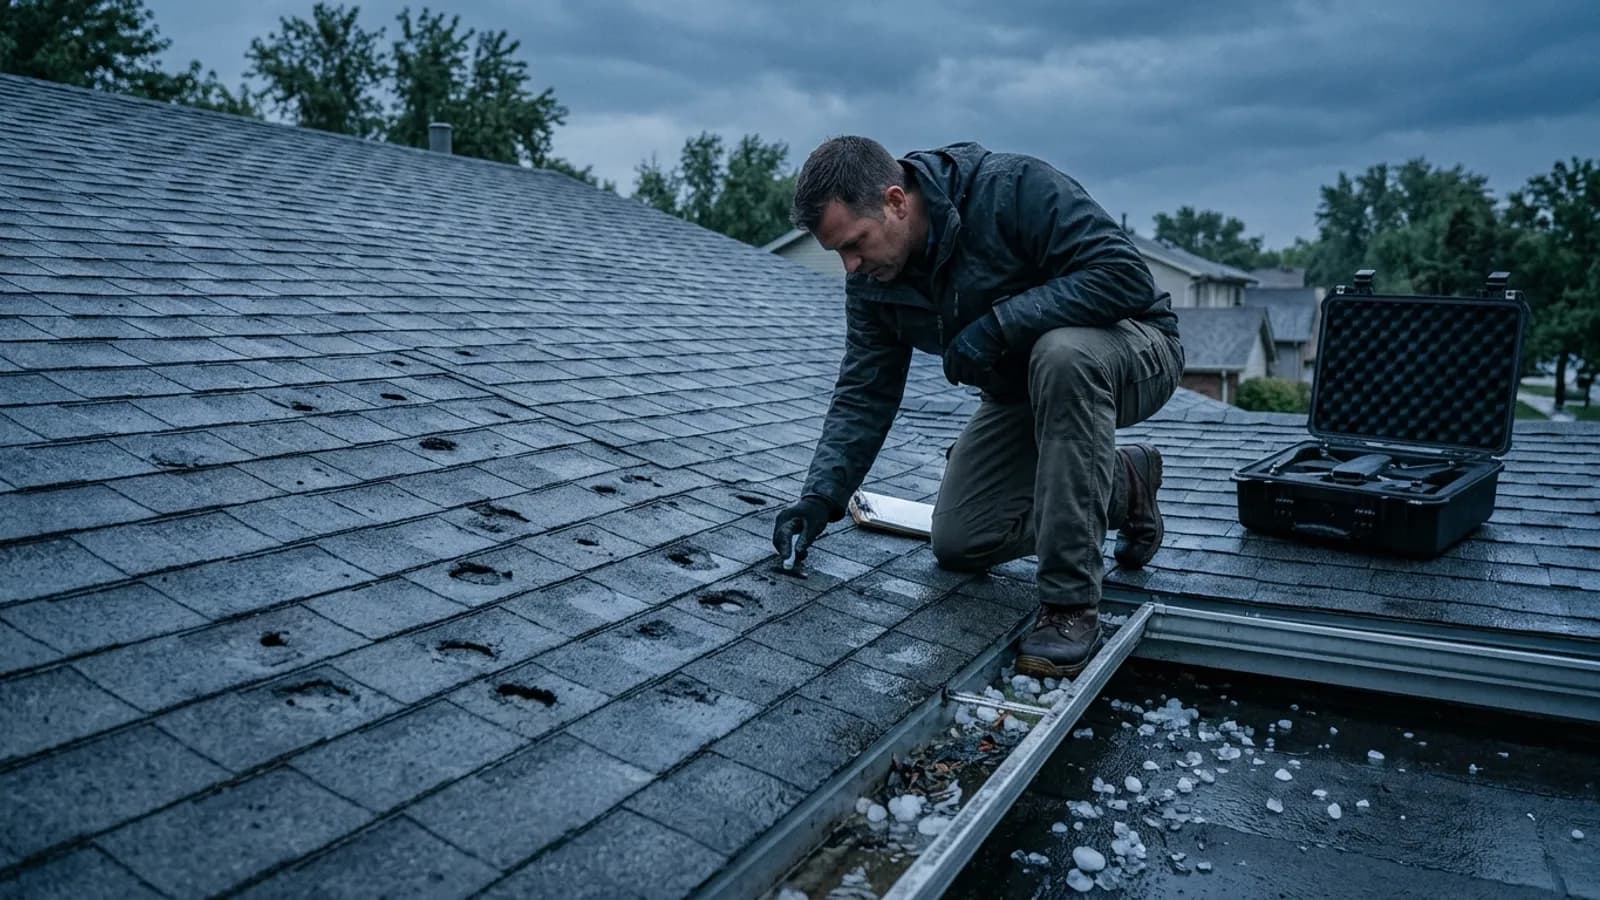
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance covers hail damage to roofs, siding, and contents, and hail-belt states price it with percentage wind/hail deductibles and ACV roof schedules.
Read guide
Flood Insurance: What It Covers, What It Costs, and Who Needs It
Flood insurance is never part of a standard home policy. Costs per year, the 30-day waiting period, NFIP limits, and why most claims come from outside flood zones.
Read guide
How to Choose the Best Home Insurance Company (No Sponsored Rankings)
Choose a home insurer on claims satisfaction, financial strength, coverage breadth, and state-market position — the criteria that replace sponsored rankings.
Read guideWhat Is a Deductible? (Insurance, Explained)
A deductible is what you pay out of pocket for covered losses before insurance pays — health resets it yearly; auto and home apply it per claim.
Read guide