
Glossary
What Is an At-Fault Accident?
An at-fault accident is a crash in which the driver bears legal responsibility — their bodily injury and property damage liability pay the other side, their collision pays their own car, and the claim surcharges their premium at renewal. Fault comes from police reports, adjuster investigations, and state negligence rules.
How it works
The fault determination decides whose insurance pays whom — and whose premium moves. Police report citations, scene evidence, and the adjusters' liability conversation produce the finding; in comparative-negligence states, comparative negligence rules split fault by percentage, and 20% fault means your carrier pays 20% of the other side's damages. The determination on the report is influential but not binding — carriers arbitrate disputes between themselves.
The pricing consequence: carriers surcharge at-fault claims commonly 20–40% for three years on the liability and collision portions, longer for severe events and DUI-tier violations. The claim populates your motor vehicle record and your claims history regardless of forgiveness or fault. Not-at-fault claims generally carry no surcharge — several states prohibit it outright — though the claim entry still appears.
Typical values
| Parameter | Typical value |
|---|---|
| Premium surcharge | Commonly 20–40% for three years |
| Record windows | MVR: 3–5 years; CLUE claim history: up to 7 years |
| Not-at-fault surcharge | 0–10% at most carriers; prohibited in some states |
| Small at-fault claims | Under about $1,000 — often worth paying out of pocket |
| Recovery | Surcharge declines annually and ages off; re-shop at each milestone |
At-fault vs not-at-fault accident
At fault: your bodily injury liability and property damage lines pay the other side, your collision pays your car, and the surcharge schedule fires. Not at fault: the other driver's liability pays you (or your collision pays and then subrogates), and most carriers apply no surcharge. One at-fault event can also be mitigated: accident forgiveness excludes a first at-fault accident from the rating at many carriers.
Worked example
An at-fault rear-end collision lands on a $1,450 per year premium. The renewal applies a 32% surcharge: $1,914. Year 2 drops about 8%, year 3 drops 12%, and year 4 the surcharge ages off — the re-shop at that milestone restores the $1,450 baseline. Skipping the milestone re-shops leaves the aging surcharge priced into every quote the market sees.
Related guides
The fault determination feeds a chain of records and coverages — the terms below decide what the crash actually costs.
- What Is Accident Forgiveness? — the feature that withholds a first at-fault surcharge.
- How Do Insurers Decide Fault After a Crash? — the percentage-fault mechanics behind the determination.
- What Is Bodily Injury Liability? — the line that pays the people you injure.
- What Is a Motor Vehicle Record (MVR)? — the driving record every carrier reads.
- What to Do After a Car Accident — the steps that shape fault and the claim.
Sources
Frequently asked questions
How much does an at-fault accident raise my insurance?
Carriers commonly apply a 20–40% surcharge for three years on the liability and collision portions, with wide carrier-to-carrier dispersion for the same event. Severe claims and DUI-tier events run higher. The exact number comes from each carrier's surcharge schedule — which is why the post-accident quote comparison is standard advice.
Does a not-at-fault accident affect my insurance?
The claim still posts to your record, but most carriers apply no surcharge or a light one for not-at-fault events. Exceptions exist: uninsured at-fault parties (your uninsured-motorist claim), high claim frequency, and some states allow surcharges regardless of fault. A violation attached to the crash matters more than the claim itself.
Related guides
What Is Accident Forgiveness?
Accident forgiveness is a feature that prevents your first at-fault accident from raising your premium — offered free to long-tenured customers or purchased as an add-on.
Read guideWhat Is Comparative Negligence?
Comparative negligence splits fault proportionally — a driver 20% responsible recovers 80% of damages. Five jurisdictions still bar recovery at any shared fault.
Read guideWhat Is Bodily Injury Liability?
Bodily injury liability pays the medical bills, lost wages, and legal claims of people you injure in an at-fault crash — written as paired limits, such as 100/300.
Read guideWhat Is a Motor Vehicle Record (MVR)?
A motor vehicle record (MVR) is the state DMV's driving history — license status, violations, at-fault accidents — that insurers pull at quote and renewal.
Read guideHow Long Do Claims Affect Insurance?
Claims history affects pricing for 3–7 years by line of business: auto claims 3–5 years, property claims 5–7 through CLUE, workers comp modifications about 3 years.
Read guide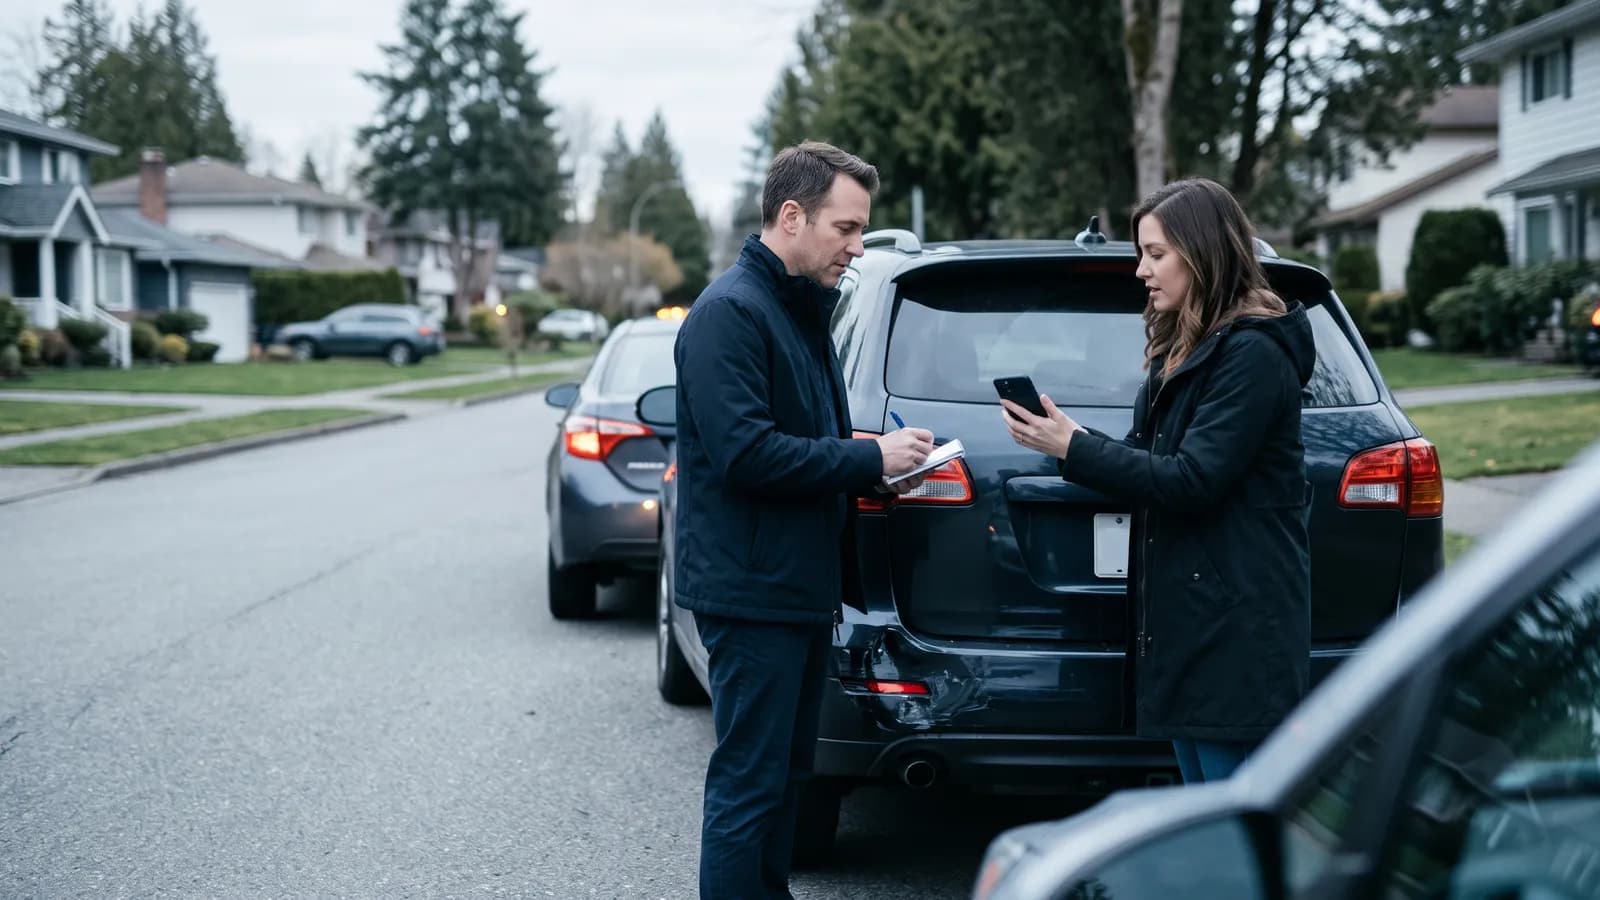
What to Do After a Car Accident: The 10-Step Claim Checklist
The post-accident sequence that protects your claim: scene safety, documentation, prompt insurer notice, the adjuster process, and the statements that cost money.
Read guide← Back to the full insurance glossary
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov Glossary — official ACA definitions for health-coverage terms.
- Insurance Information Institute (III) — property & casualty term definitions cross-checked against policy forms.
- NAIC consumer resources — regulator-authored guides and glossaries for each line of insurance.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.