
Travel Insurance for Brazil: Do You Need It and What It Costs (2026)
Travel insurance for Brazil is worth it: private hospitals treat visitors at international rates, dengue and traffic drive claims, and a policy costs 4–10% of trip.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
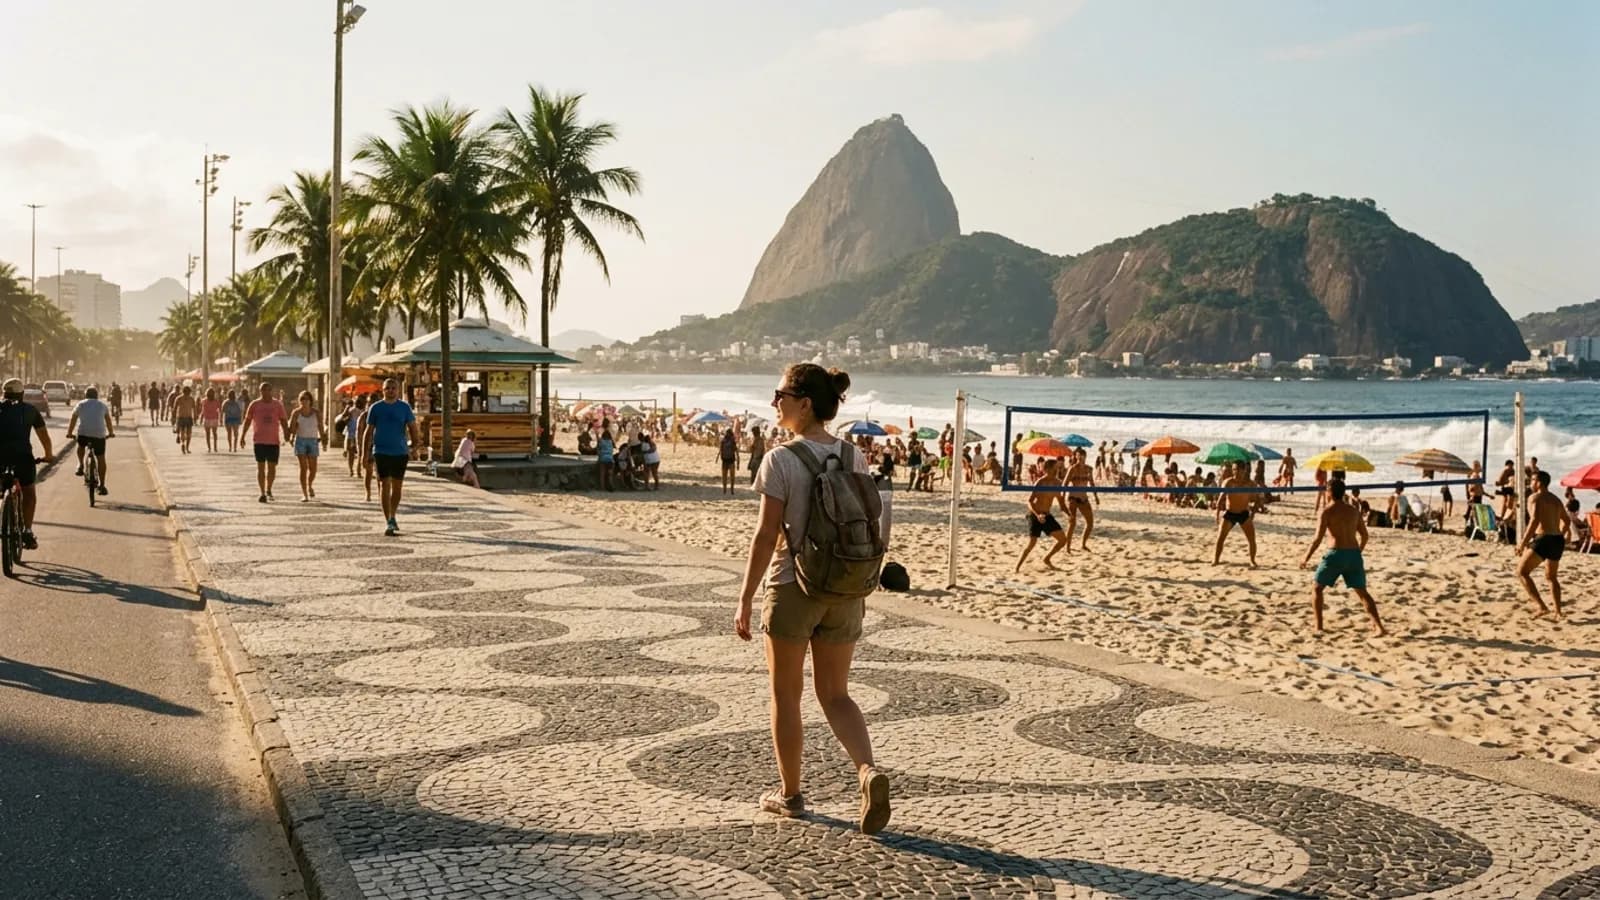
On this page
Yes — travel insurance for Brazil is worth buying. The public SUS system serves residents only, São Paulo and Rio private hospitals bill visitors at international rates, and dengue plus traffic accidents drive the claims.
Do you need travel insurance for Brazil?
US visitors apply for an eVisa, and Brazil checks no insurance at the border — the requirement is financial. Brazil's SUS public system is legally for residents, so foreign visitors are treated in the private system: Hospital Israelita Albert Einstein and Sírio-Libanês in São Paulo and Copa D'Or in Rio de Janeiro are international-standard and bill accordingly, often directly to the insurer when the assistance service arranges it. US health plans hold no Brazilian networks, and Medicare stops at the border. The claim mix is urban Brazil's own: dengue seasons spike fever hospitalizations in the December–March southern summer, traffic accidents rank among the world's highest by country, and Copacabana and Ipanema generate the theft claims. Interior travel — the Amazon and Pantanal — adds air-transfer exposure that a $250,000 evacuation limit exists to cover. Brazilian hospital groups are used to foreign patients, so the treatment itself is rarely the problem — payment mechanics and distance are.
What a Brazil policy must cover
| Coverage | Why it matters in Brazil | Target amount | | | --- | --- | | Emergency medical | Private hospitals (Albert Einstein, Sírio-Libanês, Copa D'Or) treat visitors at international rates; SUS is residents-only | $100,000+ | | Emergency medical evacuation | Amazon and Pantanal cases transfer by air to São Paulo or Manaus | $250,000+ | | Trip cancellation | Carnival-season Rio fares and Amazon lodge bookings are prepaid and non-refundable | 100% of prepaid, non-refundable costs | | Baggage and personal effects | Beach-theft and street-robbery claims run through personal-effects benefits | Per-item caps matched to what you carry |
Check how the trip cancellation coverage treats the bookings that define a Brazil trip — Carnival flights, Iguaçu tours, and Amazon lodges all cancel under strict penalty schedules.
What it costs for Brazil
Brazil policies price at 4–10% of prepaid trip cost: a $4,000 itinerary runs about $160–$400 per traveler. Costs climb with age, Amazon-region legs that need air-transfer coverage, and higher medical limits for the São Paulo private-hospital scenario. Cancel For Any Reason (CFAR) coverage adds roughly 50% to the premium and fits Carnival bookings made nearly a year ahead. Buy within 14–21 days of the first trip payment to preserve the pre-existing condition waiver and CFAR eligibility on most plans. Medical-only plans suit Rio-only city trips, but Amazon and Pantanal itineraries justify the full bundle's evacuation headroom.
Brazil-specific risks and exclusions
- Dengue fever seasons. Transmission peaks in the December–March southern summer; severe dengue means hospitalization, and the illness side of the policy — not the accident side — is what pays.
- Traffic accidents. Brazil ranks among the world's highest for road fatalities; city taxi and rideshare incidents plus coastal highway collisions produce the accident claims.
- Security incidents. Beach and street theft run through personal-effects benefits; claims need the boletim de ocorrência police report, and electronics sit under per-item caps.
- Beach and ocean claims. Rio's rip currents and surf injuries can fall under water-activity exclusion rider language — verify the marine clause before open-water swims.
- Interior evacuations. Amazon and Pantanal itineraries sit far from tertiary care; the $250,000 evacuation limit covers the fixed-wing transfer to a major city.
Filing a claim from Brazil
- Call the 24/7 assistance line before admission where possible — hospitalization and air transfers generally require pre-authorization.
- Let the assistance service arrange direct billing with Albert Einstein, Sírio-Libanês, or Copa D'Or; otherwise pay and keep every itemized receipt — the major groups' detailed accounts convert cleanly for reimbursement.
- File a boletim de ocorrência for any theft or traffic incident; Brazilian claims are denied without the police report.
- Photograph damaged baggage within the notification window and list items against the policy's per-item caps.
- Submit airline and lodge documentation for interruption claims before the policy deadline.
Related guides
Brazil anchors South America's Portuguese-speaking half of the circuit, and its neighbors repeat the private-hospital-plus-regional-transfer structure this page prices.
- Travel Insurance for Argentina — Buenos Aires private care and Patagonia evacuation exposure.
- Travel Insurance for Colombia — Medellín and Bogotá hospitals with a nomad-visa coverage mandate.
- Cancel For Any Reason (CFAR) Coverage: How It Works and When It's Worth 50% More — refundability for Carnival-season bookings.
- Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements — renewable coverage for extended Brazil stays.
- Travel Insurance: The Complete Guide — the coverage framework applied to Brazil.
Travel insurance for other destinations in the region
Planning a multi-country trip? The regional guides carry entry rules and medical realities per destination:
Sources
Frequently asked questions
Do I need travel insurance for Brazil?
Yes. US visitors need an eVisa, and no insurance mandate applies at entry, but Brazil's public SUS system serves residents only — visitors are treated in the private system, where São Paulo and Rio hospitals bill at international rates. Dengue fever seasons, urban traffic, and beach-adjacent theft drive the claim mix that a policy needs to cover.
How much medical and evacuation coverage do I need for Brazil?
Carry $100,000 or more in emergency medical benefits and $250,000 or more in emergency medical evacuation coverage. São Paulo's Albert Einstein and Sírio-Libanês hospitals and Rio's Copa D'Or deliver international-standard care, but they bill visitors accordingly. Serious cases from the Amazon, Pantanal, or interior regions transfer by air to the major cities.
Does my U.S. health insurance work in Brazil?
Not practically. US plans have no Brazilian provider networks, Medicare and Medicaid stop at the border, and the SUS public system is legally reserved for residents. Brazilian private hospitals often bill insurers directly when the assistance service arranges it, which makes a policy with a 24/7 assistance line more useful than pay-first-and-reimburse coverage.
What does travel insurance for Brazil cost?
Plan on roughly 4–10% of your prepaid trip cost. A $4,000 Brazil itinerary prices a comprehensive policy at about $160–$400 per traveler. Carnival-season and Rio-peak bookings, Amazon or Pantanal legs with air-transfer exposure, and Cancel For Any Reason (CFAR) coverage — about 50% more in premium — push costs toward the top of the range.
Is dengue fever covered by travel insurance in Brazil?
Yes, dengue is covered as illness. Brazil's transmission peaks in the southern summer months of December through March, and severe cases need hospitalization for hydration and monitoring. Travelers who avoid mosquito exposure reduce the risk, but a policy sized at $100,000 or more in medical benefits covers the hospitalization scenario when prevention fails.
Are theft and robbery losses covered in Brazil?
Baggage and personal-effects benefits cover theft from your person or lodging, and some plans add street-robbery provisions. Brazilian claims require a boletim de ocorrência — the police report filed at a delegacia or online — within the policy's notification window. Electronics and jewelry sit under per-item caps, so check the limits before carrying them.
How we researched this guide
Travel insurance pays on documented triggers, so our guides focus on what activates each benefit and what documentation the claim needs.
- Coverage triggers (trip cancellation reasons, medical evacuation standards, pre-existing waivers) are verified against policy wordings and the state DOI consumer guides that regulate them.
- Visa-entry insurance requirements (e.g., Schengen) are checked against U.S. State Department country guidance.
- Air-passenger rights cited in delay/cancellation guides come from U.S. DOT consumer rules, not airline policies.
- Destination health-risk context comes from CDC traveler health notices.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- U.S. State Department — travel — country conditions, visa insurance requirements, and emergency assistance programs.
- CDC — traveler health — destination health risks and vaccination requirements that affect medical coverage.
- U.S. DOT — Aviation Consumer Protection — airline passenger rules on cancellations, delays, and refunds.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Travel Insurance: The Complete Guide
Travel insurance reimburses prepaid trip costs after covered cancellations and pays medical bills abroad — how policies work, what they cost, and when they pay.
Read guide
Travel Insurance for Argentina: Do You Need It and What It Costs (2026)
Travel insurance for Argentina is worth it: Buenos Aires hospitals bill visitors and Patagonia evacuations run six figures. Budget 4–10% of trip cost for a policy.
Read guide
Travel Insurance for Colombia: Do You Need It and What It Costs (2026)
Travel insurance for Colombia is worth it: Medellín and Bogotá hospitals bill visitors, the nomad visa mandates coverage, and a policy costs 4–10% of trip.
Read guide
Cancel For Any Reason (CFAR) Coverage: How It Works and When It's Worth 50% More
Cancel For Any Reason (CFAR) coverage reimburses 50–75% of prepaid trip costs on a cancellation for any reason at all — for a 40–50% premium and four strict rules.
Read guide
Travel Medical Insurance: Long Trips, Digital Nomads, and Visa Requirements
Travel medical insurance pays for treatment and evacuation abroad — no trip-cancellation benefits — the product for long stays, nomads, and Schengen visa rules.
Read guide