
Car Insurance in New Jersey: Minimums, Costs, and How to Save (2026)
Car insurance in New Jersey costs $2,000–$3,200 per year for full coverage, priced for the nation's densest traffic, mandatory PIP, and a thin Basic-policy minimum.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.

On this page
Car insurance in New Jersey costs about $2,000–$3,200 per year for full coverage. The nation's densest traffic, mandatory PIP, and coastal flood exposure put New Jersey well above the national middle, and Newark and the Hudson Waterfront price highest of all. The state is also a choice no-fault market with a famously thin Basic policy.
What New Jersey drivers pay
A clean-record New Jersey driver pays $2,000–$3,200 per year for full coverage, and garaging city moves the number more than in most states.
| Driver profile | Typical annual cost |
|---|---|
| Full coverage, clean record, statewide | $2,000–$3,200 |
| Newark | $2,400–$3,800 |
| Jersey City and the Hudson Waterfront | Near Newark's range |
| Basic policy (minimum legal) | Roughly 30–40% of the full-coverage figure |
| One at-fault crash on the record | +25–50% |
| Teen driver added to the household | +$2,000–$5,000 per year |
Territorial rating is intense in New Jersey: the same driver can pay hundreds less per year by garaging in a suburban or South Jersey ZIP instead of an urban corridor. The average cost of car insurance guide shows where New Jersey's range sits nationally.
What New Jersey law requires
The New Jersey Department of Banking and Insurance (DOBI) regulates auto coverage, and the state's structure has three moving parts no other state combines the same way.
- Standard policy liability minimum: $35,000/$70,000/$25,000 as of January 1, 2026. The minimum rose in steps — from the long-standing 15/30/5 to 25/50/5 in 2021, then property damage to $25,000 in 2023, then to the current limits — with insurers directed by DOBI Bulletin 25-06.
- PIP, mandatory. New Jersey is a no-fault state: personal injury protection defaults to $15,000 of medical coverage per person, with purchase options up to $250,000.
- Right-to-sue choice. Standard policies pick limited or unlimited tort; the limited (verbal-threshold) option restricts pain-and-suffering lawsuits to serious injuries in exchange for a lower premium.
- UM/UIM, included on Standard policies. Minimum uninsured/underinsured motorist limits rise with the new liability minimums.
- Basic policy, the alternative. About $15,000 of PIP and $25,000 of property damage, with no bodily-injury liability unless a $10,000 option is added and no UM/UIM at all.
The New Jersey claim landscape
Density, water, and the no-fault system define New Jersey's claim pattern.
- Congestion crashes — the New Jersey Turnpike, Garden State Parkway, and Newark/Jersey City corridors pack the country's highest traffic density, so rear-end and multi-car claims are the baseline loss.
- Coastal and inland flooding — Superstorm Sandy (2012) and the remnants of Hurricane Ida (2021) drowned vehicles from the Shore to Newark; comprehensive is the only line that pays flood damage.
- No-fault PIP intensity — New Jersey's PIP system historically attracted staged-accident fraud rings in North Jersey, and carriers price that history into the state's medical-coverage costs.
- Auto theft — urban cores in northeast New Jersey post some of the nation's highest vehicle-theft rates; comprehensive pays the theft claim.
- Deer in the suburbs — New Jersey's deer population collides with commuters on suburban routes every autumn; the strike itself is a comprehensive claim.
Coverage setup that fits New Jersey
A New Jersey policy starts with the Standard-versus-Basic decision, then tunes PIP and the lawsuit right.
- Choose the Standard policy if you own anything — the Basic policy's missing liability and UM/UIM turn one injury crash into personal debt.
- Liability at 100/300/100 — the new 35/70/25 minimums still trail a multi-claimant Turnpike crash.
- Tune PIP deliberately — raise the medical limit if your health plan is thin; a higher PIP deductible trades premium for out-of-pocket risk.
- Pick the lawsuit right knowingly — limited tort saves premium on a Standard policy, but it narrows recovery for pain and suffering to serious injuries.
- Comprehensive is non-negotiable near the water — Sandy-scale flooding and urban theft both pay through comprehensive.
- Re-shop annually — territorial rating and carrier dispersion mean the how to lower car insurance checklist produces real money in New Jersey, and the full coverage decision sets sensible comp/collision deductibles.
New Jersey's Basic policy and the right-to-sue choice
New Jersey is a choice no-fault state, and the two decisions that shape every quote are the policy type and the lawsuit right. The Basic policy exists as a budget lifeline: about $15,000 of PIP and $25,000 of property damage, with no bodily-injury liability unless the optional $10,000 is purchased and no uninsured-motorist protection at all. It fits a narrow profile — a low-asset driver who accepts personal exposure — and it is priced far below the Standard policy. On the Standard side, the limited-versus-unlimited right-to-sue choice is New Jersey's version of tort: limited tort (the verbal threshold) restricts pain-and-suffering lawsuits to serious or permanent injuries and discounts the premium, while unlimited tort preserves full lawsuit rights. Medical bills flow through PIP either way. The cost-effective setup for most New Jersey drivers is the Standard policy with 100/300/100 liability, a deliberately chosen PIP configuration, and limited tort only when health coverage is strong.
What New Jersey's minimums actually pay in a real crash
Work a common New Jersey scenario: a multi-vehicle Turnpike crash with two injured occupants ($85,000 in combined medical bills) and $32,000 of vehicle damage.
| Coverage line | New Jersey minimum pays | 100/300/100 pays |
|---|---|---|
| Bodily injury, per person | up to $35,000 each | up to $100,000 each |
| Bodily injury, per accident | capped at $70,000 total | capped at $300,000 total |
| Property damage | capped at $25,000 | capped at $100,000 |
New Jersey's $35,000/$70,000/$25,000 minimums — effective January 1, 2026 — are the strongest the state has had, and PIP pays the medical layer first under no-fault regardless of who caused the crash. Even so, a Turnpike multi-vehicle crash with hospital transports outruns a $70,000 per-accident cap quickly, and the at-fault driver owes everything above it personally — wage garnishment and asset exposure follow. Property damage above $25,000 is also personal. At 100/300/100, the same crash is a claims event, not a lawsuit — and on a Basic policy, none of the liability column exists at all, which is the gap the Standard-versus-Basic choice is really about.
Related guides
New Jersey's density and no-fault rules connect it to New York and Pennsylvania, and the flood guide covers the state's signature catastrophic loss.
- Car Insurance: The Complete Guide — how every coverage line works before you set limits.
- Car Insurance in Newark, NJ — the state's priciest metro; $2,400–$3,800 per year for full coverage.
- Car Insurance in New York — the other high-density no-fault state across the Hudson; $2,200–$3,500 per year.
- Car Insurance in Pennsylvania — the choice-no-fault neighbor with limited tort; $1,500–$2,300 per year.
- Does Car Insurance Cover Flood Damage? — what Sandy- and Ida-scale flooding does to liability-only policies.
Compare car insurance in other states
Requirements and rate bands move at the state line:
-
Free Car Insurance Quotes: Compare Rates by State (2026) — the 35/70/25 Standard-policy floor and what a New Jersey quote includes.
Sources
Frequently asked questions
How much does car insurance cost in New Jersey per year?
Full coverage in New Jersey runs about $2,000–$3,200 per year for a clean-record driver, well above the national middle. Newark and the Hudson Waterfront price highest — Newark full coverage averages roughly $2,400–$3,800 per year — while suburban and South Jersey towns sit lower.
What are New Jersey's minimum car insurance requirements in 2026?
On a Standard policy, New Jersey requires $35,000/$70,000/$25,000 in liability as of January 1, 2026 — the latest step in increases that started from the long-standing 15/30/5. PIP medical coverage is mandatory, and uninsured/underinsured motorist coverage rides with the Standard policy.
Is car insurance required in New Jersey?
Yes, but New Jersey lets you choose the policy. The Standard policy carries full liability, PIP, and UM/UIM; the Basic policy is the cheapest legal option — about $15,000 of PIP and $25,000 of property damage with no bodily-injury liability unless you add $10,000.
What is limited tort versus full tort in New Jersey?
On a Standard policy you pick your right to sue. Limited tort (the verbal threshold) costs less but restricts lawsuits for pain and suffering to serious or permanent injuries; unlimited tort preserves full lawsuit rights for a higher premium. The choice does not affect how medical bills are paid — PIP pays those regardless.
How does New Jersey PIP work after a crash?
New Jersey is a no-fault state: your own personal injury protection pays medical bills first, regardless of who caused the crash. The Standard policy defaults to $15,000 of PIP with options up to $250,000, and your deductible and co-pay choices move the premium more than most drivers expect.
Is the Basic policy a good idea in New Jersey?
It is the cheapest legal coverage in New Jersey, and it fits drivers with no assets and no dependents counting on them. It omits bodily-injury liability beyond an optional $10,000, and it cannot include UM/UIM — so an injury caused by an uninsured driver or by you lands on personal funds.
How we researched this guide
Car insurance pricing is set per driver, per ZIP code — so our guides anchor on regulator and industry statistics and explain the factors, not a fake exact price.
- Premium ranges are anchored to NAIC statewide average-expenditure data, the most complete public dataset on what drivers actually pay per state.
- State minimum-coverage requirements are checked against each state's motor-vehicle financial-responsibility statute and the state insurance department's consumer pages.
- What a coverage actually pays for is verified against policy declarations and specimen forms, not marketing copy.
- Discount and surcharge rules cite the state DOI consumer bulletin where each state regulates them differently — for example credit-based insurance scores, which most states permit but a few ban.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 16, 2026.
- IIHS — Insurance Institute for Highway Safety — crash-test data, vehicle loss statistics, and safety-feature research.
- NHTSA — National Highway Traffic Safety Administration — recalls, crash data, and state traffic-safety requirements.
- FMCSA — Federal Motor Carrier Safety Administration — commercial vehicle and carrier insurance requirements.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Car Insurance: The Complete Guide
Car insurance bundles liability, collision, comprehensive, and medical coverage — this guide explains state minimums, full coverage, and how to lower the premium.
Read guideFree Car Insurance Quotes: Compare Rates by State (2026)
Free car insurance quotes explained — what drivers pay by state and age in November 2026, the information insurers request, and how to compare quotes fairly.
Read guideCar Insurance in Newark, NJ: Costs and Guide (2026)
Car insurance in Newark costs about $2,400–$3,800 per year, with dense urban claims, PIP-heavy no-fault rules, and prices above the surrounding Jersey suburbs.
Read guideCar Insurance in New York: Minimums, Costs, and How to Save (2026)
Car insurance in New York costs $2,200–$3,500 per year for full coverage, priced for the $50,000 PIP mandate and New York City density.
Read guideCar Insurance in Pennsylvania: Minimums, Costs, and How to Save (2026)
Car insurance in Pennsylvania costs $1,500–$2,300 per year for full coverage — a choice no-fault state where the full-vs-limited tort pick moves the price most.
Read guide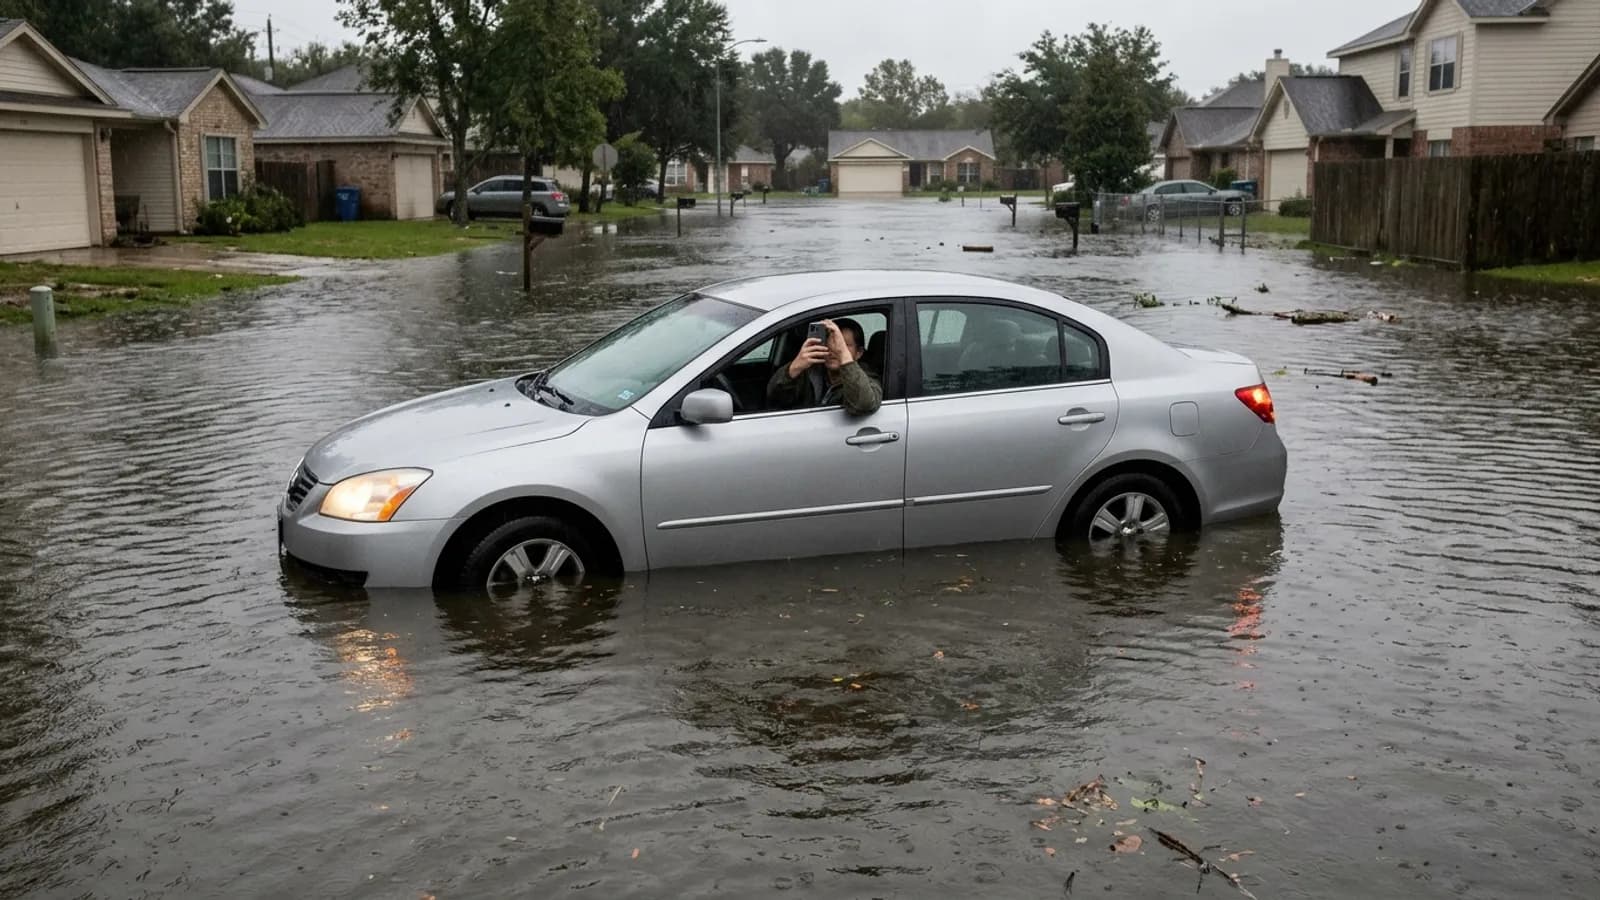
Does Car Insurance Cover Flood Damage?
Flood damage claims under comprehensive coverage — hydro-locked engines, flooded interiors, storm surge — and liability-only policies pay none of it.
Read guide