
E-commerce Insurance: Coverage for Online Sellers
E-commerce insurance is product-liability-first: goods sold create the claims, inventory is the asset, and customer data is the cyber exposure — $80–$400 per month.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
E-commerce insurance is product-liability-first: the goods you sell create the claims, the inventory is the asset, and the customer data is the cyber exposure. Amazon and other marketplaces add platform mandates on top, and small sellers commonly pay $80–$400 per month for the stack.
The e-commerce stack
| Policy | Covers | Typical monthly cost |
|---|---|---|
| General liability / product liability | Injuries and damage from products sold | $40–$100 |
| Inventory / property | Stock at home, warehouse, 3PL | $30–$150 |
| Cyber | Customer payment data, site breaches | $50–$150 |
| Business income | Interruption coverage | BOP component |
The products claim — that an item you sold injured someone — is products liability coverage riding inside the general liability form; the underlying mechanics are the general liability rules with the products-completed-operations aggregate doing the heavy lifting.
| Scale | Typical monthly cost |
|---|---|
| Side-hustle Etsy or craft seller | $40–$100 |
| Established Shopify store | $100–$250 |
| Amazon FBA with regulated products | $150–$400 |
The inventory location map: 3PL, garage, and in between
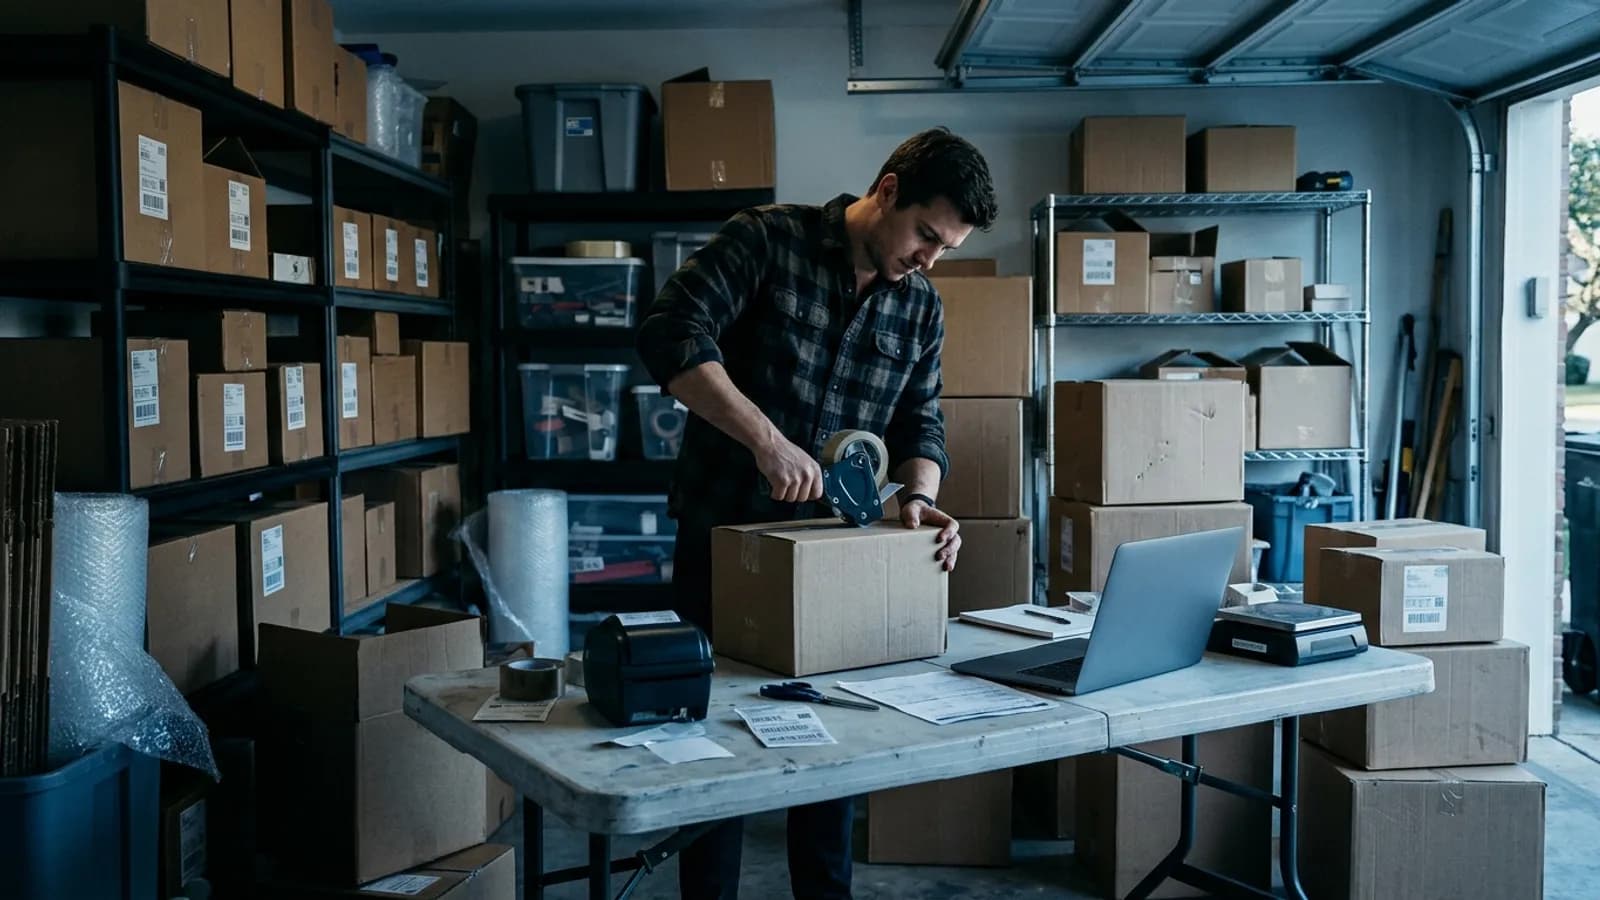
E-commerce property exposure is wherever the boxes are, and the boxes are rarely in one place. Inventory in your garage sits under a homeowners policy that excludes business property — the endorsement-versus-business-policy decision for home-stored stock is the core of the home business checklist. In a warehouse you lease, the stock sits under your BOP or a commercial property policy. In a 3PL's facility, it sits under a contract question — many fulfillment agreements make the 3PL responsible (their bailee coverage) for loss in their care, others disclaim it and leave the gap to you. Read the 3PL contract's loss section before assuming. Each location the stock occupies should be listed or covered by someone's policy in writing; sellers discover their inventory map the same week they discover which location was uninsured.
Product liability across borders: the importer's position
Selling a product makes you its seller of record; importing or private-labeling it makes you, in product-liability practice, functionally its manufacturer. Claims for a defective widget — the cracked housing, the failing charger, the small part a child swallowed — name the seller first because the seller is findable and insured, then work back toward the factory. A supplier's certificate or a "quality agreement" does not transfer your liability to them; it creates only a contractual claim you pursue afterward. The underwriting questions follow: country of manufacture, whether you or the supplier engineered the product, testing documentation (UL, CE, or equivalent as applicable), and recall procedures.
The Amazon seller specifics
- Amazon requires $1 million product-liability coverage from sellers whose monthly proceeds exceed $10,000 in any month, verified by certificate.
- The A-to-Z claims run through the platform; your general liability answers the underlying liability claims.
- FBA inventory at Amazon warehouses needs coverage clarification — Amazon's liability terms for stored goods are limited, and the gap lands on your property line or the 3PL contract.
What a $500k-revenue online store pays
A direct-to-consumer store at roughly $500,000 annual revenue, product-weighted (consumer goods, overseas manufacturing), commonly budgets $1,500–$4,000 per year ($125–$335 per month) for general liability with products coverage at $1M/$2M, scaling with product category — children's products, consumables, and electrical goods price above housewares. Add property and inland marine for inventory locations at $300–$1,000 per year ($25–$85 per month), and cyber at $500–$2,000 per year ($40–$170 per month) — payment-card data is the exposure, and the policy design is in the cyber insurance guide. Commercial auto enters only where owned vehicles exist. Low-weight digital-goods sellers strip the property line and add media liability instead. The number that should not be low is the products limit: one injury claim against an uninsured product line erases years of margin.
When the platform audits your insurance
Marketplaces verify seller insurance on a schedule, not just at signup: periodic re-verification, certificates checked for expiry, limits matched to the requirement, and sellers who lapse suspended from payouts until current. The verification services platforms use read the certificate of insurance literally — the named insured must be the selling entity, the limits must meet the threshold, the policy must be active. Three habits keep the loop painless: bind coverage to the entity that sells, not the owner personally (the naming rules are in the LLC insurance guide); set the renewal date ahead of the platform's expiry alert; and keep the certificate file matching what the platform's dashboard shows. The design-and-advice layer some sellers add — media liability and errors and omissions (E&O) — follows the same claims-made rules as the E&O guide.
Related guides
The online-seller stack connects to the data, entity, and cost pages around it:
- Freelancer Insurance — the solo-seller entry stack before inventory scales.
- BOP Insurance — the bundle that carries the business-income line.
- How Much Is Business Insurance? — costs by policy and business type.
- Business Insurance: The Complete Guide — the full small-business coverage map.
Sources
Frequently asked questions
What insurance does an e-commerce business need?
The stack: product liability (general liability covering the products sold), inventory and business property coverage, cyber for customer payment data, and shipping-adjacent coverage. Amazon sellers face additional platform mandates — $1 million liability proof for sellers above the platform's revenue threshold.
How much is e-commerce insurance?
Small sellers commonly pay $80–$300 per month for the stack: general liability at $40–$100 per month, inventory coverage priced by stock value, and cyber at $50–$150 per month. Product category drives pricing — electronics, children's products, and supplements price higher than housewares.
Does homeowners insurance cover an e-commerce business?
No — inventory, product liability, and business income are excluded from personal policies, and homeowners forms sublimit business property to a few hundred or few thousand dollars. Home-stored inventory needs business coverage; the endorsement-versus-policy decision is the home business checklist's core question.
Does e-commerce insurance cover inventory in transit?
Only through inland marine or cargo coverage, which follows goods between locations — and whose terms depend on shipping terms (who owns the goods mid-journey). Ocean and air freight, parcel shipments, and domestic trucking each carry different cover structures. List your shipping lanes with the carrier; transit is where inventory maps silently go uninsured.
What insurance does a print-on-demand shop need?
The same seller-of-record stack as physical goods — general liability with products coverage, since you sell the item even though someone else prints it — plus media liability or E&O for the design layer: copyright and trademark claims over uploaded artwork are the print-on-demand claim that actually fires. Verify your print partner's contract does not silently assign design liability to you.
Does business insurance cover chargebacks and fraud losses?
Generally no — chargebacks from buyer disputes, friendly fraud, and payment fraud are financial losses most policies exclude; crime coverage addresses employee theft, not customer fraud. Payment-processor fraud tools and platform seller protections are the operational answer. Cyber policies sometimes add funds-transfer-fraud coverage for social-engineering scams — price it as a sublimit, not an assumption.
How we researched this guide
Business insurance requirements are mostly statutory — workers comp is state law — so our guides separate legal requirements from prudent coverage.
- Workers-comp rules (who must carry, exemptions, monopolistic states) are verified against state statutes and NCCI classifications.
- General liability and BOP coverage mechanics are verified against standard policy forms and SBA guidance.
- Professional-liability explanations distinguish the claims-made trigger and tail options, because that's where businesses get caught.
- Industry examples use realistic claim scenarios published by insurers and courts, and we label estimates as estimates.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- U.S. Small Business Administration (SBA) — which policies a business legally needs and how to buy them.
- OSHA — Occupational Safety and Health Administration — workplace safety rules that drive workers-compensation obligations.
- NCCI — National Council on Compensation Insurance — workers-comp class codes and rate filings used in most states.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Business Insurance: The Complete Guide
Business insurance explained: the general liability, BOP, workers comp, E&O, and commercial auto policies a small business needs — and what each costs per month.
Read guide
What Is General Liability Insurance? Coverage and Costs
General liability insurance pays third-party injury and property damage claims; small businesses pay $40–$100 per month for the standard $1M/$2M limits.
Read guide
Cyber Insurance for Small Business: What It Covers and What It Costs
Cyber insurance pays breach response, ransomware downtime, and liability for leaked client data; small businesses pay $500–$2,500 per year for $250k–$1M limits.
Read guide
LLC Insurance: What Coverage Your Company Actually Needs
LLC insurance covers what the liability shield does not — your own negligence, uninsured claims — starting at $40–$100 per month for general liability.
Read guideWhat Is Products Liability Coverage?
Products liability covers injury and damage claims caused by products you make, sell, or distribute — built into general liability for small businesses.
Read guide