
What Is COBRA Insurance and How Does It Work?
COBRA lets you keep your employer health plan after job loss by paying the full premium plus up to 2% — the 18-month rules, the 60-day window, and when the ACA wins.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
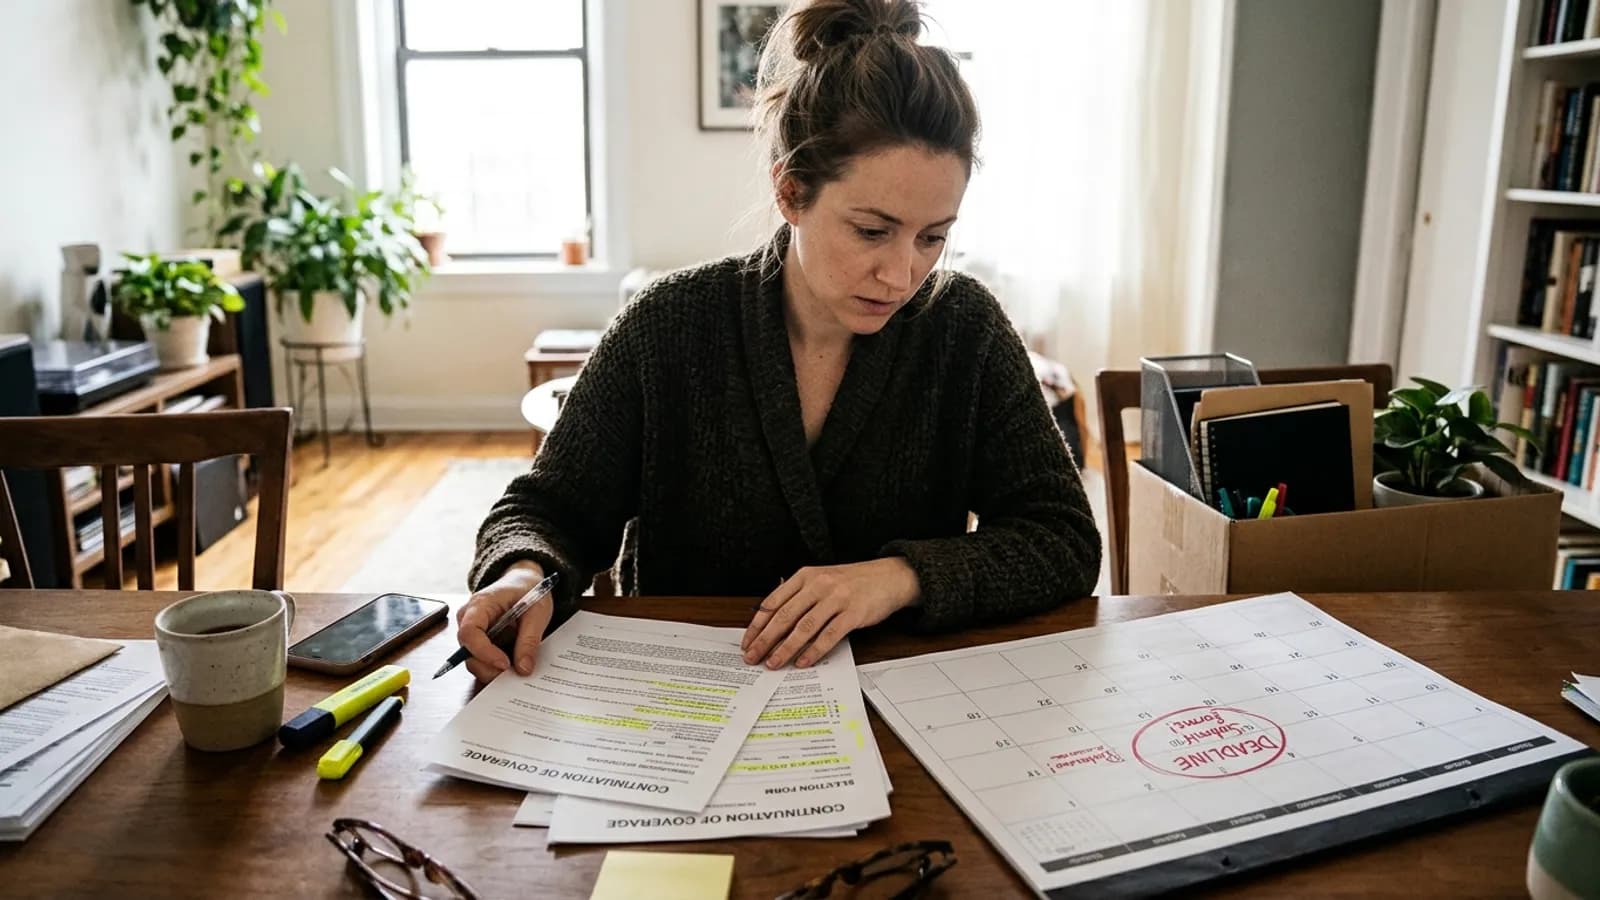
COBRA — the Consolidated Omnibus Budget Reconciliation Act — is the federal right to keep your employer's health plan after a qualifying event, usually losing your job, by paying the entire premium yourself, typically for 18 months. Same doctors, same plan, same cards; new price tag: the full premium plus up to 2%, which for family coverage commonly runs $1,800–$2,500 per month.
The mechanics
- Qualifying event: job loss (other than gross misconduct), reduced hours below eligibility, divorce from the covered employee, death of the employee, Medicare entitlement of the employee, or a child aging out. Losing job-based coverage is a classic qualifying life event for other coverage too. Employers with 20+ employees are covered (state "mini-COBRA" laws cover smaller employers, often 18+ months).
- Duration: 18 months standard for job loss/hours reduction; 29 or 36 months for certain events (disability extension, divorce, death, Medicare entitlement).
- Election window: you have at least 60 days from the election notice (or coverage loss, if later) to elect, plus 45 days after electing to make the first payment.
- Retroactive coverage: once elected and paid, coverage dates back to the loss date — doctor visits during the decision window can be claimed retroactively.
- Price: full premium + up to 2% administrative fee, with no employer subsidy.
What COBRA costs
| Plan | Typical COBRA monthly cost |
|---|---|
| Single coverage | ~$700–$1,000 |
| Family coverage | ~$1,800–$2,500 |
KFF employer survey averages put total family premiums above $2,000 per month; COBRA adds the 2% fee on top.
COBRA vs ACA marketplace — the decision that matters
| Factor | COBRA | ACA marketplace |
|---|---|---|
| Monthly cost | Full premium, no subsidies | Premium tax credits often slash the price |
| Networks/doctors | Unchanged | New network — check your doctors |
| Deductible progress | Kept (same plan year) | Resets |
| Timing | Enroll within 60 days, retroactive | Special enrollment: 60 days from losing coverage |
| Best for | Met deductible/OOP max; ongoing treatment; continuity | Everyone else, especially lower incomes |
The rule of thumb: if you haven't met your deductible, the marketplace usually wins on price. Losing job-based coverage opens a 60-day special enrollment window on HealthCare.gov or your state exchange, and premium tax credits are income-based, not job-based — a zero-income job-loss month can make marketplace coverage nearly free. The health insurance hub maps the full set of options that open up at job loss.
The COBRA-as-safety-net trick
Because election is retroactive and the window is 60+ days, a practical sequence exists:
- Lose coverage → immediately apply on the marketplace (special enrollment) with a start date.
- If care is needed during the gap, elect COBRA retroactively — it covers those dates.
- Drop COBRA once marketplace coverage starts (no penalty for electing and later declining).
You're never forced to choose blind: COBRA functions as a 60-day option while the marketplace application processes.
Who qualifies beyond the employee
The covered events reach past job loss: reduction of hours below the plan's eligibility floor (the underemployed spouse's event), divorce or legal separation (the ex-spouse's own 36-month window), death of the employee (surviving dependents), Medicare entitlement of the employee (ending the dependents' coverage), and a child's aging out. Each qualifying person elects independently with their own maximum period — 18 months for the employee's events, 36 months for the divorce/disability extensions. The often-missed move: a divorced spouse electing COBRA keeps the identical plan at the employer's group rate — materially cheaper than individual-market pricing for the same benefits, and often the best-priced 36 months of coverage available.
The small-employer and state-continuation exceptions
COBRA applies to employers with 20+ employees; smaller groups fall to state continuation laws — many states require mini-COBRA from employers down to 2–19 employees, with state-set periods (commonly 9–18 months) and sometimes higher premiums. Two more edges: churches and federal government plans follow their own rules, and retiree coverage sometimes runs longer under retiree-health provisions. The verification move after a qualifying event: ask the employer's benefits office two questions — "are we COBRA-eligible or state-continuation?" and "what is the exact maximum period and monthly cost for my tier?" The answers shape the COBRA-vs-marketplace arithmetic that follows.
COBRA mistakes to avoid
- Assuming it's the only option — marketplace subsidies routinely undercut it by hundreds per month.
- Electing too early — pay-as-needed using the retroactive window; don't prepay months you didn't use.
- Ignoring state mini-COBRA — small-employer (under 20) workers have state continuation rights instead.
- Forgetting HSA/FSA details — FSAs generally stop at the qualifying event; HSAs continue if you remain HDHP-eligible.
- Double coverage — electing COBRA while a marketplace plan is active wastes a month of premium.
Related guides
COBRA is one branch of the job-loss coverage decision — these pages cover the marketplace alternative and the glossary terms behind the mechanics.
- Supplemental Insurance: The Complete Guide — the hub: where continuation coverage sits in the stack.
- What Is COBRA Coverage? — the glossary definition of the continuation right.
- What Is a Special Enrollment Period? — the marketplace window that opens at job loss.
- How to Choose the Best Health Insurance Company — evaluating the plans that compete with COBRA.
- What Is an HSA? — the account whose eligibility continues through COBRA.
Sources
Frequently asked questions
What is COBRA insurance?
COBRA — the Consolidated Omnibus Budget Reconciliation Act — is a federal law letting you continue your employer's group health plan after a qualifying event (usually job loss or reduced hours) for typically 18 months. You pay the full premium yourself: what you used to pay plus your employer's share, plus up to a 2% administrative fee. Coverage is identical to what you had as an employee.
How much does COBRA cost?
The average employer family plan costs over $2,000 per month in total premiums, and COBRA makes you pay all of it plus a 2% fee — commonly $1,800–$2,500 per month for family coverage and $700–$1,000 per month for single coverage. Employers no longer subsidize any of it.
When is COBRA better than ACA marketplace coverage?
COBRA wins when you've already met your deductible and out-of-pocket maximum this year (marketplace plans restart those), when you need immediate coverage for ongoing treatment without network disruption, or when marketplace subsidies don't apply to your situation. For everyone else, marketplace plans with premium tax credits are usually far cheaper.
How long do I have to elect COBRA?
You have at least 60 days from receiving the election notice (or from losing coverage, whichever is later) to elect, and then 45 days to pay. Coverage retroactively applies to the loss date once elected and paid — so you can effectively 'look back' and elect COBRA only if you needed it during that window. This makes COBRA a free 60-day safety net while you arrange marketplace coverage.
Can I cancel COBRA early once a new job's coverage starts?
Yes — COBRA cancels on request with no penalty, and new employer coverage takes over on its effective date. Watch one gap: don't cancel COBRA effective the day before the new plan starts (a one-day uninsured gap can complicate later special enrollments). The standard sequence: new coverage first, then cancel COBRA effective the same or next day.
Is COBRA available from employers with fewer than 20 employees?
Federal COBRA no — but many states require continuation coverage from smaller employers (down to 2–19 employees under various state mini-COBRA laws), with state-set periods and premium rules. Check the state insurance department's continuation page after a qualifying event at a small employer; the rules and deadlines differ from federal COBRA's.
How we researched this guide
Supplemental policies are gap-fillers, so our guides define the gap first — what the primary coverage already pays — then judge the add-on honestly.
- Disability guides are framed against SSA's actual SSDI/SSI eligibility and payment rules, so readers see what federal benefits already cover.
- Employer voluntary-benefit rules follow Department of Labor (EBSA) regulations on enrollment and ERISA protections.
- Medigap content follows the standardized plan letters and guaranteed-issue windows published on Medicare.gov.
- HSA/FSA tax rules cite IRS Publication 969 directly, with contribution limits updated each year IRS guidance changes.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- Social Security Administration — disability (SSDI/SSI) — federal disability benefits, the baseline private disability policies stack on.
- U.S. Department of Labor — Employee Benefits Security Administration — rules governing employer-sponsored voluntary benefits.
- Medicare.gov — Medigap (supplemental) — standardized Medigap plans and enrollment rights.
- IRS — Health Savings Accounts — HSA tax rules relevant to high-deductible plan strategy.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Supplemental Insurance: The Complete Guide
Supplemental insurance explained: hospital indemnity, disability, critical illness, AD&D, and burial policies — the cash benefits that fill major medical's gaps.
Read guide
Health Insurance: The Complete Guide
Health insurance runs through employer plans, ACA marketplace plans, Medicaid, and Medicare — this guide maps the costs, deadlines, and choices inside each path.
Read guideWhat Is COBRA Coverage?
COBRA is the federal right to continue an employer's group health plan after job loss by paying the full premium plus 2% — commonly for 18 months.
Read guideWhat Is a Qualifying Life Event?
A qualifying life event — losing job-based coverage, marriage, birth or adoption, a move, losing Medicaid — opens a 60-day special enrollment period.
Read guideWhat Is a Premium Tax Credit?
A premium tax credit (PTC) is the Affordable Care Act subsidy that lowers marketplace health premiums, capping what a household pays as a share of income each year.
Read guide