
Does Renters Insurance Cover Pet Damage?
Split — renters liability covers injuries and damage your pet causes to other people and their property; damage to your own belongings and apartment is excluded.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Split — renters liability covers injuries and damage your pet causes to other people and their property, but damage to your own belongings and the apartment you rent is excluded by design. Pet damage to your things is never a covered claim.
The pet liability that is covered
The liability piece of pet ownership is real, and it is the renters-insurance part: injuries and property damage your pet causes to other people are covered claims. A bite at the dog park, a scratch that sends a neighbor for stitches, a dog that knocks a cyclist off their bike — these are third-party bodily-injury and property-damage claims paid under personal liability up to the limit, with the insurer handling investigation and settlement. The bodily injury liability mechanics work the same way as any other liability claim.
Two gates apply: the breed disclosure (excluded breeds void the claim) and the limit itself — $100,000 default, $300,000 for a few dollars per month. Pet damage to a neighbor's belongings — the shredded garden hose, the ruined porch cushion — is third-party property damage and follows the same covered path. The breed and bite questions have their own page: dog bites under renters insurance.
The damage-to-your-own-unit gap
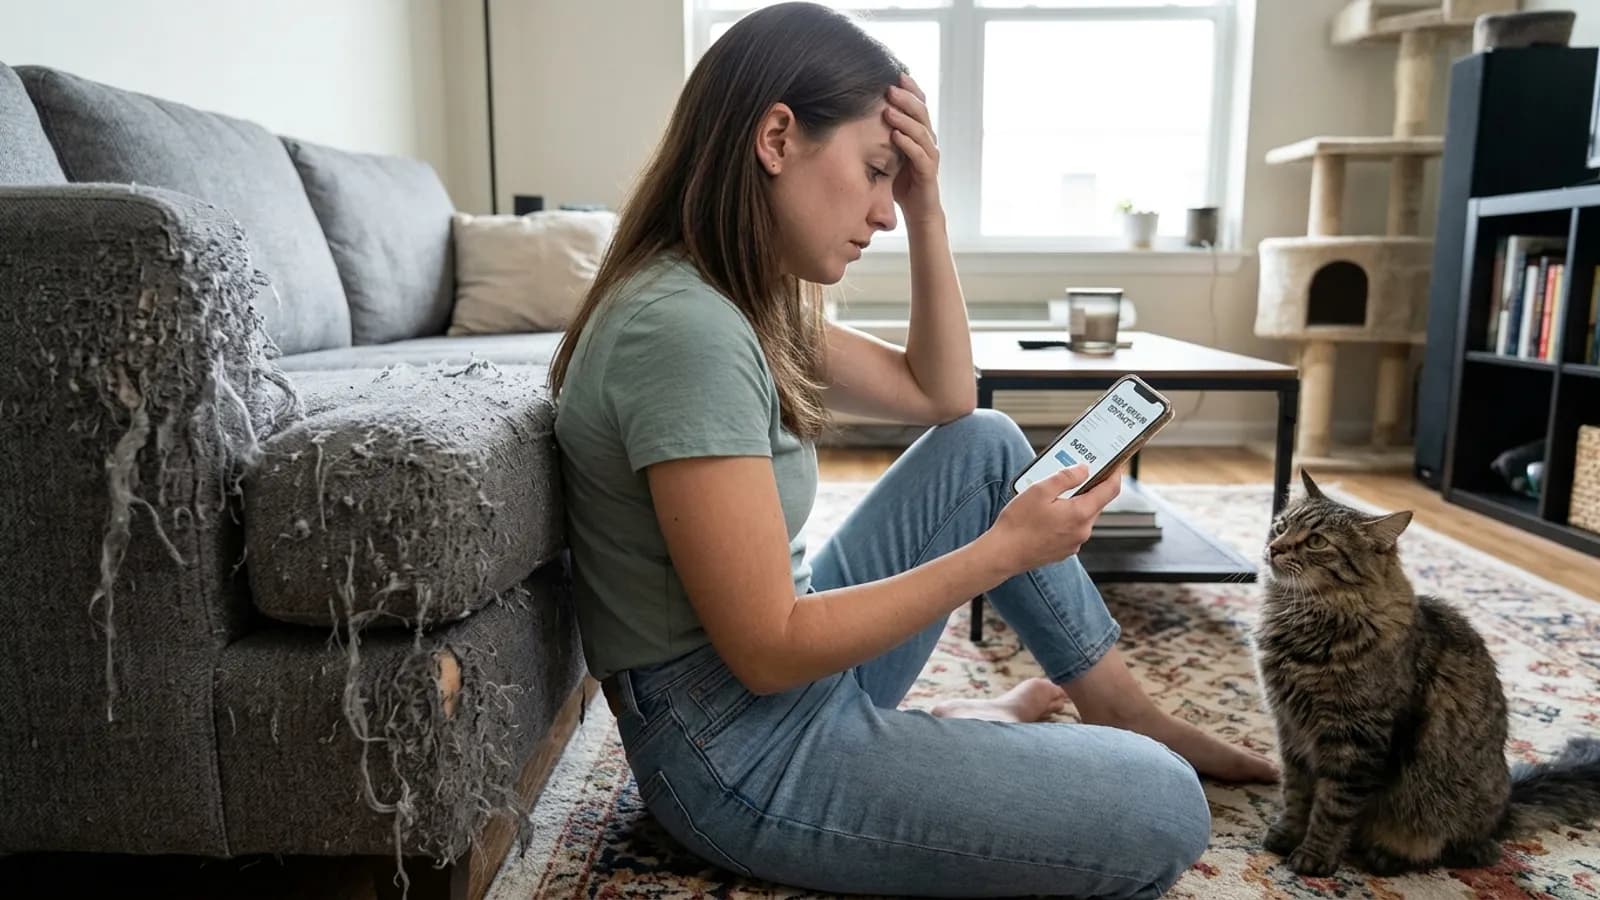
The most-asked pet question has the shortest answer: damage your pet does to the apartment you rent is not covered. Personal liability excludes property in your care, custody, or control — and the rented premises are the textbook example. Chewed baseboards, scratched door frames, stained carpet, and shredded blinds all trace to one funding source: the security deposit, then your own pocket when the deposit runs out.
No renters endorsement buys this coverage back; the fix is contractual, not insurance. Photograph the unit at move-in — dated, room by room — so pre-existing damage never lands on your deposit, and treat the pet-proofing budget (crate, scratch guards, washable rugs) as the actual insurance against pet damage. Skipping the disclosure step, meanwhile, is one of the eight mistakes that void the liability claims that are covered.
The pet-injury confusion
The direction of coverage runs one way, and renters reverse it often. Your policy pays for harm your pet causes; it never pays for harm to your pet. A dog hit by a car, a cat that swallows something toxic, a pet injured by another animal — none of that is a renters claim, because personal-property coverage excludes animals.
The funding sources for pet injuries are pet insurance, your emergency fund, or a claim against whoever negligently caused the injury — a neighbor's unleashed dog attacking yours is a claim against that neighbor, potentially through their liability coverage. The clean mental model: renters liability is what your pet does to the world; pet insurance is what the world does to your pet.
What the liability numbers look like in practice
| Scenario | Covered lane | Typical payout path |
|---|---|---|
| Dog bites a guest | Personal liability | Medical bills, then settlement, up to your limit |
| Dog shreds the neighbor's fence | Personal liability | Third-party property damage, up to your limit |
| Cat scratches the apartment's door frames | Not covered | Security deposit, then your pocket |
| Dog chews your own couch | Not covered | Contents excludes pet damage entirely |
| Pet swallows a foreign object | Not covered | Pet insurance or emergency fund |
The deposit defense at move-out
The deposit is where uncovered pet damage actually gets paid, and the defense is the same dated documentation that wins insurance claims. The move-in photo set — dated, room by room, blinds and baseboards included — draws the baseline; the move-out set against it shows what the pet actually did versus what the tenancy wore. Landlords bill against wear the tenant caused; pets blur that line in the landlord's favor unless the baseline exists. The charging pattern is predictable: carpet and blinds first, door frames second, everything else negotiable.
The insurance-side corollary: because the liability section never pays the rented premises, the pet-owning renter's risk transfer is prevention and documentation, not a policy upgrade. The $300,000 liability limit still matters — it covers the bite and third-party scenarios — but no limit setting touches the deposit lane.
Related guides
Pet damage splits across two policies and a lease:
- What Is Renters Insurance and How Much Does It Cost? — the liability, property, and loss-of-use structure for $15–$30 per month.
- What Is Liability Insurance? — the coverage part doing the work in every pet-injury claim.
- How to Choose the Best Renters Insurance Company — breed rules and pet pricing differ carrier by carrier.
- Pet Insurance: The Complete Guide — the product that covers veterinary bills the renters policy excludes.
Sources
Frequently asked questions
Does renters insurance cover scratched floors my landlord bills me for?
Generally no. Damage to the rented premises is excluded from liability as property in your care, custody, or control. The security deposit pays first, then you do — pet-proofing is the practical insurance here, and no renters endorsement buys this coverage back.
Is damage my dog does to a neighbor's property covered?
Yes. Damage to third-party property is a liability claim, paid up to your limit — the shredded garden hose and the ruined porch cushion follow the same covered path as a bite. Breed exclusions and the disclosure on your application still apply.
Does renters insurance pay my pet's medical bills?
No. Personal-property coverage excludes animals, so veterinary bills are pet insurance or emergency-fund territory. One exception: if a neighbor's negligence injured your pet, that is a claim against the neighbor, potentially through their liability coverage — photograph the incident and keep the vet record either way.
Does renters insurance cover dog bites?
Yes — through the liability section, for bites your dog inflicts on other people, on or off premises, subject to breed exclusions and disclosure. The dedicated dog-bite page covers the breed lists, the medical-payments piece, and the limits that matter.
Does renters insurance cover damage my cat does to the apartment?
Damage to the apartment is not covered — it is property in your care and control. Your liability section can respond to damage your pet causes to the landlord's other property or to third parties, but the deposit is a lease negotiation, not a claim.
How we researched this guide
Renters coverage is small and simple, but landlord requirements and state rules vary — so we verify both sides of the lease.
- What HO-4 policies cover (and the liability and loss-of-use mechanics) is verified against standard policy forms and DOI consumer guides.
- Landlord-side insurance requirements are framed against HUD tenant-rights resources, since required coverage limits appear in lease terms, not statutes.
- Cost figures are ranges by state and coverage limit, anchored to NAIC statistics.
- Disaster-aid expectations are set from FEMA guidance: federal assistance is not a replacement for coverage, and we explain exactly what it does pay.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HUD — tenant rights and responsibilities — state landlord-tenant rules that affect liability requirements.
- FEMA — renters and disaster assistance — what federal disaster aid does and does not cover for tenants.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Does Renters Insurance Cover Dog Bites?
Usually yes — renters liability covers dog bites your dog inflicts on others, up to your limit, but breed exclusions and undisclosed bite history can void the claim.
Read guide
The 8 Renters Insurance Mistakes That Cost Tenants Money
Eight renters insurance mistakes cost real money: ACV coverage, thin liability, skipped endorsements, unlisted roommates, undisclosed pets, and lapsed renewals.
Read guide
What Is Renters Insurance and How Much Does It Cost?
Renters insurance covers your belongings, liability, and hotel costs when the rental is unlivable, for about $15–$30 per month — what it pays and what it excludes.
Read guide
Pet Insurance: The Complete Guide
Pet insurance explained: what accident-and-illness policies cover and exclude, real monthly costs for dogs and cats, and the rules that decide claims.
Read guideWhat Is Bodily Injury Liability?
Bodily injury liability pays the medical bills, lost wages, and legal claims of people you injure in an at-fault crash — written as paired limits, such as 100/300.
Read guide