
Whole Life vs IUL: Guaranteed vs Indexed
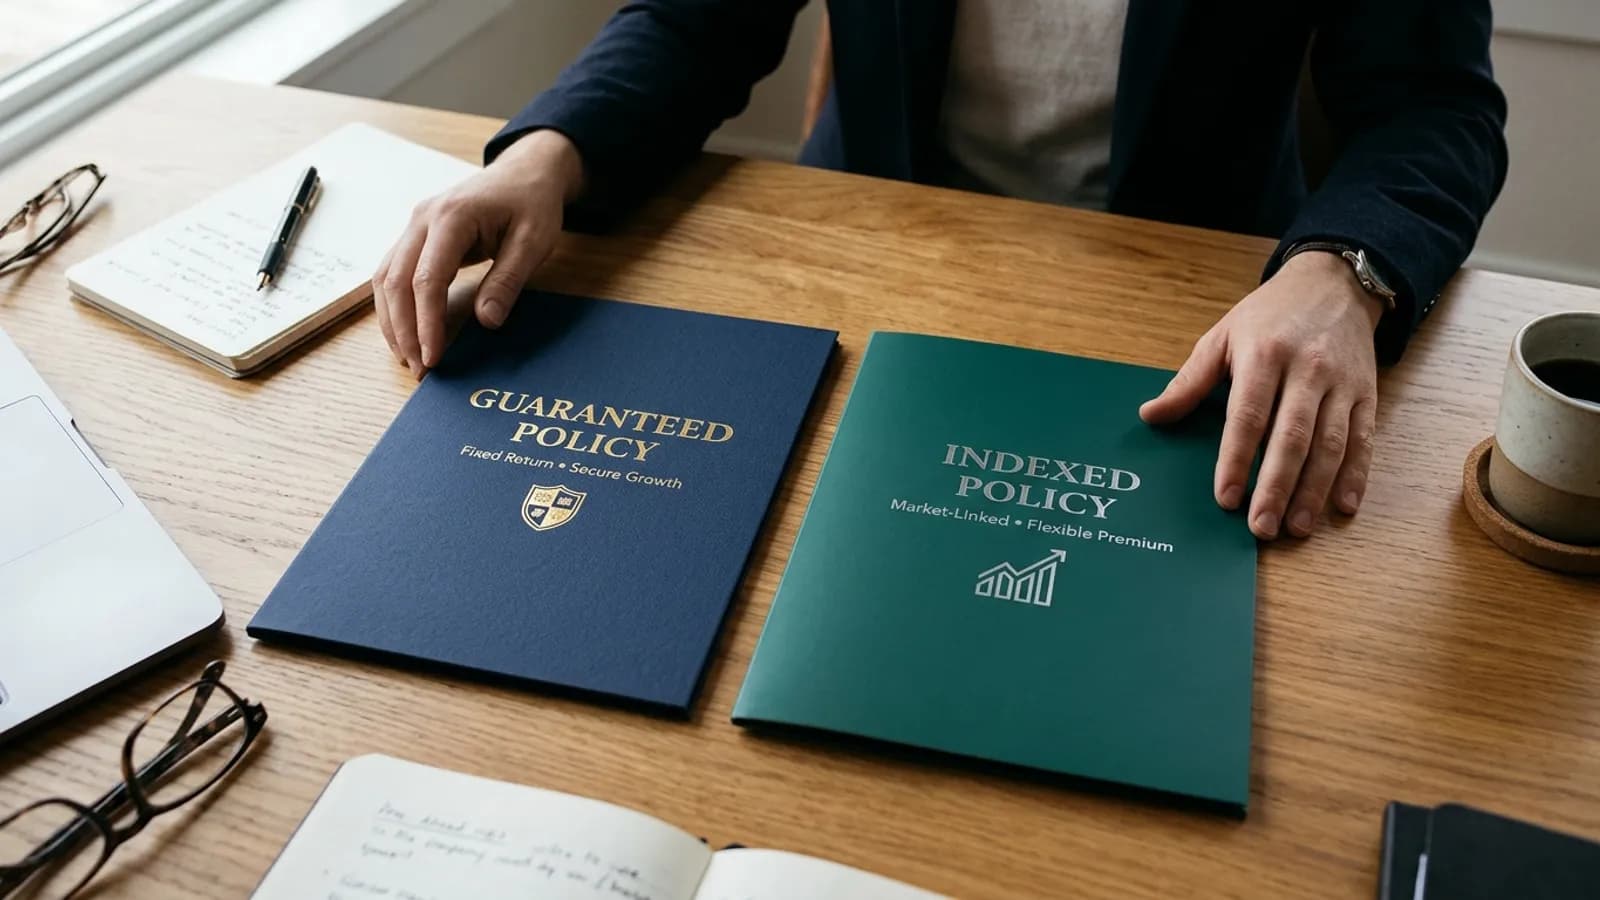
Whole life guarantees fixed rates and level premiums; IUL credits index-linked returns with caps and floors — compare the two permanent policies side by side.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
For most buyers of permanent coverage, whole life insurance is the sounder default: its premium, death benefit, and minimum cash-value growth are contractually guaranteed, while indexed universal life (IUL) trades those guarantees for index-linked upside that caps, fees, and weak markets can erode.
Whole life and IUL in one line each
Whole life insurance is permanent coverage with a fixed lifetime premium, a guaranteed death benefit, and cash value that grows at a guaranteed minimum rate; dividends from mutual carriers add non-guaranteed upside on top. Indexed universal life (IUL) is a form of universal life insurance whose cash value earns credits tied to a stock index, protected by a 0% floor and limited by a cap.
Side-by-side comparison
| Dimension | Whole life | IUL |
|---|---|---|
| Cash-value growth | Guaranteed minimum rate, plus non-guaranteed dividends | Index-linked credits, capped (commonly 8–12%), floored at 0% — never guaranteed |
| Premiums | Fixed and level for life | Flexible; underpayment enables lapse |
| Fees | Moderate and disclosed at issue | Rising cost-of-insurance charges plus policy fees |
| Worst case | Underperformance versus alternatives | Lapse if charges outpace credits and premiums |
| Maintenance | Pay the premium | Annual in-force review required |
| Complexity | Moderate | High — illustrations must be read on the guaranteed column |
Read the guaranteed column first
Every IUL illustration shows two sets of numbers: non-guaranteed values built on current cap and rate assumptions, and the guaranteed column built on contract minimums. The comparison method: request both illustrations, run each to age 100, and compare total premiums paid, face amount held, and lapse risk. If the buyer's decision flips depending on which column is read, the decision is being made by assumptions the carrier does not guarantee. Whole life's illustration has the same structure, but its guaranteed column carries the full promise — the gap between the two columns is small, which is the whole difference between the products.
When whole life is the better choice
The guarantee is the point. Whole life fits buyers whose budget cannot absorb premium increases, who want a policy that runs itself without annual maintenance, and whose plan depends on contractual certainty — funding a trust for a lifelong dependent, locking estate liquidity, or holding buy-sell money for a business. Participating policies from strong mutual insurers add dividend upside without touching the guaranteed floor, so the case for certainty does not require giving up all participation. The full mechanics are covered in the whole life guide.
When IUL is the better choice
IUL fits buyers with three things at once: a need for permanent coverage, the funded discipline to keep the account ahead of rising charges, and genuine appetite for index participation after seeing the guaranteed column. A well-funded IUL that is reviewed annually and topped up in weak years can outperform whole life's fixed rate over long horizons. The funding discipline has a hard edge: premiums pushed past statutory limits reclassify the policy as a modified endowment contract (MEC), which changes the tax treatment of loans and withdrawals — fund to a target, not to a ceiling, and get tax advice before overfunding. The design, dials, and traps are covered in the IUL guide.
The cost-of-insurance drag inside both policies
Both designs pay cost-of-insurance charges — the mortality charge — that rise annually as the insured ages, and the two designs handle the drag differently. Whole life bakes the entire mortality curve into one fixed, level premium: the buyer's experience never changes. IUL passes the rising charges to the account value each year, so later-year performance depends on accumulated credits outrunning accumulating charges. Strong early credits fund the late-year cost; weak sequences let the drag consume the account.
Which policy survives a bad decade
Stress both products against the same disaster: three consecutive zero-credit years in an IUL against three years of flat dividends in whole life. Whole life's guaranteed values grow exactly on schedule, the fixed premium continues, and the household's exposure is opportunity cost — the market ran, the policy did not. The IUL credits sit at zero while charges continue, cash value falls, and the policy drifts toward lapse unless premiums increase; a policy loan accelerates the drift, and a lapse with gains outstanding can end in a tax bill on value never received.
The comparison result is structural: whole life's worst case is underperformance, IUL's worst case is lapse. Choosing IUL accepts that asymmetry in exchange for upside participation — and makes the annual in-force review required maintenance.
Switching between them
A Section 1035 exchange moves cash value from an existing life policy into a new one without tax on the gains, so switching is mechanically simple. Economically it is not automatically wise: the new IUL applies its own surrender charges, and the guaranteed coverage being replaced cannot be rebuilt at the insured's current age and health. Read both contracts' guaranteed columns before moving value.
Related guides
The choice between permanent designs usually follows a bigger decision — whether permanent coverage is needed at all — and the neighboring pages handle the remaining branches.
- Term vs Whole Life Insurance: Which One Do You Actually Need? — the temporary-versus-permanent decision that usually comes first.
- Term vs Guaranteed Universal Life (GUL) — the other permanent alternative, with guaranteed-level premiums to a set age.
- Life Insurance: The Complete Guide — the hub covering every policy type and cost structure.
- What Is Cash Value in Life Insurance? — the account both designs build, at different levels of certainty.
- How to Choose the Best Life Insurance Company (No Sponsored Rankings) — caps, floors, and participation rates are carrier-specific and worth comparing.
Sources
Frequently asked questions
Which builds cash value faster, whole life or IUL?
On illustrations, IUL — which is why illustrations sell it. In reality it depends on index performance: IUL can outpace whole life in good decades and stall in bad ones, while whole life grows on its guaranteed schedule regardless. The guaranteed columns tell the honest comparison, and they usually favor whole life.
Is IUL cheaper than whole life?
Premiums are commonly lower for the same initial face amount, but the comparison is conditional: IUL's lower premium buys thinner guarantees, and staying insured to age 100 may require premium increases in weak years that a fixed whole life premium never asks for. The honest comparison runs both policies' guaranteed columns to age 100.
Can an IUL lose its death benefit?
Yes — through lapse. If index credits fall short while cost-of-insurance charges continue and premiums or loans do not compensate, the policy can exhaust its values and terminate, taking the death benefit with it. A lapse with outstanding loans can also trigger taxable gains. Whole life's death benefit is contractually guaranteed while premiums are paid.
Can the insurer change IUL caps and participation rates?
Yes, within contract limits. IUL carriers declare the cap, participation rate, and floor periodically, and those declarations can move with market conditions — the guaranteed column is the only part the carrier cannot cut. Whole life's guaranteed cash value growth rate is fixed in the contract and cannot change after issue.
Can I exchange a whole life policy for an IUL?
A Section 1035 exchange moves cash value between life insurance policies without triggering tax on the gains. The exchange is not automatically wise: the new IUL applies its own surrender charges and contract terms, and the guaranteed whole life coverage being replaced cannot be rebuilt at the insured's current age and health. Compare contracts before switching.
How we researched this guide
Life insurance is contract law: what matters is the policy's guarantees, so we verify against the policy documents and regulator guides, never illustrations alone.
- Policy mechanics (term conversion, guaranteed periods, lapse rules, contestability) are verified against insurer specimen policies and the NAIC Life Insurance Consumer Guide.
- Cost ranges use published rate-table patterns by age, term, and health class — always presented as ranges, because underwriting sets the final price per applicant.
- How much coverage a household needs is framed against Social Security survivors benefits (ssa.gov) and standard replacement-income math we show step by step.
- Claims statistics come from LIMRA industry studies and regulator complaint indexes, not from carrier press releases.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- NAIC consumer guides (incl. the Life Insurance Buyer's Guide) — how policies, illustrations, and guarantees work, straight from the regulators.
- Social Security Administration — survivors benefits — what Social Security already pays survivors, which shapes how much private coverage is needed.
- LIMRA (Life Insurance Market Research Association) — industry ownership and gap studies referenced for coverage statistics.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Life Insurance: The Complete Guide
Life insurance explained: term versus whole life, what coverage costs by age, how much death benefit a family needs, and the beneficiary mistakes to avoid.
Read guide
What Is IUL (Indexed Universal Life) Insurance? An Honest Guide
Indexed universal life (IUL) is permanent life insurance whose cash value tracks a market index with caps and floors — how it works, its costs, and its risks.
Read guide
What Is Whole Life Insurance? Pros, Cons, and Real Costs
Whole life insurance offers lifetime coverage, fixed premiums, and guaranteed cash value at 5–15 times the cost of term — how it works and who should buy it.
Read guide
Term vs Whole Life Insurance: Which One Do You Actually Need?
Term costs 5–15 times less and fits most families; whole life lasts forever with guaranteed cash value — the side-by-side with real prices.
Read guideWhat Is Universal Life Insurance?
Universal life insurance is permanent coverage with flexible premiums and cash value crediting a declared or index-linked rate — flexibility that enables lapses.
Read guideWhat Is Cash Value in Life Insurance?
Cash value is the savings component inside permanent life insurance — whole life builds it at guaranteed rates; term life has none.
Read guide