
Life Insurance in Your 50s: The LTC and Legacy Decade
The 50s: term windows narrow, long-term care insurance hits its ideal application age, and the group-life-to-individual handoff matters.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
The 50s are the transition decade: term windows narrow, long-term care insurance hits its ideal application age, and the conversion windows on older term policies become use-it-or-lose-it decisions. The decade's pricing still rewards health, and the retirement handoff punishes anyone who waits past it.
Typical costs
| Applicant (healthy, non-tobacco) | Typical monthly price |
|---|---|
| $500,000, 10-to-15-year term at 55 | ~$80–$150 per month |
| $250,000, 20-year term at 55 | ~$30–$50 per month |
| $1,000,000, 15-to-20-year term at 55 | ~$150–$300 per month |
Health classes harden in this decade — which is why accelerated underwriting shines for moderate faces and why every birthday between 50 and 60 moves the quote visibly.
The key moves
- Re-run the needs worksheet — the retirement-income-replacement number shrinks (see the calculation).
- Check every term policy's conversion deadline — the windows on 1990s-and-2000s-vintage policies are closing.
- Price long-term care insurance — the 55–60 window is the sweet spot of insurability and price.
- Plan the group-life handoff — employer coverage ends with the job; replace it before retirement does.
- Start final-expense planning — the need becomes permanent as the need for income replacement ends.
The conversion decision deadline
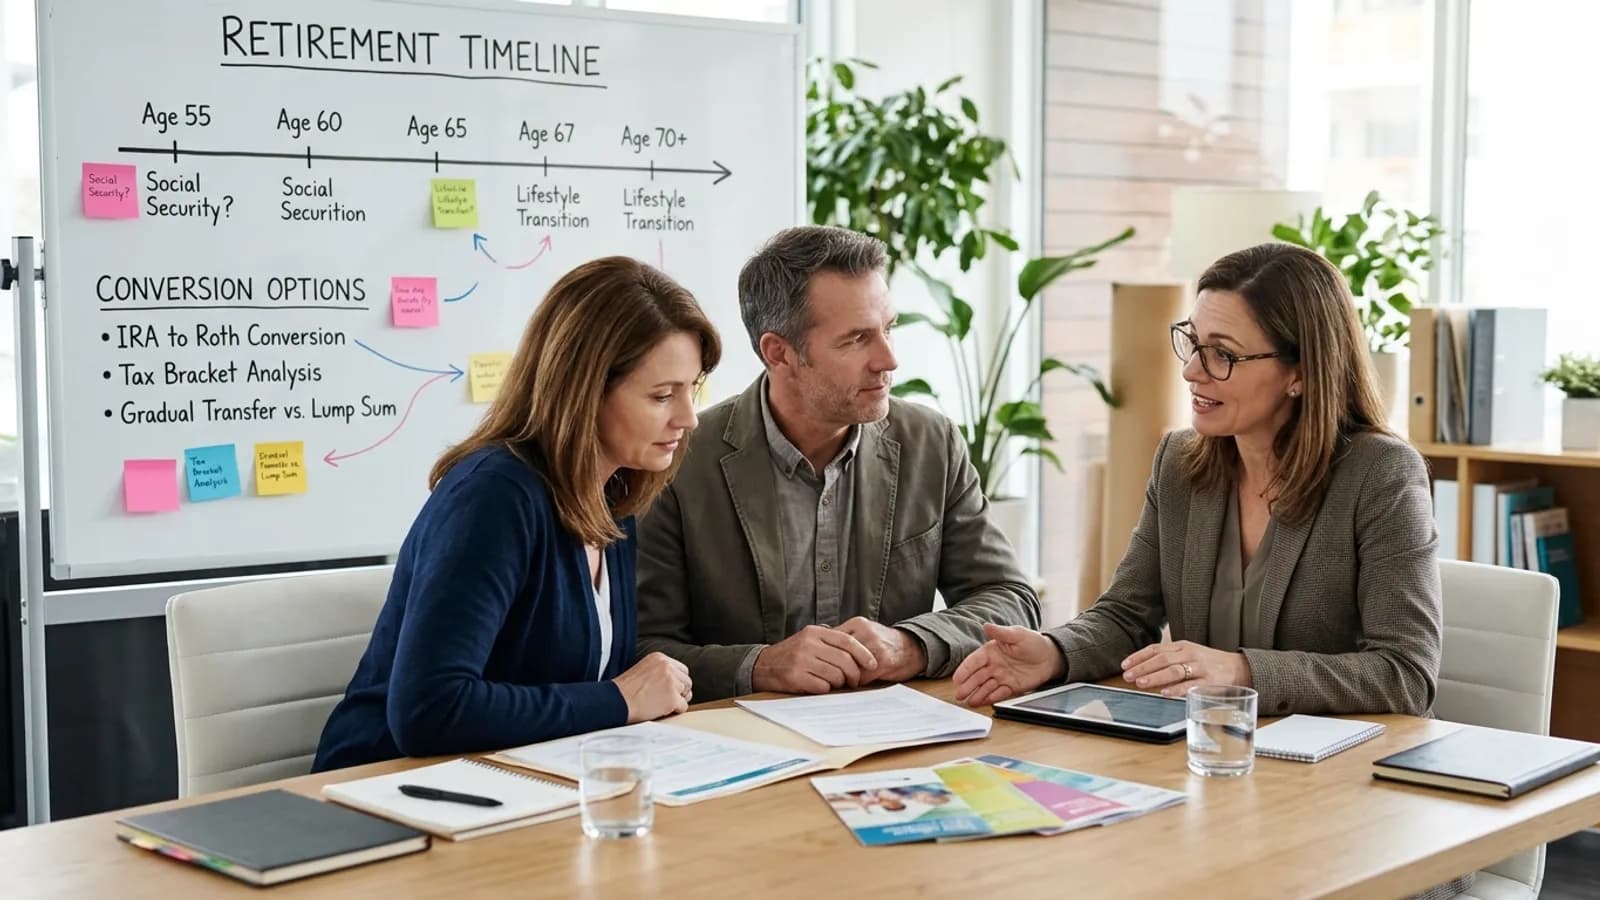
The 50s are when term policies bought decades earlier meet their conversion windows, and the window is a use-it-or-lose-it feature: conversion rights let the face convert to permanent coverage without new underwriting, but only before the contract's deadline — commonly a defined age or a set number of years into the policy (the conversion rider mechanics). The conversion math is specific: the permanent premium prices at your current age, so converting at 52 costs far less than the same face converted at 62; converting part of the face (many carriers allow partial conversion) is the standard move — the piece converted becomes permanent coverage for the need that never expires (final expenses, a legacy bequest, a dependent's lifetime), while the unconverted term continues cheaply. The riders guide ranks the conversion clause as the one that saves families.
Final expense vs term at 55: the crossover
The 50s pricing crossover is worth seeing in numbers. A healthy non-tobacco 55-year-old commonly pays $30–$50 per month for $250,000 of 20-year term — income-replacement-scale coverage at realistic prices. The same buyer paying $60–$90 per month for a $25,000 guaranteed-issue final-expense policy is paying a higher cost per thousand for a tenth of the face — the price of guaranteed acceptance. The crossover logic: term wins while underwriting is passable and the need is income replacement; final expense wins when health disqualifies term, when the need is small and permanent (end-of-life costs exist at every age), or when the buyer wants the policy to pay whenever death comes. The full product math is in the term-vs-final-expense comparison, and the 60s guide shows the ladder's next rung.
LTC insurance: the decade it prices best
Long-term care insurance is a 50s decision more than a 60s one, for underwriting reasons: applicants in their early-to-mid 50s pass health screening at meaningfully higher rates than applicants at 65, and the premium locks at issue age. The product answers a need the life insurance stack does not — extended custodial care (home health, assisted living, nursing care) that Medicare does not cover — and it interacts with life coverage through hybrid products: life policies with LTC acceleration riders extend the accelerated death benefit mechanics to chronic illness. The honest framing: LTC insurance is expensive and its value depends on the discount for applying while healthy; the 50s health file that passes life underwriting comfortably is the same file that passes LTC underwriting. Households that skip it self-insure knowingly. The broader supplemental landscape lives in the supplemental insurance hub.
The group-life handoff, step by step
The retirement handoff is a sequence, and each step has a deadline. Find the conversion deadline first: group certificates carry a conversion right — usually 30–31 days after coverage ends — that converts the group face to an individual permanent policy with no medical underwriting, priced at the current age. It is the only guaranteed door when health has failed, and it is usually the most expensive per thousand when health is fine. Price the replacement second: a new individual term or guaranteed universal life policy, underwritten while the health file still passes, commonly prices well below the converted group face — but it requires underwriting, so it must be bought before the coverage ends, not after. Check portability third: some employers offer portable group coverage that continues without the employer's subsidy; it survives the job but rarely wins a price comparison at 55. Size the remainder: the needs worksheet run at 55 decides how much of the group face is worth replacing at all — the surviving-income gap and final expenses are usually the only lines left. The sequence ends with one rule: nothing lapses before its replacement is in force.
Related guides
The 50s decisions hand off directly to the senior market's products and deadlines:
- Term vs Guaranteed Universal Life (GUL) — the permanent product that guarantees the death benefit to age 100+ at the lowest price.
- Life Insurance with No Medical Exam — the accelerated-underwriting route this decade's moderate faces qualify for.
- Life Insurance for Seniors: Real Options After 60 (and the Traps) — the product shelf and trap list the 60s open onto.
- What Is Term Life Insurance? How It Works and What It Costs — the term product still buyable in this decade, with prices.
- What Is Whole Life Insurance? Pros, Cons, and Real Costs — what a conversion actually converts into.
Sources
Frequently asked questions
Can I buy $1,000,000 of term in my 50s?
Yes, with full underwriting — healthy non-tobacco 55-year-olds are commonly approved for $1,000,000 of 15-to-20-year term at $150–$300 per month. The pricing scales steeply with age and health tier, and the needs re-run may show the number should be smaller anyway. Insurability exists in the 50s; the price just demands the calculation.
How much is life insurance per month at 55?
A healthy non-tobacco 55-year-old commonly pays $30–$50 per month for $250,000 of 20-year term, or $150–$300 per month for $1,000,000 of 15-to-20-year term with full underwriting. Prices step up steeply per year of age — the same face costs meaningfully more at 58 than at 52, so the application timing is a pricing decision.
What happens to employer group life when I retire?
It usually ends — group coverage is employment-conditional. The options: convert to an individual permanent policy during the carrier's conversion window (priced at your current age, no underwriting), buy replacement term or guaranteed universal life while health still passes, or let it end if the needs test returns a small number. Check the portability deadline before the last day of work.
What happens if I outlive the 20-year term I bought at 45?
The policy's renewal rates apply — priced at 65-year-old mortality, which is dramatically higher — or the policy simply ends if it has no renewal provision. The planning answers are earlier: convert part of the face during the conversion window, ladder so rungs expire as needs expire, and accept that post-65 needs are final-expense-shaped, not income-shaped.
Does life insurance still make sense in your 50s?
It depends on what dies with you: a working income a spouse depends on, dependent children, or debt argues yes — often via term to retirement. An empty mortgage, independent children, and funded retirement argue the smaller permanent-only case: final expenses and legacy. The needs test is the same worksheet, run at 55 instead of 35.
How we researched this guide
Life insurance is contract law: what matters is the policy's guarantees, so we verify against the policy documents and regulator guides, never illustrations alone.
- Policy mechanics (term conversion, guaranteed periods, lapse rules, contestability) are verified against insurer specimen policies and the NAIC Life Insurance Consumer Guide.
- Cost ranges use published rate-table patterns by age, term, and health class — always presented as ranges, because underwriting sets the final price per applicant.
- How much coverage a household needs is framed against Social Security survivors benefits (ssa.gov) and standard replacement-income math we show step by step.
- Claims statistics come from LIMRA industry studies and regulator complaint indexes, not from carrier press releases.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- NAIC consumer guides (incl. the Life Insurance Buyer's Guide) — how policies, illustrations, and guarantees work, straight from the regulators.
- Social Security Administration — survivors benefits — what Social Security already pays survivors, which shapes how much private coverage is needed.
- LIMRA (Life Insurance Market Research Association) — industry ownership and gap studies referenced for coverage statistics.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
Life Insurance for Seniors: Real Options After 60 (and the Traps)
Life insurance after 60: term into the 70s, guaranteed universal life for lifetime needs, final expense into the 80s — real prices and the traps.
Read guide
Term vs Final Expense Insurance
Term covers temporary needs cheaply and expires; final expense is small permanent coverage ($5,000–$25,000) for funeral costs at older ages.
Read guide
Life Insurance in Your 60s: The Transition Decade
The 60s: term scarcity begins, final-expense products enter, the pension-election life question arrives, and the Medicare transition changes the plan.
Read guideWhat Is a Conversion Rider on Term Life?
A conversion rider switches term life insurance to permanent coverage without a new medical exam — the original health class carries forward to the deadline.
Read guideWhat Is an Accelerated Death Benefit?
An accelerated death benefit lets a terminally or chronically ill insured access part of the death benefit while alive — typically 50–90% — reducing what beneficiaries later receive.
Read guide