
How to Read an Explanation of Benefits (EOB) — Line by Line
The EOB is the insurer's claim statement — billed, allowed, paid, your share — never a bill. Read it line by line to catch errors and track the deductible.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
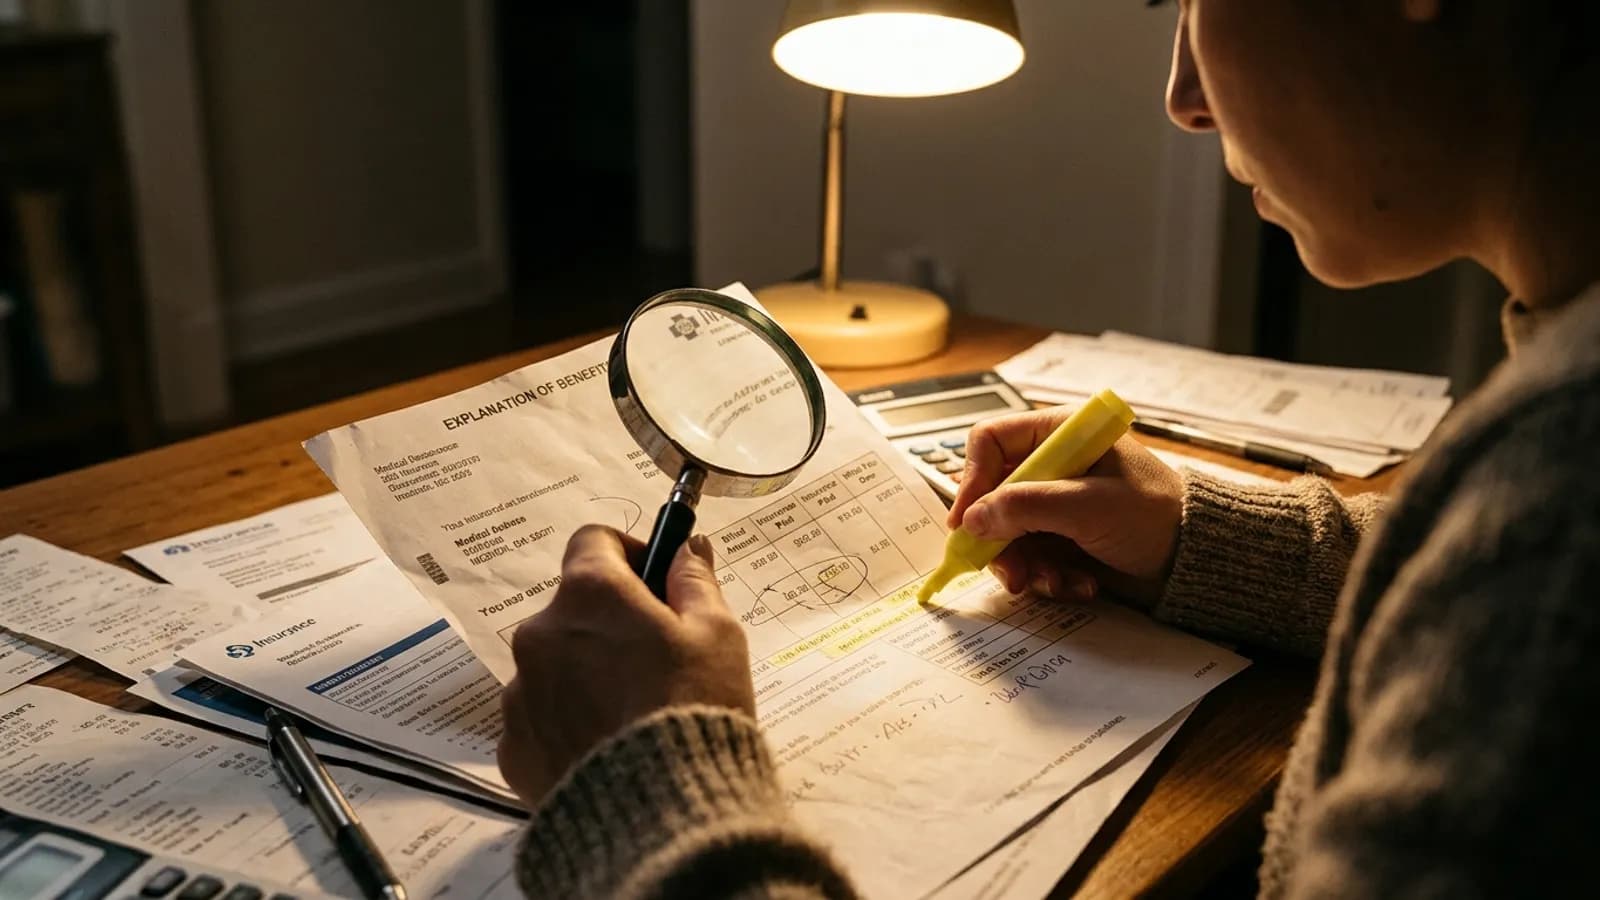
An Explanation of Benefits (EOB) is the insurer's statement of how a claim was processed — billed amount, allowed amount, plan paid, and your share — and it is not a bill. Reading it line by line catches billing errors, predicts the real bill, and tracks deductible progress toward the out-of-pocket maximum. The fields below run in a fixed chain, and the arithmetic is checkable.
The fields, decoded
| EOB field | What it means | What to check |
|---|---|---|
| Billed amount | Provider's sticker price | Meaningless alone — the network discount lives in the next line |
| Allowed amount | The negotiated rate your plan recognizes | The number your cost-sharing keys off — compare across claims for oddities |
| Plan paid | The insurer's payment | Zero? Check the deductible phase or the denial code |
| Patient responsibility | Your share (deductible + copay + coinsurance) | The number your bill should match |
| Denial/reduction code | Why anything wasn't paid | The appeal path starts here — see claim denials |
The money arithmetic: billed, allowed, plan paid, you owe
A worked example makes the chain concrete: a lab panel billed at $310; the plan's allowed (negotiated) amount is $120; the plan pays $85; you owe $35. The logic: the billed amount is the provider's list price — noise, in-network; the allowed amount is the contracted price — the real cost basis; the plan-paid and patient-owed split follows the plan design (deductible phase, coinsurance percentage, or copay). Two common patterns the arithmetic exposes: the deductible-phase claim (you owe the full allowed amount because the deductible is fresh), and the non-covered service (allowed equals billed at zero plan-paid, meaning the whole thing is yours — check whether it should have been covered).
The workflow: EOB → bill reconciliation
- Wait for both documents — the EOB (insurer) and the bill (provider).
- Match the claim numbers.
- Compare patient responsibility (EOB) against the amount due (bill).
- Mismatch? The EOB wins the argument — contact the provider's billing office with the EOB in hand.
- No bill after 60–90 days? Confirm the claim processed correctly (sometimes it processed as patient responsibility and nobody sent a bill — pay it before it collections).
The deductible tracker (the EOB's hidden value)
Each EOB's patient-responsibility line accumulates toward your deductible and out-of-pocket maximum. The tracking spreadsheet (or the insurer's app) answers the two questions that drive care-timing decisions:
- How far into the deductible am I? Scheduling elective care after it's met costs coinsurance, not full price — see the December strategy.
- How close to the out-of-pocket max? The worst-case number per plan, and the ceiling every EOB's running totals climb toward.
The errors the EOB reveals
- Duplicate billing — the same service code twice on one visit.
- Wrong coding — a routine screening billed as diagnostic (turning a $0 preventive visit into a deductible event).
- Out-of-network leakage — the facility was in-network; the anesthesiologist wasn't (the No Surprises Act protects some of this pattern).
- Denied claims that shouldn't be — the denial code with an appeal path attached.
- Balance billing beyond the allowed amount — illegal in-network, and protected in emergencies by the Act.
The denial codes and the follow-up script
The EOB's code section is where money is recovered, and the follow-up script is short. The code taxonomy: contractual reduction (the plan discounted the billed amount — normal, no action); deductible or coinsurance application (expected cost-sharing); non-covered service (check the plan documents and the specific CPT code — provider coding errors cause many of these); prior authorization missing (the fix is an authorization appeal, sometimes retroactive); and coordination-of-benefits confusion (two plans involved — the secondary-plan rules decide). The script for a wrong denial: call the plan's member line with the claim number, ask for the specific denial reason in plain language, and request the written review process; simultaneously call the provider's billing office — the two calls commonly reveal the error (a wrong code, a network-status mismatch) faster than either alone. The fraud-and-error habit: read the services listed per visit — duplicate line items, services dated after your visit, and inflated units ("2" in the units column doubles the claim) are the classics insurers take seriously when members report them, because the member is the only witness to what actually happened.
Related guides
The EOB sits between the premium math it audits and the billing mechanics it exposes.
- How Much Is Health Insurance? 2026 Costs by Plan Type — the premium math the EOB's numbers explain at claim level.
- What Is Coinsurance? — the percentage split in the middle of the arithmetic chain.
- What Is Prior Authorization? — the missing-approval denial path and its retroactive fixes.
- What Is Balance Billing? — the charge that appears when a bill exceeds the allowed amount.
- What Does Self-Pay Mean? — the bill that arrives with no claim behind it.
Sources
Frequently asked questions
What is an Explanation of Benefits (EOB)?
The EOB is the insurer's statement after processing a claim: what the provider billed, the insurer's allowed amount, what the plan paid, and what you owe. It is not a bill — but it predicts the one you'll receive, and reconciling the two is where billing errors surface. The field-by-field reading method below walks the chain.
What's the difference between an EOB and a bill?
The EOB comes from the insurer (the claim's math); the bill comes from the provider (the demand for your share). If the bill exceeds what the EOB says you owe, the provider billed wrongly — the EOB is your dispute evidence, and the mismatch is the complaint. Read the EOB before paying anything.
What are the most important EOB fields?
Four: the allowed amount (the negotiated rate your cost-sharing keys off), the plan-paid amount, your responsibility (the patient share), and the denial or reduction code with its reason. The billed-to-allowed gap is the network discount working; the patient-responsibility line is the number your eventual bill should match.
Why does my EOB show a patient responsibility I did not expect?
Three common causes: the claim ran through a fresh deductible (you owe the full allowed amount until it is met), coinsurance applied a percentage you forgot, or the service was non-covered. The EOB's own fields show which — find the allowed amount, the plan-paid line, and the denial or adjustment code. A bill exceeding the EOB's number is the dispute.
What should I do if the EOB denies a service I thought was covered?
Run the two-call sequence: ask the insurer for the specific denial reason and the appeal process in writing, and ask the provider's billing office to check the claim codes — coding errors and network-status mismatches cause a large share of these. Authorization-related denials often have retroactive fix paths. Mind the appeal window; it runs from the EOB date.
How do I track my deductible with EOBs?
Each EOB states the year-to-date deductible progress — sum the patient-responsibility lines (or read the running field) to see exactly where you stand mid-year. That number is the input for the December-timing decision: schedule planned procedures in December if the deductible is met, January if the plan is resetting anyway.
How we researched this guide
Health coverage rules change every plan year, so our guides are built on the current-year federal program documents and re-checked against them on a schedule.
- Enrollment dates, plan tiers, and subsidy mechanics come from HealthCare.gov and CMS program guidance — the same documents insurers and marketplaces must follow.
- Cost figures are ranges by plan tier, age band, and region, because marketplace premiums are set per county, not nationally.
- Medicare rules follow the current CMS handbook edition; when annual notices change, affected guides are updated within the same review cycle.
- What we don't cover: personal plan recommendations. We explain how to compare plans against your own expected usage instead.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov — ACA marketplace rules: plan tiers, enrollment periods, subsidies, and essential health benefits.
- Centers for Medicare & Medicaid Services (CMS) — Medicare and Medicaid program rules, annual enrollment guidance, and marketplace program documents.
- U.S. Department of Health & Human Services — ACA implementation regulations and preventive-care coverage rules.
- KFF (Kaiser Family Foundation) — nonpartisan health-policy research and marketplace enrollment statistics.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading
What Is a Deductible in Health Insurance? (With Real Numbers)
The deductible is what you pay for covered care before cost-sharing starts — how it pairs with copays, coinsurance, and the out-of-pocket maximum, worked in dollars.
Read guide
Surprise Medical Bills and the No Surprises Act: Your Protections
The No Surprises Act bans most surprise out-of-network billing for emergency and facility care: what is protected, the ambulance gap, and how to fight a wrong bill.
Read guide
Health Insurance: The Complete Guide
Health insurance runs through employer plans, ACA marketplace plans, Medicaid, and Medicare — this guide maps the costs, deadlines, and choices inside each path.
Read guideWhat Is an Explanation of Benefits (EOB)?
An Explanation of Benefits (EOB) is the insurer's after-claim statement — billed, allowed, plan paid, patient responsibility — not a bill, but bills must match it.
Read guideWhat to Do About a Claim Denial
A claim denial is the insurer's refusal to pay, issued with a reason code. Fix by resubmission, internal appeal within 180 days, then independent external review.
Read guideWhat Is an Out-of-Pocket Maximum?
The out-of-pocket maximum is the annual cap on your share of covered in-network care — deductible, copays, and coinsurance all count, then the plan pays 100%.
Read guide