
Turning 26: Your Health Insurance Deadline
Turning 26 ends parent-plan coverage — the end date varies by plan, the 60-day special enrollment window is the deadline, and three replacement doors follow.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
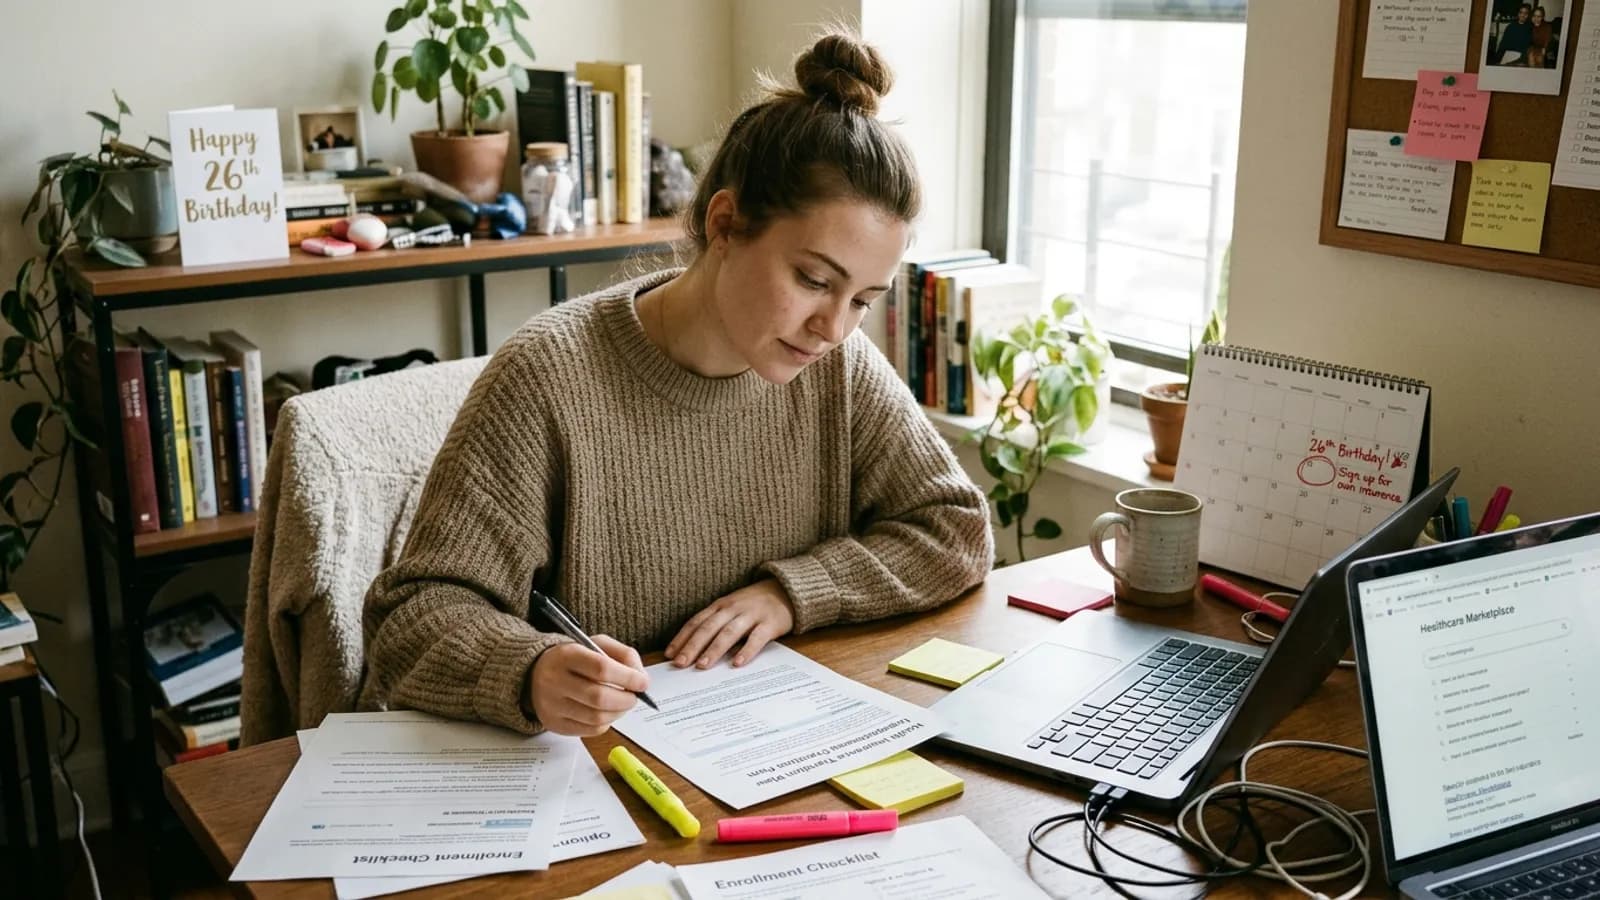
Turning 26 ends parent-plan dependent coverage — the exact end date varies by plan, the 60-day special enrollment window is the deadline that matters, and the replacement choice sorts into three doors by income and employment. The mechanics below make the transition deliberate instead of accidental.
The end-date mechanics: birthday, plan year, and the coverage cliff
The age-26 end date has mechanics that surprise most families. The ACA mandates dependent coverage up to age 26 — no student or dependency requirements — but the exact last day depends on the plan: many employer plans end dependent coverage at the end of the month of the 26th birthday, some run through the end of the plan year in which the child turns 26, and marketplace plans follow their own stated terms. Two siblings born months apart can lose coverage on different dates under the same parent's plan. Read the dependent-termination clause, not the age in the brochure, and calendar the date — the college students guide covers the student-specific checks before that date arrives.
The 60-day window (the deadline)
Losing dependent coverage is a qualifying life event: a 60-day special enrollment period opens on the loss, and replacement coverage can start before the old plan ends if the switch is planned. The trap is the mental version — staying on the parent's plan after it ended. The 60-day window closes, and the next door is January 1 open enrollment with a fully uninsured autumn in between. The open enrollment dates page maps the annual windows against the birthday timeline.
Typical costs
Unsubsidized marketplace coverage for a 26-year-old commonly runs $300–$500 per month for silver-tier plans, varying by state and county. Subsidies act on the 26-year-old's own household income now — and the 26-year-old income band is where subsidies work hardest: a low first-job income can produce heavily subsidized silver or near-free bronze.
The three replacement doors, priced for the 26-year-old
- Employer coverage: the default for the employed — the enrollment window runs alongside the SEP from the coverage loss, and new-hire waiting periods are the gap to bridge. The employer open enrollment method decides the plan tier.
- The marketplace: the default for the unemployed or self-employed — run the quote at actual projected income, because the difference between doors can be hundreds of dollars per month.
- Medicaid: for genuinely low incomes in expansion states, the near-zero-cost answer, enrolling year-round — see the Medicaid expansion rules.
The getting-covered guide ranks all three doors for each situation.
The parent-side mechanics: the shared decision before 26
The age-26 conversation is a two-party decision, and the parent's side has its own economics. Adding a 25-year-old to an employer family plan usually adds nothing (family coverage is family coverage), though some plans price tiered coverage, and the dependent's marketplace alternative at low income can be heavily subsidized — making the family split the cheaper structure in some years. The coordination rules: the dependent does not need to live with the parent or be a tax dependent under the ACA rule; marriage ends dependent eligibility; and dual coverage is not worth maintaining — a 26-year-old on both a parent's plan and a marketplace plan creates coordination confusion, not redundancy. The pre-26 planning move: at 25, price the three doors for the upcoming birthday year and calendar the end date, because the cheapest transition is the planned one.
Related guides
The age-26 transition connects to the qualifying-event rule, the subsidy math on your own income, and the low-premium products a healthy 26-year-old prices.
- What Is a Qualifying Life Event? — the trigger behind the 60-day window, defined term by term.
- What Is a Premium Tax Credit? — the subsidy computation that now runs on your income alone.
- Catastrophic Health Plans — the under-30 low-premium option the birthday makes newly available.
- Health Insurance for the Self-Employed — the income-projection rules for first-job and freelance years.
- Health Insurance: The Complete Guide — the silo hub for every coverage path.
Sources
Frequently asked questions
Does my insurance end exactly on my 26th birthday?
Not necessarily — the Affordable Care Act (ACA) requires coverage up to age 26, but the last day depends on the plan: many employer plans terminate at the end of the birthday month, some run through the plan year's end, and marketplace plans state their own terms. Read the dependent-termination clause in the plan documents and calendar the date. Losing the coverage is a qualifying event that opens a 60-day window to enroll in replacement coverage.
What is the cheapest health insurance at 26?
It depends on income and employment: employer coverage wins for the employed with a real contribution; a low income makes heavily subsidized marketplace silver — or Medicaid in expansion states — the near-zero-cost answer; and a moderate income makes the subsidy-adjusted marketplace the default. Unsubsidized marketplace coverage for a 26-year-old commonly runs $300–$500 per month, so run the quote at your projected income before defaulting to any option.
Can I stay on my parent's plan if I get married at 25?
No — marriage ends dependent eligibility under the parent's plan, but it opens a special enrollment period for both spouses, so the 60-day window to get marketplace or employer coverage starts at the marriage. Neither spouse needs the other's employer plan: two marketplace plans or one employer family plan are the standard routes. Plan the switch before the wedding date rather than discovering the gap after it.
Can I stay on my parent's plan if I live in a different state?
Yes — eligibility to 26 does not depend on residence, student status, or financial dependence, so a child living across the country can stay enrolled. The catch is network, not eligibility: an HMO or regional PPO may have few in-network providers near the child's city, leaving emergency-only coverage in practice. Verify providers near the child's residence, and if the network fails, price the marketplace plan in the child's own state.
How we researched this guide
Health coverage rules change every plan year, so our guides are built on the current-year federal program documents and re-checked against them on a schedule.
- Enrollment dates, plan tiers, and subsidy mechanics come from HealthCare.gov and CMS program guidance — the same documents insurers and marketplaces must follow.
- Cost figures are ranges by plan tier, age band, and region, because marketplace premiums are set per county, not nationally.
- Medicare rules follow the current CMS handbook edition; when annual notices change, affected guides are updated within the same review cycle.
- What we don't cover: personal plan recommendations. We explain how to compare plans against your own expected usage instead.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- HealthCare.gov — ACA marketplace rules: plan tiers, enrollment periods, subsidies, and essential health benefits.
- Centers for Medicare & Medicaid Services (CMS) — Medicare and Medicaid program rules, annual enrollment guidance, and marketplace program documents.
- U.S. Department of Health & Human Services — ACA implementation regulations and preventive-care coverage rules.
- KFF (Kaiser Family Foundation) — nonpartisan health-policy research and marketplace enrollment statistics.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Health Insurance: The Complete Guide
Health insurance runs through employer plans, ACA marketplace plans, Medicaid, and Medicare — this guide maps the costs, deadlines, and choices inside each path.
Read guideWhat Is a Qualifying Life Event?
A qualifying life event — losing job-based coverage, marriage, birth or adoption, a move, losing Medicaid — opens a 60-day special enrollment period.
Read guideWhat Is a Premium Tax Credit?
A premium tax credit (PTC) is the Affordable Care Act subsidy that lowers marketplace health premiums, capping what a household pays as a share of income each year.
Read guide
Catastrophic Health Plans: Who Qualifies and What They Cover
Catastrophic plans cover under-30s and hardship exemptions: lowest marketplace premiums, an $8,500 2026 deductible, three free primary visits, no subsidies.
Read guide
Health Insurance for the Self-Employed: Your Real Options in 2026
Self-employed health insurance: four real paths, from subsidized marketplace plans to sharing ministries, with monthly costs and tax angles for each.
Read guide