
Gym and Fitness Studio Insurance: Coverage for the Injury-Prone Floor
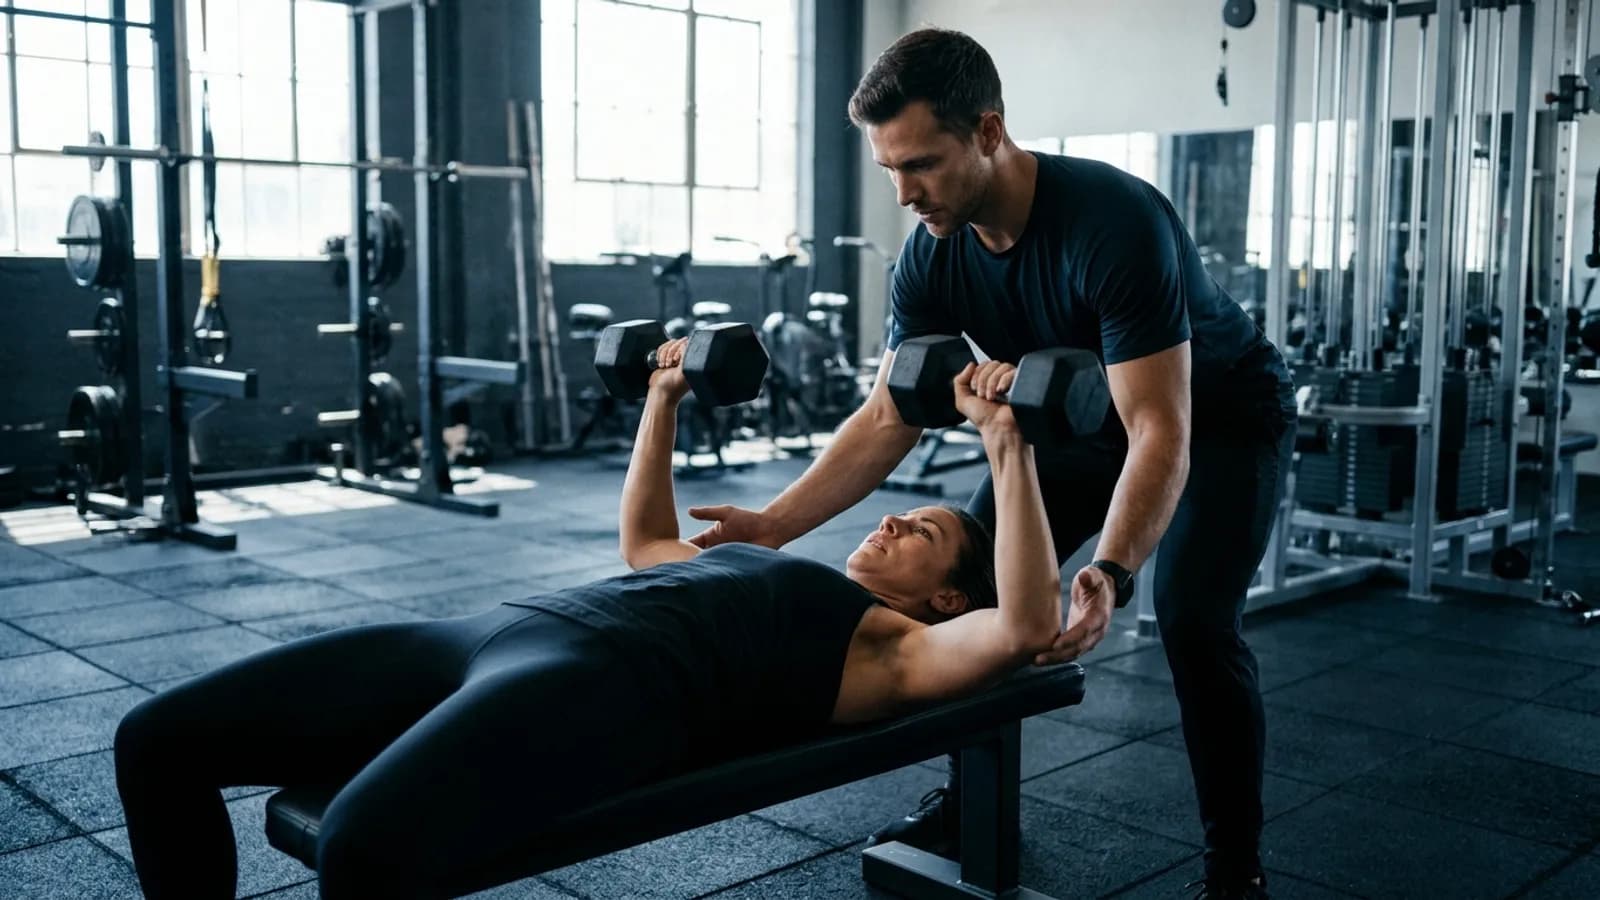
Gym insurance is built around member injuries; boutique studios commonly pay $100–$250 per month, while large facilities with pools price higher.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Gym insurance is liability-max on the injury-prone floor: member injuries are the claim category, the equipment is the property line, and the trainer-advice claims sit in professional liability. Boutique studios run $100–$250 per month; the waiver forms help, and the coverage is the real answer.
The gym stack
| Policy | Covers | Typical monthly cost |
|---|---|---|
| General liability (member injuries) | Falls, equipment injuries | $80–$300 |
| Property / equipment | Machines, free weights, flooring | $50–$200 |
| Professional liability | Training-program claims | $30–$100 |
| Workers compensation | Trainers, front desk | Priced per payroll |
| Abuse coverage | Youth programs | $50–$150 |
| Business interruption | Closure scenarios | BOP component |
The liability line works like any premises policy — third-party injury on your premises and from your operations — but priced for the one business where injuries are the product working as intended; the mechanics are the general liability rules, and the property line usually rides in a BOP.
The gym-specific claims
- The equipment injury — the cable machine failure, the dropped-weight bystander.
- The trainer-program injury — the program that caused the injury; the professional-liability lane.
- The locker-room theft — member property claims, usually answered only where the gym was negligent (the broken lock, the unsecured door).
- The youth-program allegation — the abuse-coverage scenario.
- The pool or sauna incident — the facility-feature liability that raises the whole floor's pricing.
The waiver forms: the honest limits
Waivers reduce claims for inherent risks — ordinary muscle soreness, standard-equipment use. They do not cover negligence: the broken cable, the unqualified trainer, the wet floor nobody mopped. State enforceability varies, so the stack is the answer and the waiver is the supplement. Signed by every member, retained, and versioned when the form changes, the waiver also becomes claim evidence — a gym that cannot produce the member's signed waiver defends the same claim worse.
The maintenance log that decides the squat-rack claim
Gym liability claims turn on equipment condition, and equipment condition turns on records. The claim file for an injured member requests: dated inspection and maintenance logs for every machine, cable and upholstery replacement records, manufacturer recall responses, and staff incident reports written the day of the injury. A gym with a documented monthly inspection cycle defends a claim cheaply — the adjuster sees a managed environment; a gym without records pays for the same injury twice, once in settlement and once in legal fees reconstructing what it cannot prove. The operational fix is a clipboard-and-dates system: a monthly inspection sheet per machine zone, a work-order log, and a same-day incident report template at the front desk. Carriers price the discipline into the premium — documented safety programs are loss control in the literal sense.
Off-site classes, pop-ups, and the location gap
The gym's policy covers described locations, and the boot camp in the park is not one of them. Off-site classes, outdoor sessions, hotel-partner programs, and pop-up events each extend the premises — some carriers extend by endorsement, others by adding locations, and others prefer a short-term event policy. The same gap applies to trainers you send into clients' homes and to classes you run at schools or offices. The check is mechanical: list every location where members exert themselves under your supervision, verify each appears on the certificate or an endorsement, and confirm the off-site activities' waiver language matches the on-site version. Off-site is where insured gyms most often discover their policy's geography.
A 5,000-square-foot studio's annual budget
A mid-size gym or fitness studio — 5,000 square feet, 300–800 members, four staff — commonly budgets the following per year: general liability with participant coverage at $1M/$2M for $1,500–$4,000 (about $125–$335 per month); property for equipment at $300–$1,000 (value the cardio row at replacement cost); workers compensation for staff, priced per payroll, commonly $1,000–$2,500; professional liability for training advice at $300–$1,000; and, where minors train, verify the abuse-coverage terms explicitly. Total: roughly $3,500–$8,000 per year — about $290–$670 per month. Two pricing levers move the number: documented safety programs (staff certifications, equipment logs, member intake forms) and waiver enforcement.
The staff certification file
Fitness staffing is a certification business as far as underwriters are concerned, and the file doubles as the liability defense. What carriers ask at quoting: trainer certifications from recognized bodies, current CPR and AED credentials for everyone on the floor, and documented continuing education. What the claim file adds: the trainer's certificate on the day of the injury, the member's intake and health-history form, and the program design records for the session in question. A trainer training outside their certification scope — the yoga instructor prescribing post-surgical rehab programming — is the claim that pierces both the certification file and the professional-liability line. The employment-side mechanics of the same file — payroll, workers-comp class codes for fitness staff, the first-trainer hire — are in the workers comp guide and the first-employee checklist. And when the gym adds a childcare room, the exposure stops being fitness insurance entirely — the daycare-specific stack, abuse coverage included, is in the daycare guide.
Related guides
The gym stack borrows from the liability and employment pages around it:
- BOP Insurance — the property-plus-interruption bundle under the equipment line.
- Certificate of Insurance — the document independent trainers hand you before session one.
- How Much Is Business Insurance? — costs by policy and business type.
- Business Insurance: The Complete Guide — the full small-business coverage map.
Sources
Frequently asked questions
How much is gym insurance?
Boutique studios commonly pay $100–$250 per month. Mid-size gyms pay $250–$500 per month. Large facilities with pools, saunas, and youth programs pay $500–$1,500+ per month. The waiver forms help; the liability limits are the real protection.
What insurance does a gym need?
General liability (member injuries — the core), property coverage for the equipment, workers compensation for trainers and staff, professional liability for training-advice claims, sexual-abuse coverage where youth programs exist, and business interruption for the closure scenarios.
Do liability waivers protect gyms?
Partially — waivers reduce claims for inherent risks (ordinary soreness, standard equipment use) but do not cover negligence (broken equipment, unqualified trainers). State rules vary on waiver enforceability; the coverage is the real answer and the waiver is the supplement.
Does gym insurance cover trainer advice claims?
Professional liability covers the training-program injury claim — the program that caused the injury — while general liability covers the slip-and-fall. Trainers employed by the gym ride the gym's coverage; independent trainers need their own.
Does gym insurance cover personal trainers who rent space from me?
Not automatically — independent trainers are businesses, not your employees, and their liability is theirs. The standard arrangement: trainers carry their own general liability and professional liability naming your gym as additional insured, and provide certificates before their first session. The gym's policy then answers premises claims; the trainer's answers training claims.
Are children in the childcare area covered?
Childcare inside a gym is a daycare exposure, not a fitness one — general liability alone does not answer supervision, abuse, or child-injury claims well. Gyms offering childcare need the daycare-specific endorsements (abuse coverage, higher supervision limits) or a separate daycare policy. The underwriting file is the same as any center: ratios, background checks, protocols.
How we researched this guide
Business insurance requirements are mostly statutory — workers comp is state law — so our guides separate legal requirements from prudent coverage.
- Workers-comp rules (who must carry, exemptions, monopolistic states) are verified against state statutes and NCCI classifications.
- General liability and BOP coverage mechanics are verified against standard policy forms and SBA guidance.
- Professional-liability explanations distinguish the claims-made trigger and tail options, because that's where businesses get caught.
- Industry examples use realistic claim scenarios published by insurers and courts, and we label estimates as estimates.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- U.S. Small Business Administration (SBA) — which policies a business legally needs and how to buy them.
- OSHA — Occupational Safety and Health Administration — workplace safety rules that drive workers-compensation obligations.
- NCCI — National Council on Compensation Insurance — workers-comp class codes and rate filings used in most states.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Business Insurance: The Complete Guide
Business insurance explained: the general liability, BOP, workers comp, E&O, and commercial auto policies a small business needs — and what each costs per month.
Read guide
What Is a BOP (Businessowners Policy)? The Small-Business Bundle
A Business Owners Policy (BOP) bundles general liability, commercial property, and business interruption at a discount; most small businesses pay $50–$300 per month.
Read guide
What Is General Liability Insurance? Coverage and Costs
General liability insurance pays third-party injury and property damage claims; small businesses pay $40–$100 per month for the standard $1M/$2M limits.
Read guide
Workers Comp Insurance: Requirements, Costs, and the Rules Employers Miss
Workers compensation insurance is required in nearly every state; class codes and experience modifiers price a typical small employer at $40–$150 per month.
Read guide
Daycare Insurance: Coverage for Childcare Businesses
Daycare insurance pairs child-injury liability, abuse coverage, and licensing mandates; home daycares pay $100–$250 and centers $400–$1,500 per month.
Read guide