
Commercial Auto Insurance: When Your Personal Policy Stops Working
Commercial auto insurance exists because personal policies exclude business use; most small businesses pay $100–$250 per month per vehicle, and HNOA fixes the rest.
Why you can trust this guide
- Written by Daniel Reyes, AINS, former licensed P&C agent — independent insurance education publisher.
- Factual accuracy reviewed and signed off by Marcus Hale, CPCU, AINS, licensed P&C agent (Independent insurance reviewer).
- Every factual claim traces to a regulator, statute, or policy document — sources are listed at the bottom of the page.
- Last verified ; time-sensitive guides are re-checked at least twice a year. Read our editorial policy.
On this page
Commercial auto insurance exists because personal auto policies exclude business use — and the exclusion surface area is bigger than most owners think: deliveries, client visits by employees, errands in company vehicles, anyone driving for the business. The gap-filler for the in-between cases costs $15–$50 per month.
The four auto-insurance situations
| Situation | What covers it |
|---|---|
| Commuting to your job | Personal auto |
| You driving your own car for light business errands | Personal auto sometimes — policy language varies; confirm |
| Deliveries, transporting goods or people for pay, heavy business use | Commercial auto — personal policies exclude livery and delivery |
| Employees driving their own cars for work | HNOA (hired and non-owned) — employees' personal policies exclude business use |
| Rideshare and delivery apps | A rideshare endorsement — the consumer side is in the car insurance guide |
What commercial auto covers
- Liability (bodily injury and property damage) for business vehicles — limits sized to the exposure; $1 million is common, and interstate trucking requires federal filings
- Physical damage (comprehensive and collision) on owned vehicles
- Cargo and contents endorsements for tools, equipment, and goods in transit
- Hired auto — rented vehicles used on business
- Filings — FMCSA forms for interstate carriers, livery filings where applicable
The heavy-vehicle end of this list — box trucks, tractor-trailers, federal filings — has its own economics in the trucking insurance guide.
HNOA: the $15–$50-per-month gap-filler
The most common small-business auto gap is not a company truck — it is an employee driving their own car to a client meeting or supply run. The employee's personal policy covers their risks but often excludes business use. If they cause a serious accident on business, the claimant sues the business too. HNOA — an endorsement on a general liability or BOP policy — provides the business with liability protection over that exposure. Ask for it if the answer to "do employees ever drive for work?" is anything but a hard no.
What it costs
| Coverage | Typical monthly cost |
|---|---|
| HNOA endorsement (on GL/BOP) | $15–$50 |
| Commercial auto, service vehicle (van or truck, low miles) | $100–$250 |
| Delivery vehicle, urban routes | $200–$400+ |
| Fleet pricing | Per-vehicle discounts at 3+ units |
Pricing drivers: vehicle type, driver records, operating radius, cargo, and filings. The cross-industry benchmarks are in how much business insurance costs.
The traps
- Title versus use confusion — a personally titled car used heavily for business is still a commercial-use problem; conversely, an LLC-titled car needs the policy named to the LLC.
- The 10,000-pound line — heavier vehicles (box trucks, some one-ton rigs) fall outside personal policy forms entirely.
- Employee MVRs unchecked — pricing and insurability ride on the motor vehicle record; pull MVRs before hiring drivers.
- Cargo assumptions — tools and inventory in transit need inland-marine or cargo endorsements; the auto policy's contents coverage is thin.
- Personal policy silence — the exclusion does not announce itself; it appears in the denial letter. Disclose business use at application and endorsement time.
Radius, weight, and the rating class underneath the quote
Commercial auto pricing starts with three fields, not four wheels. Radius — how far the vehicle roams from its garaging address — splits into local, intermediate, and long-haul bands, and a delivery radius crossing state lines moves the file to different underwriting. Weight — gross vehicle weight class — separates a cargo van from a box truck. Body type and use — service van, delivery, dump, towing — assigns the class code the premium multiplies from. A landscaper's F-250 parked overnight and the same truck running full-day routes with a trailer price differently for reasons the VIN cannot explain. Getting these three fields accurate at application prevents the audit-time re-rating that surprises renewals.
Physical damage: ACV, deductibles, and the loan balance
Liability limits protect other people; physical damage protects the vehicle itself. Comprehensive and collision on a commercial auto policy pay actual cash value — the depreciated street value — minus your chosen deductible. The trap sits between ACV and finance: a $38,000 van two years old carries maybe $26,000 of ACV against a $33,000 loan balance, and a total loss pays the first number, leaving the gap unpaid unless gap insurance was purchased at finance time. Deductible choice is a claim-frequency decision: commercial vehicles run more miles and more claims than personal cars, so a $1,000 deductible on a van that backs into posts twice a year costs more than it saves.
What a two-van service business pays
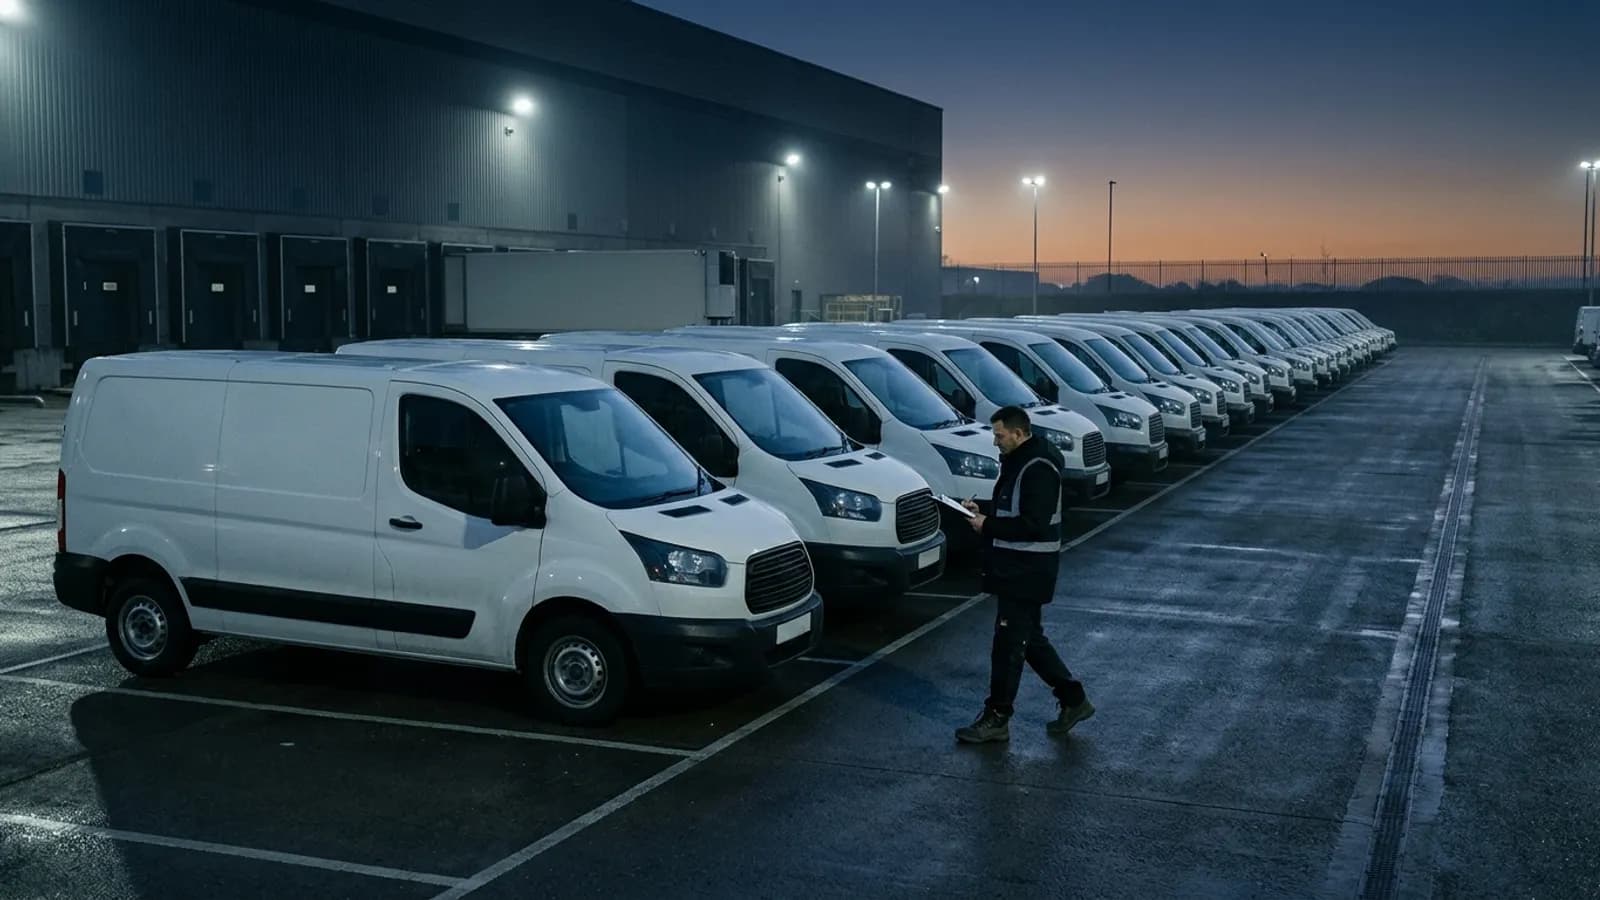
A plumbing or electrical shop running two cargo vans with $1 million combined single limits commonly sees $100–$250 per month per vehicle ($1,200–$3,000 per vehicle per year) — priced on radius, driver records, cargo, and territory. Two clean records with a local radius sit near the bottom; one at-fault claim in the last three years can double a single vehicle's premium. Compare that against the alternative the business is tempted by: leaving the vans on the owner's personal policy. Personal policies exclude or sublimit business use, and a claim discovered mid-settlement leaves both carriers pointing at each other. The commercial policy costs real money and exists for the exact claim the personal policy would have denied.
The driver file: MVRs, schedules, and re-rating
Commercial auto pricing is driver pricing. Carriers pull motor vehicle records at quoting and at renewal, and the file they see — violations, at-fault claims, license status per scheduled driver — moves the premium more than the vehicle list does. The management routine that keeps the file clean: run MVRs before adding any driver, schedule only employees who actually drive, remove departed drivers at the next renewal, and re-check records annually. One at-fault claim in the prior three years can double a single vehicle's premium; a DUI re-prices the whole fleet and can trigger non-renewal. The hire-and-schedule routine belongs to the first-employee checklist, and the liability side of the stack is in the general liability guide.
Related guides
The auto line connects to the payroll and cost pages that move it:
- BOP Insurance — the policy the HNOA endorsement usually rides on.
- Business Insurance: The Complete Guide — the full small-business coverage map.
- LLC Insurance — naming the entity on the title and the policy.
- Workers Comp Insurance — the driver-on-payroll side of the same file.
Sources
Frequently asked questions
When do I need commercial auto insurance?
When a vehicle is titled to the business, driven by employees, used for deliveries or transporting equipment or people for pay, or used heavily for business errands. Personal policies exclude livery, delivery, and employee driving — a claim during excluded use can be denied outright. Hired and non-owned auto (HNOA) covers the in-between cases cheaply.
What is hired and non-owned auto insurance (HNOA)?
Liability coverage for vehicles the business does not own: employees driving their personal cars on business errands (non-owned) and rented vehicles (hired). It is an endorsement on general liability or BOP policies, commonly $15–$50 per month — the cheapest fix for the most common small-business auto gap.
How much does commercial auto insurance cost?
Typically $100–$250 per month per vehicle for small businesses, scaling with vehicle type, driving records, radius of operation, and cargo. Delivery and heavy vehicles price higher; low-mileage service vehicles lower. FMCSA interstate filings and livery filings add requirements.
Does my personal policy cover business use of my car?
Partially at best: commuting is covered, but deliveries, transporting people for pay, and heavy business use are excluded or restricted — and employees driving your car is a different gap entirely. The claim-time discovery that the policy does not apply is the standard small-business auto disaster.
Does commercial auto cover my employee driving their own car for work?
Only through hired and non-owned auto (HNOA) coverage added to the policy. HNOA pays when an employee's personal car causes business-related damage or injury — the employee's own policy responds first, and HNOA backstops the business's liability. Without it, an errand-run crash can land on the company.
What happens if an undisclosed driver crashes the company van?
Permissive use usually keeps the claim covered — a licensed employee you allowed to drive is typically an insured. Problems compound when the driver was excluded on the policy, unlicensed, or operating outside described use: the carrier may deny, non-renew, or re-rate sharply. Schedule drivers accurately; undisclosed-driver disputes are avoidable ones.
How we researched this guide
Business insurance requirements are mostly statutory — workers comp is state law — so our guides separate legal requirements from prudent coverage.
- Workers-comp rules (who must carry, exemptions, monopolistic states) are verified against state statutes and NCCI classifications.
- General liability and BOP coverage mechanics are verified against standard policy forms and SBA guidance.
- Professional-liability explanations distinguish the claims-made trigger and tail options, because that's where businesses get caught.
- Industry examples use realistic claim scenarios published by insurers and courts, and we label estimates as estimates.
Where facts vary by state or insurer, we publish the range and the reason for the variation rather than a single misleading average. We do not sell insurance, take money from insurers for coverage, or publish claim amounts we cannot trace to a source.
Sources
The primary sources behind the facts on this page. Last verified November 10, 2026.
- U.S. Small Business Administration (SBA) — which policies a business legally needs and how to buy them.
- OSHA — Occupational Safety and Health Administration — workplace safety rules that drive workers-compensation obligations.
- NCCI — National Council on Compensation Insurance — workers-comp class codes and rate filings used in most states.
- NAIC — National Association of Insurance Commissioners — model regulations, consumer guides, and industry statistics.
- Find your state insurance regulator (NAIC directory) — every state insurance department — the authority for your state's rules and complaint filing.
- Insurance Information Institute (III) — industry statistics and consumer explainers we cross-check against regulator publications.
Rules that vary by state are verified against the state insurance department's consumer pages — find yours via the NAIC directory above.
Keep reading

Business Insurance: The Complete Guide
Business insurance explained: the general liability, BOP, workers comp, E&O, and commercial auto policies a small business needs — and what each costs per month.
Read guide
What Is General Liability Insurance? Coverage and Costs
General liability insurance pays third-party injury and property damage claims; small businesses pay $40–$100 per month for the standard $1M/$2M limits.
Read guide
LLC Insurance: What Coverage Your Company Actually Needs
LLC insurance covers what the liability shield does not — your own negligence, uninsured claims — starting at $40–$100 per month for general liability.
Read guide
How Much Is Business Insurance? Costs by Policy and Business Type
Small business insurance runs $40–$100 per month for general liability and $60–$200 for a BOP, with a small employer's full stack at $150–$600 per month.
Read guide
Car Insurance: The Complete Guide
Car insurance bundles liability, collision, comprehensive, and medical coverage — this guide explains state minimums, full coverage, and how to lower the premium.
Read guide
Law Firm Insurance: Legal Malpractice and the Practice Stack
Law firm insurance centers on legal malpractice at $1,500–$5,000 per year per attorney, plus cyber for client confidentiality and general liability for the office.
Read guide